Corporate tax departments frequently struggle to shield breakthrough tax minimization strategies from public exposure or competitor replication during collaborative ventures. In an era of heightened regulatory scrutiny and aggressive auditing, safeguarding these proprietary methodologies has become both more critical and increasingly complex.
Successfully securing this intellectual property grants enterprises a sustainable financial advantage, transforming legal defense into a strategic asset. However, a standard, one-size-fits-all non-disclosure agreement is rarely sufficient; robust protection stipulates that legal frameworks must be precisely aligned with evolving tax codes. For instance, protecting proprietary cross-border transfer pricing models or specialized R&D tax credit calculators requires highly customized confidentiality provisions.
This article outlines how to implement specialized confidentiality agreement templates, exploring essential protective clauses, jurisdictional nuances, and best practices for securing your firm's most valuable corporate tax innovations.
Corporate Tax Planning Non-Disclosure Agreement
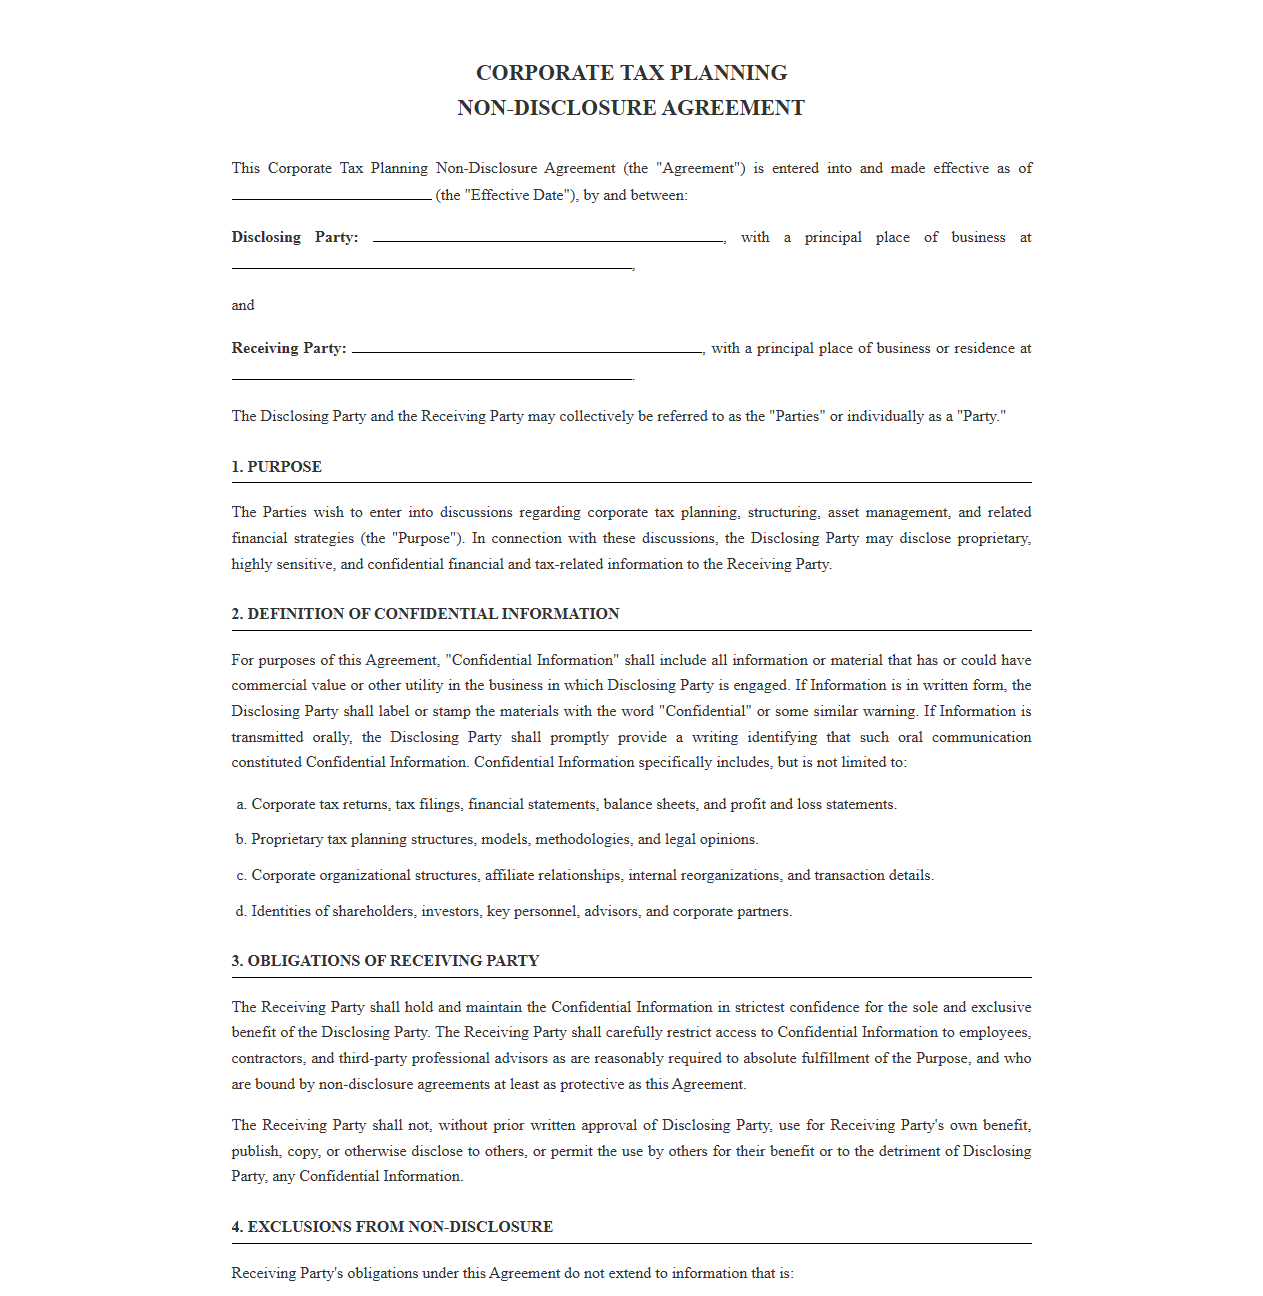 Download: .PDF
Confidentiality Agreement for Strategic Corporate Tax Advisory
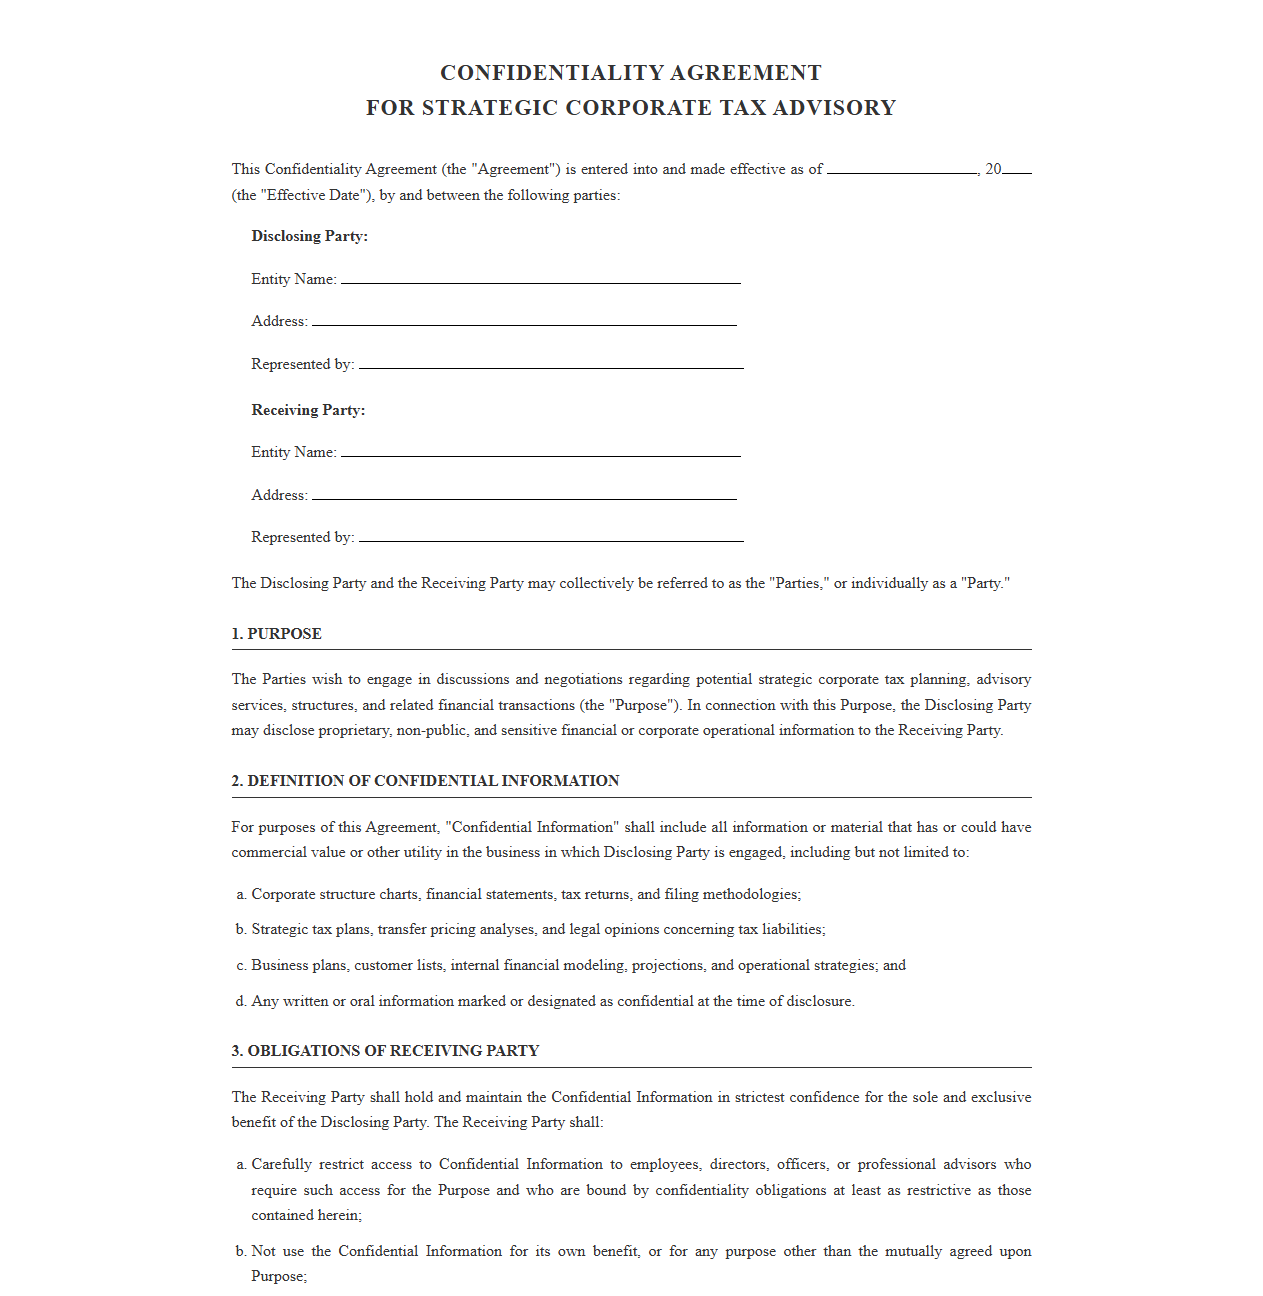 Download: .PDF
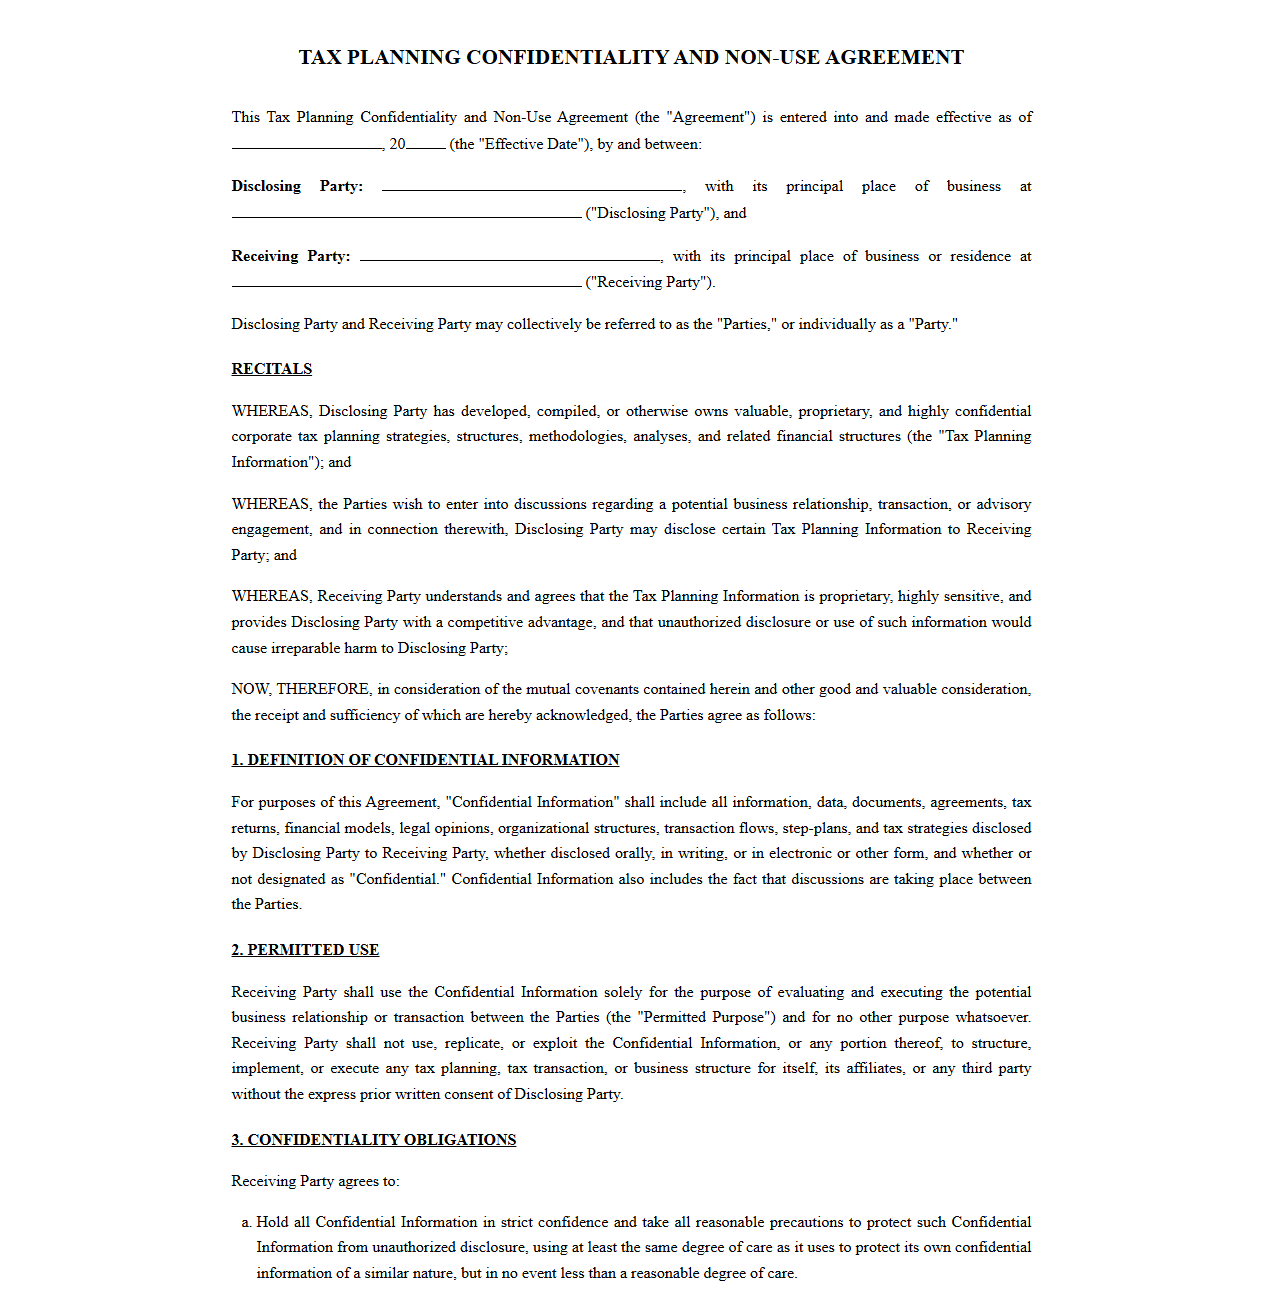
Tax Planning Confidentiality and Non-Use Agreement
 Download: .PDF
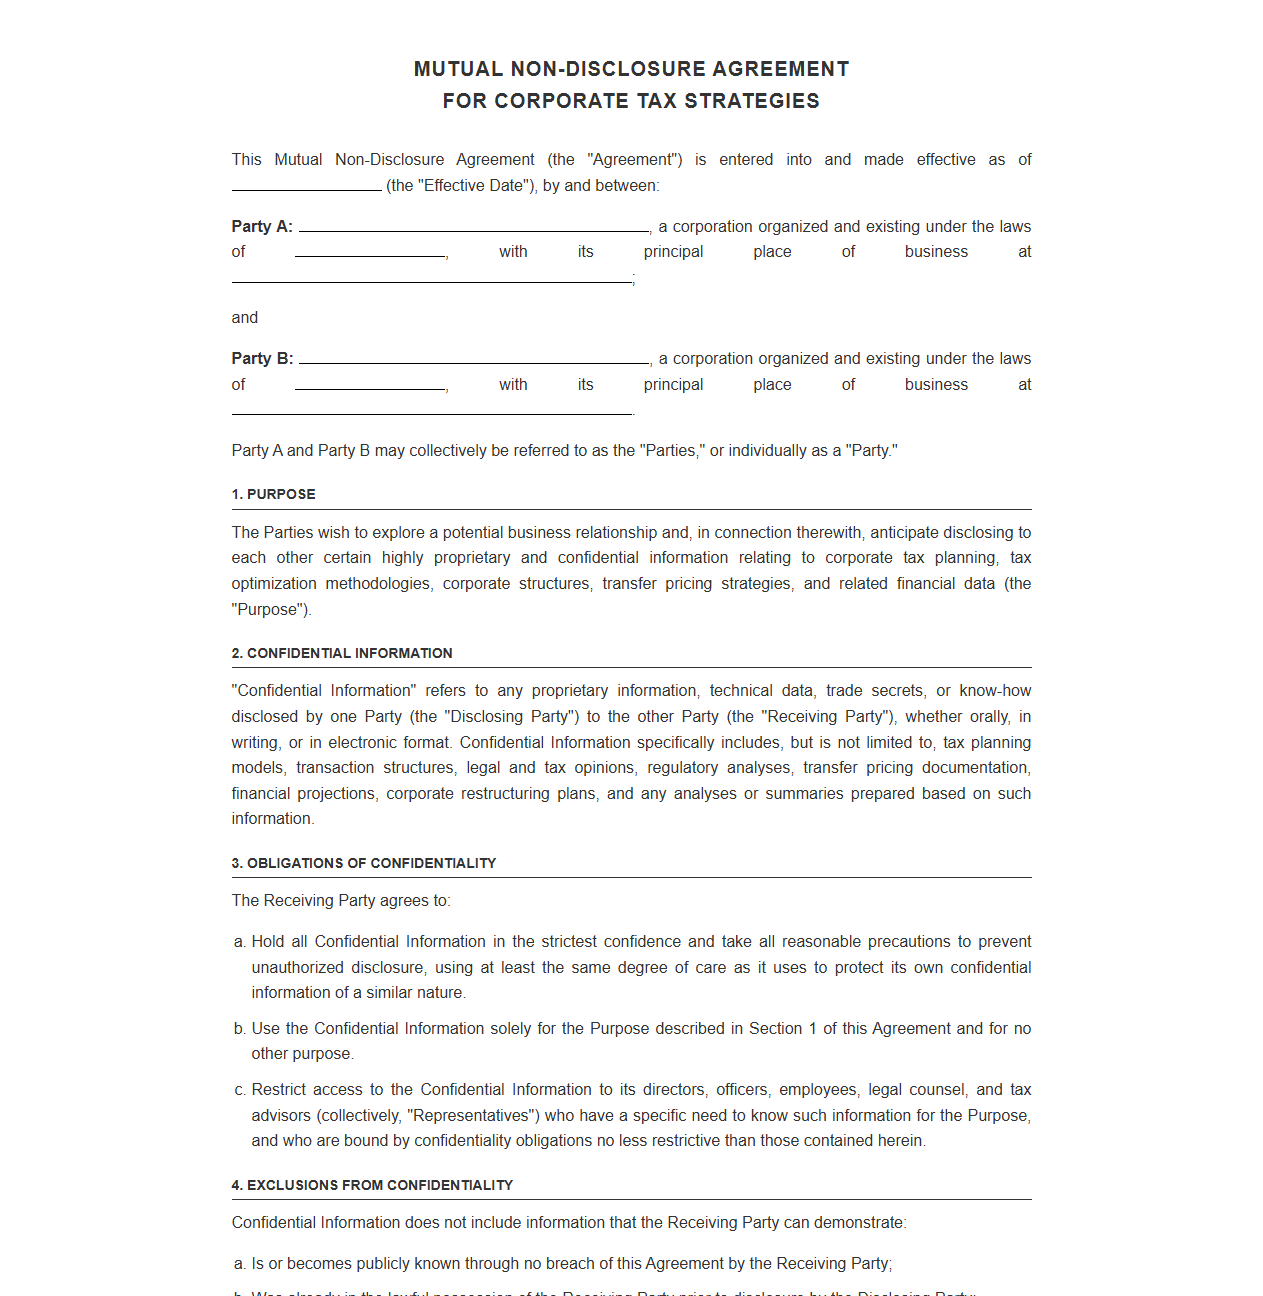
Mutual Non-Disclosure Agreement for Corporate Tax Strategies
 Download: .PDF
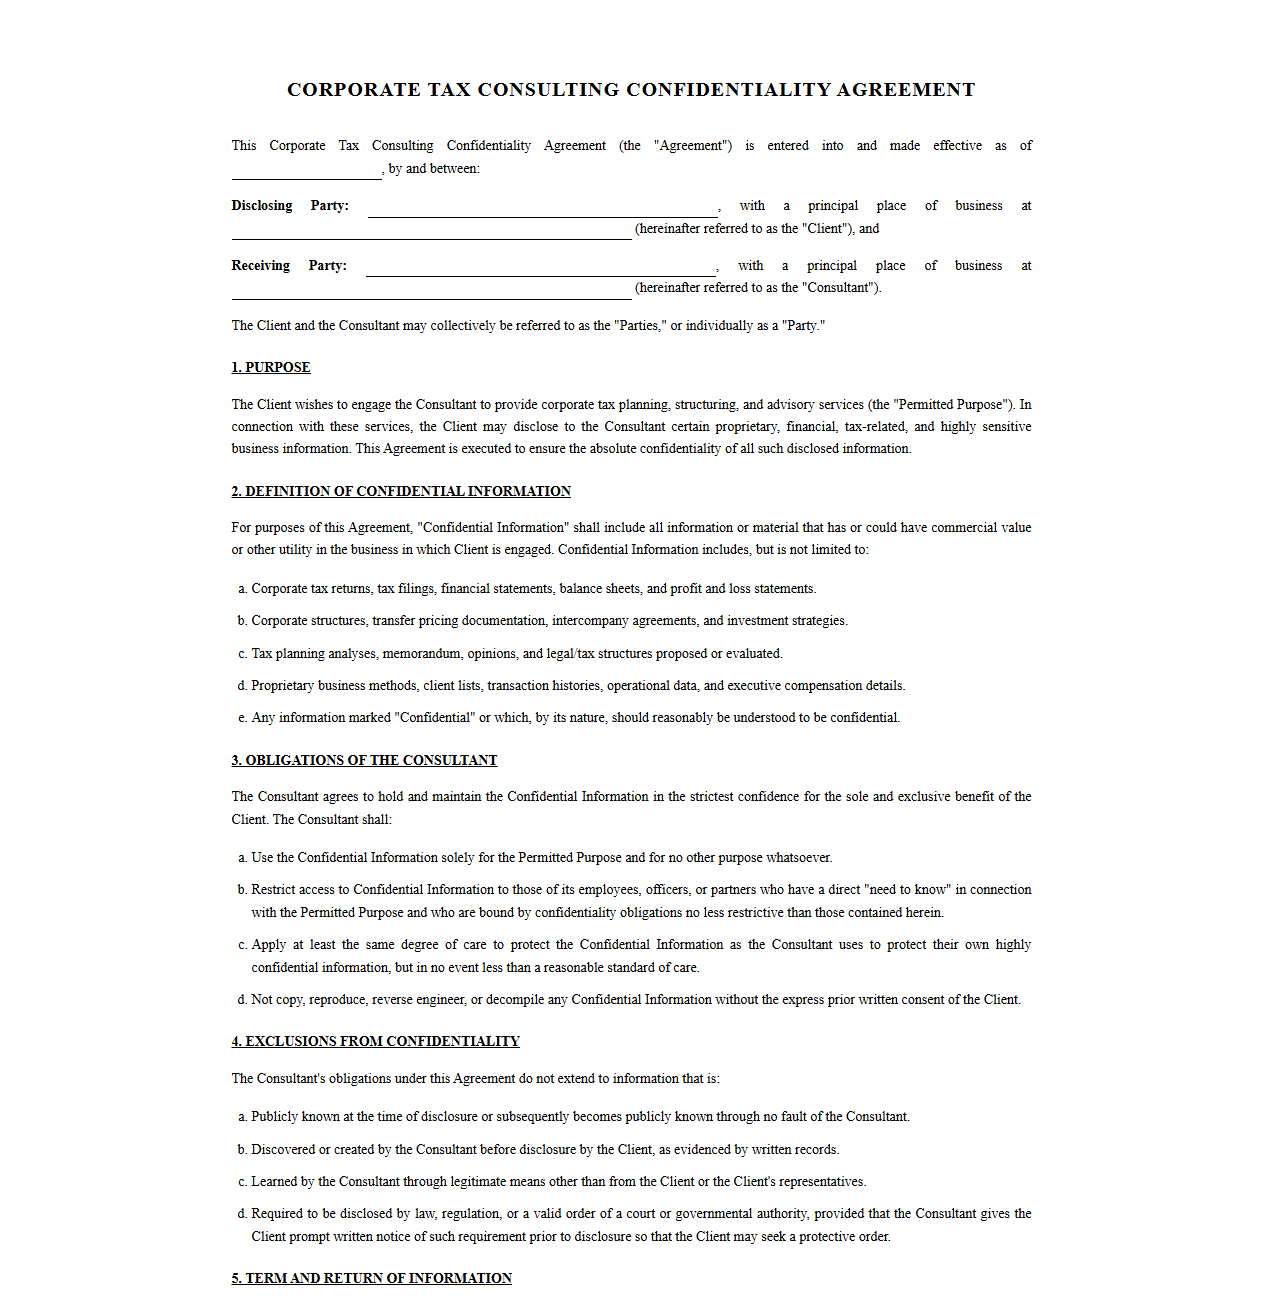
Corporate Tax Consulting Confidentiality Agreement
 Download: .PDF
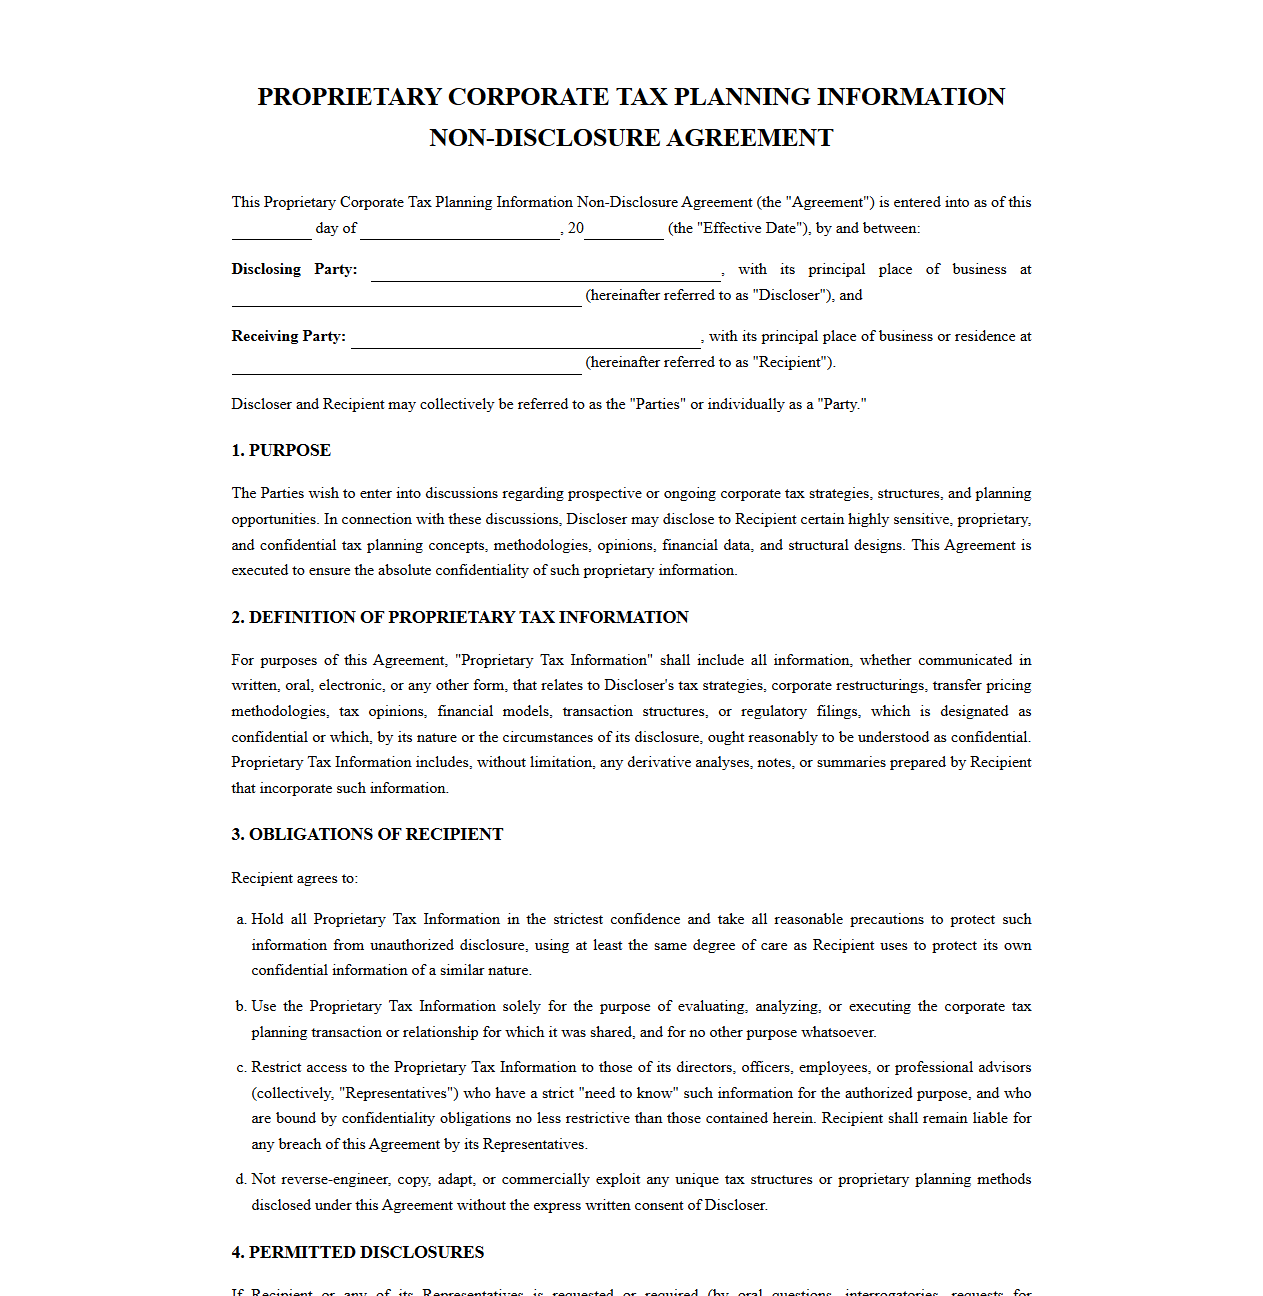
Proprietary Tax Planning Information Non-Disclosure Agreement
 Download: .PDF
Confidentiality Agreement for Corporate Tax Restructuring
 Download: .PDF
Corporate Tax Minimization Strategy Confidentiality Agreement
 Download: .PDF
The High Stakes of Proprietary Corporate Tax Strategies
Innovative corporate tax strategies provide a significant competitive edge in today's global market. By legally minimizing tax liabilities, companies free up capital for reinvestment, research, and expansion. However, these highly sophisticated structures are vulnerable to replication by competitors if leaked. Protecting these intellectual assets through robust confidentiality agreements is vital for corporate financial security. The leakage of a proprietary framework represents severe financial exposure and the potential loss of a unique market advantage.
Defining the Corporate Tax Non-Disclosure Agreement
A tax-specific Non-Disclosure Agreement (NDA) is a specialized legal instrument designed to protect proprietary tax planning methods. Unlike standard commercial confidentiality agreements that generally protect broad business trade secrets, a tax NDA focuses narrowly on proprietary financial models, transaction structures, and specific legal opinions. It operates under the framework of attorney-client privilege and work-product doctrine to ensure that highly technical tax engineering remains shielded from unauthorized eyes while preserving the precedential value of the firm's bespoke tax positions.
Essential Clauses: Outlining "Proprietary Tax Information"
To ensure maximum protection, the agreement must clearly define what constitutes "Proprietary Tax Information." A vague definition risks making the NDA unenforceable in court. The agreement must explicitly cover several critical assets:
- Proprietary algorithms and financial modeling software used to project tax liabilities.
- Bespoke structuring advice and step-transaction blueprints for mergers and acquisitions.
- Formal tax opinion letters, memoranda of law, and private letter ruling applications.
- Written and oral communications with external tax advisors, CPA firms, and legal counsel.
Balancing Confidentiality with IRS Disclosure Requirements
There is an inherent tension between strict corporate confidentiality and mandatory tax shelter disclosure rules enforced by tax authorities. Under IRS regulations, particularly regarding "confidential transactions" under IRC Section 6011, agreements that restrict disclosure of the tax treatment or tax structure of a transaction can trigger onerous reporting requirements and severe penalties. To avoid these pitfalls, drafters must include a carefully constructed carve-out clause that allows for legal compliance without voiding the entire agreement.
"Notwithstanding any provision in this Agreement to the contrary, each party hereto (and each employee, representative, or other agent of such party) may disclose to any and all persons, without limitation of any kind, the tax treatment and tax structure of the transaction and all materials of any kind (including opinions or other tax analyses) that are provided to the taxpayer relating to such tax treatment and tax structure."
Standard Exclusions and Reasonable Durations
A legally enforceable tax NDA must balance protection with reasonableness. It cannot cover information that is already in the public domain or independently developed without reference to the proprietary strategy. Furthermore, defining the duration of protection requires careful thought in a rapidly shifting legislative landscape. Courts routinely strike down indefinite confidentiality terms, making reasonable, time-bound limitations essential. Typically, a duration aligned with the statute of limitations for tax audits plus an additional buffer is deemed enforceable.
Remedies and Enforcement in the Event of a Breach
When a proprietary tax strategy is compromised, immediate and decisive action is necessary to mitigate damages. Because the financial impact of a lost tax advantage is highly complex to quantify, a structured response framework must be established within the agreement.
- Securing immediate injunctive relief to halt any further unauthorized disclosure or implementation of the leaked tax strategy.
- Enforcing contractually specified liquidated damages to bypass the difficulty of proving exact financial valuation loss.
- Calculating the actual diminished value of the proprietary tax advantage based on potential competitor adoption and regulatory exposure.
Implementing NDA Templates into the Tax Planning Workflow
To successfully safeguard intellectual assets, companies must systematically integrate confidentiality protocols into their routine tax planning workflows. NDAs should not be treated as an afterthought; they must be executed before any sensitive discussions or proprietary data transmissions commence.
When engaging with outside counsel, specialized accounting firms, or internal M&A teams, establish a rigid pipeline. First, execute the tax-specific NDA prior to sharing any financial models or transaction blueprints. Second, clearly label all shared documents as proprietary and confidential. Third, conduct periodic reviews of active agreements to ensure compliance with evolving regional tax regulations.
Leave a comment