Forensic accountants and legal teams constantly battle the risk of catastrophic data leaks that can compromise high-stakes corporate investigations and destroy client trust. Balancing rigorous financial tracing with stringent data privacy regulations requires a highly structured legal framework before any sensitive auditing begins. Implementing robust privacy agreements grants investigators the ironclad protection needed to secure proprietary financial data during deep-dive audits.
While these templates serve as vital foundational frameworks, practitioners must recognize that they require careful tailoring to fit specific jurisdictional laws. For example, deploying specialized Non-Disclosure Agreements (NDAs) for whistleblowers and Kovel letters for attorney-client privilege offers concrete proof of rigorous security standards. Below, we examine the essential privacy templates every forensic firm needs to shield their investigations from exposure and ensure compliance.
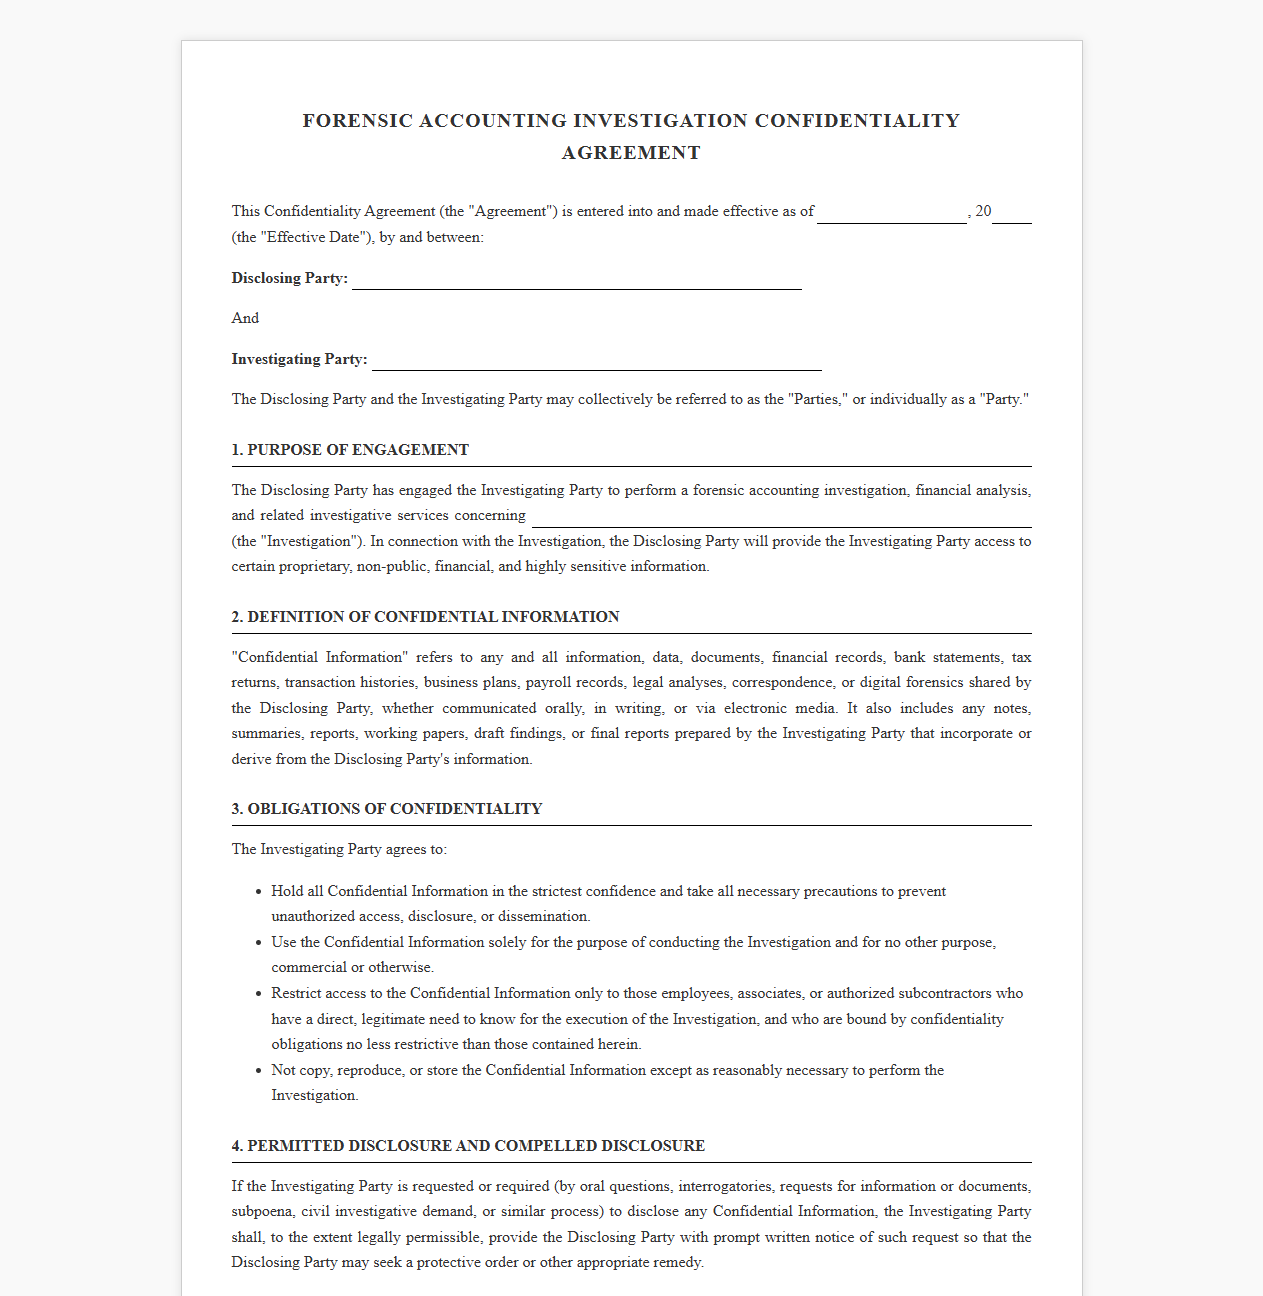
Forensic Accounting Investigation Confidentiality Agreement Template
 Download: .PDF
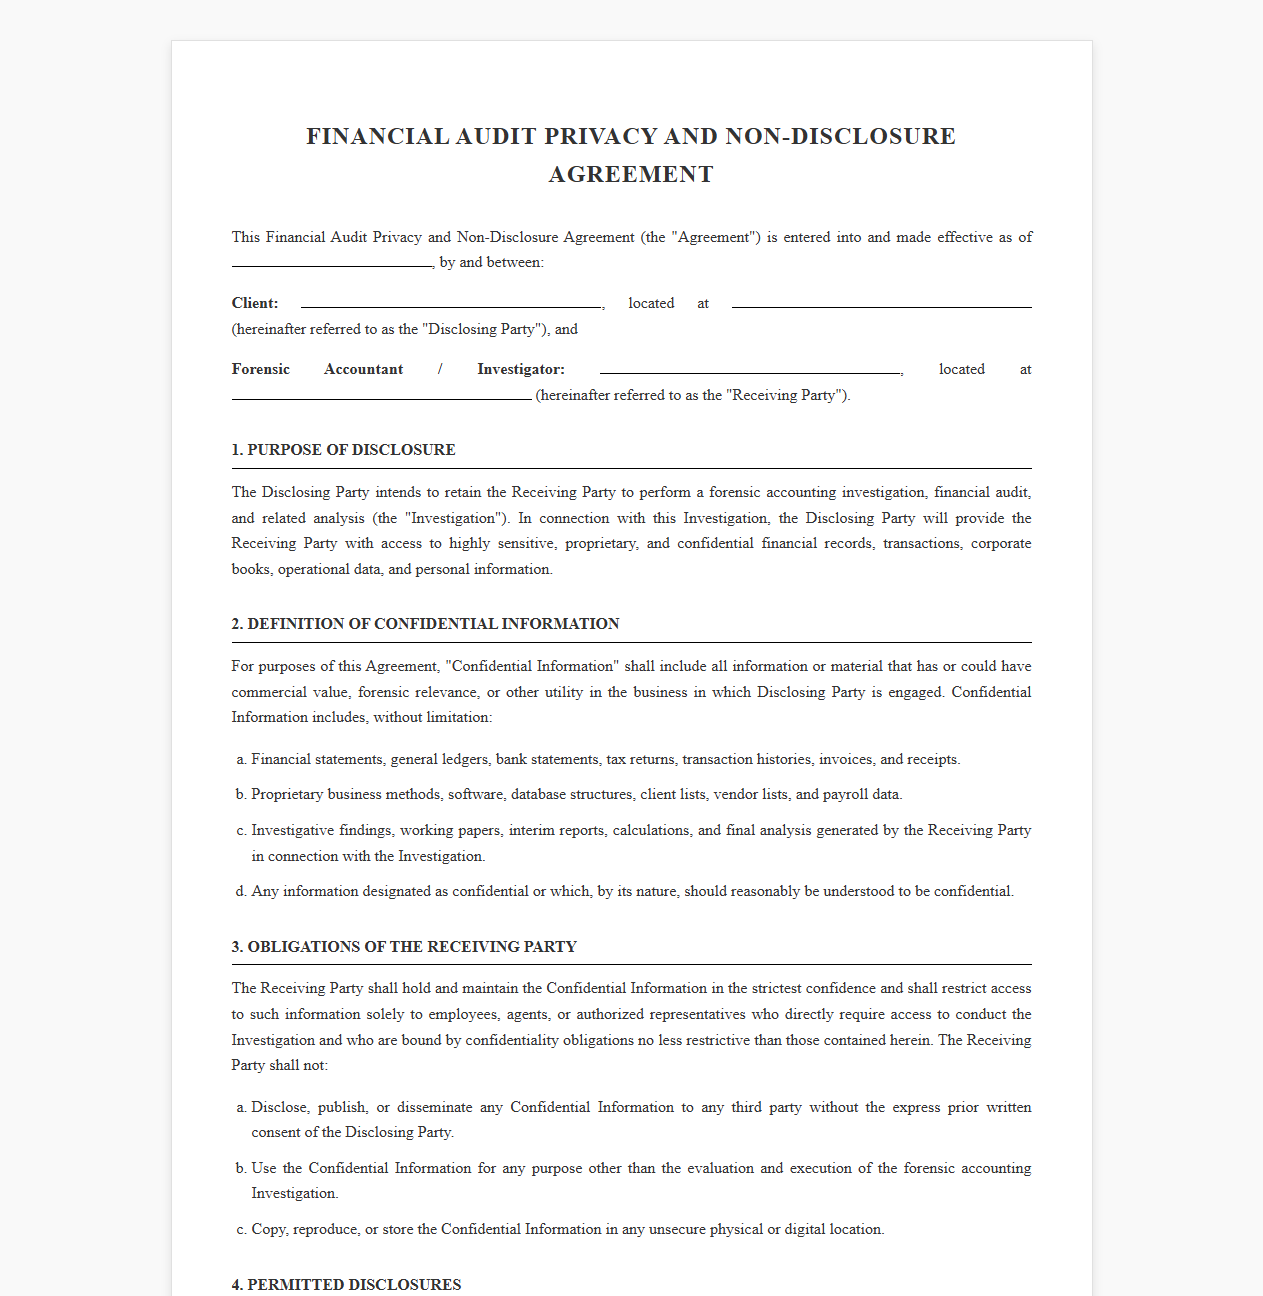
Financial Audit Privacy and Non Disclosure Agreement
 Download: .PDF
Forensic Accounting Services Confidentiality and Privacy Agreement
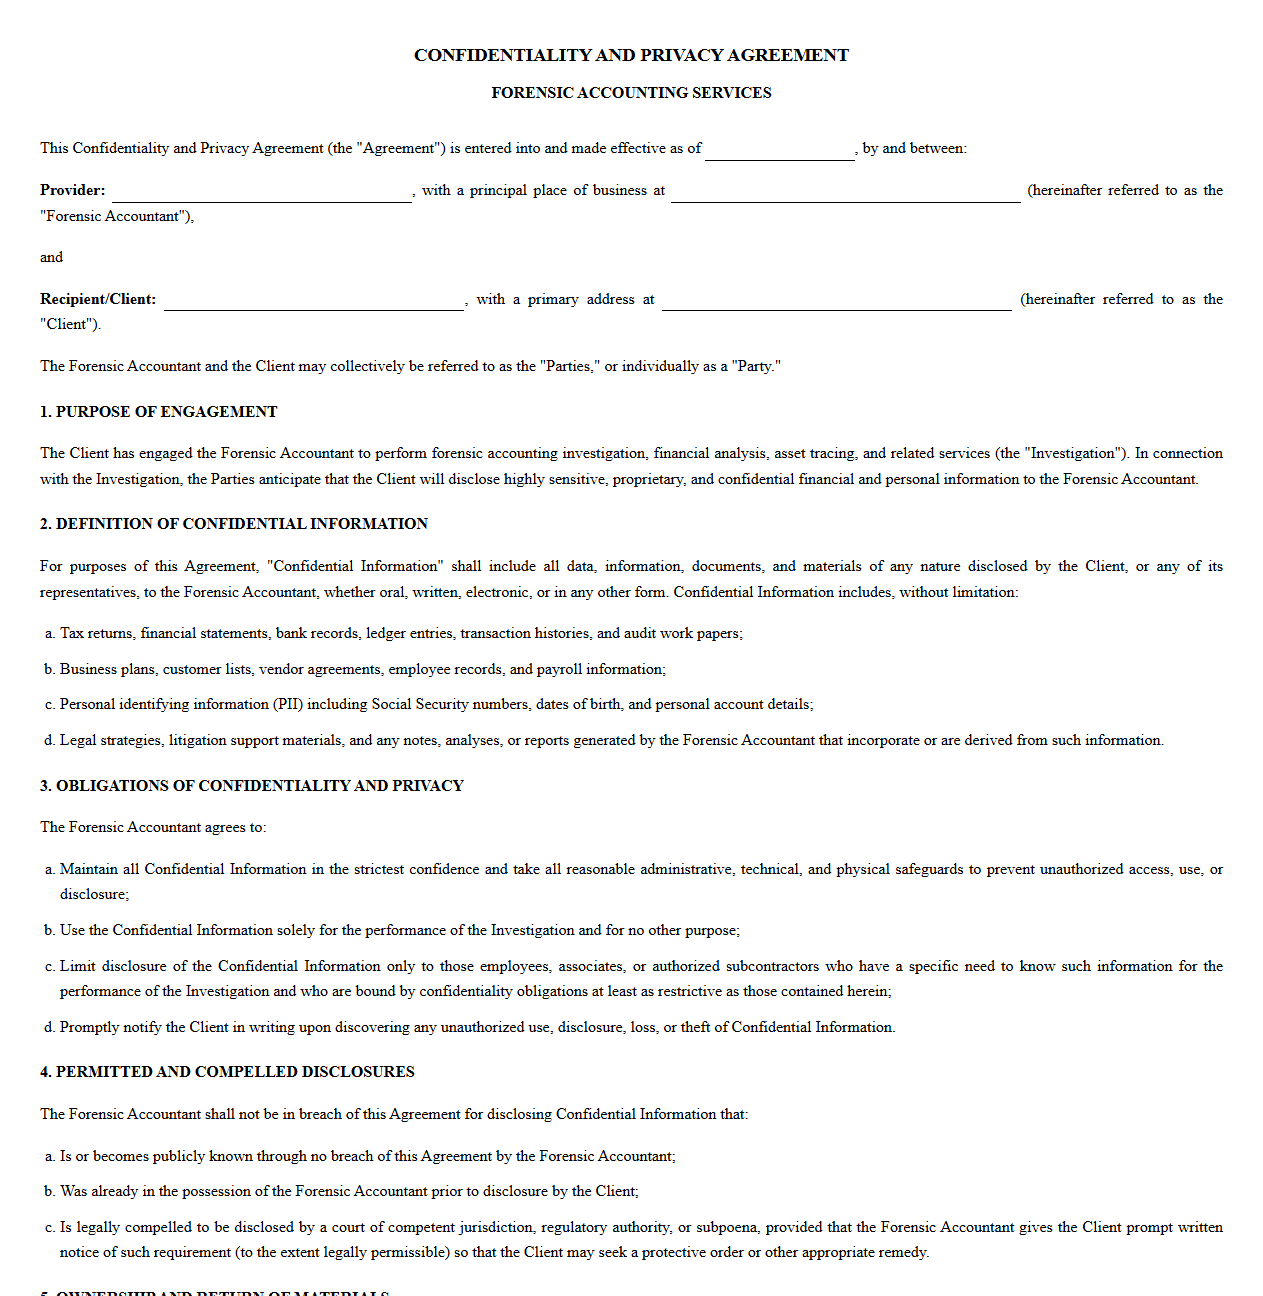 Download: .PDF
Confidentiality Agreement for Forensic Financial Investigations
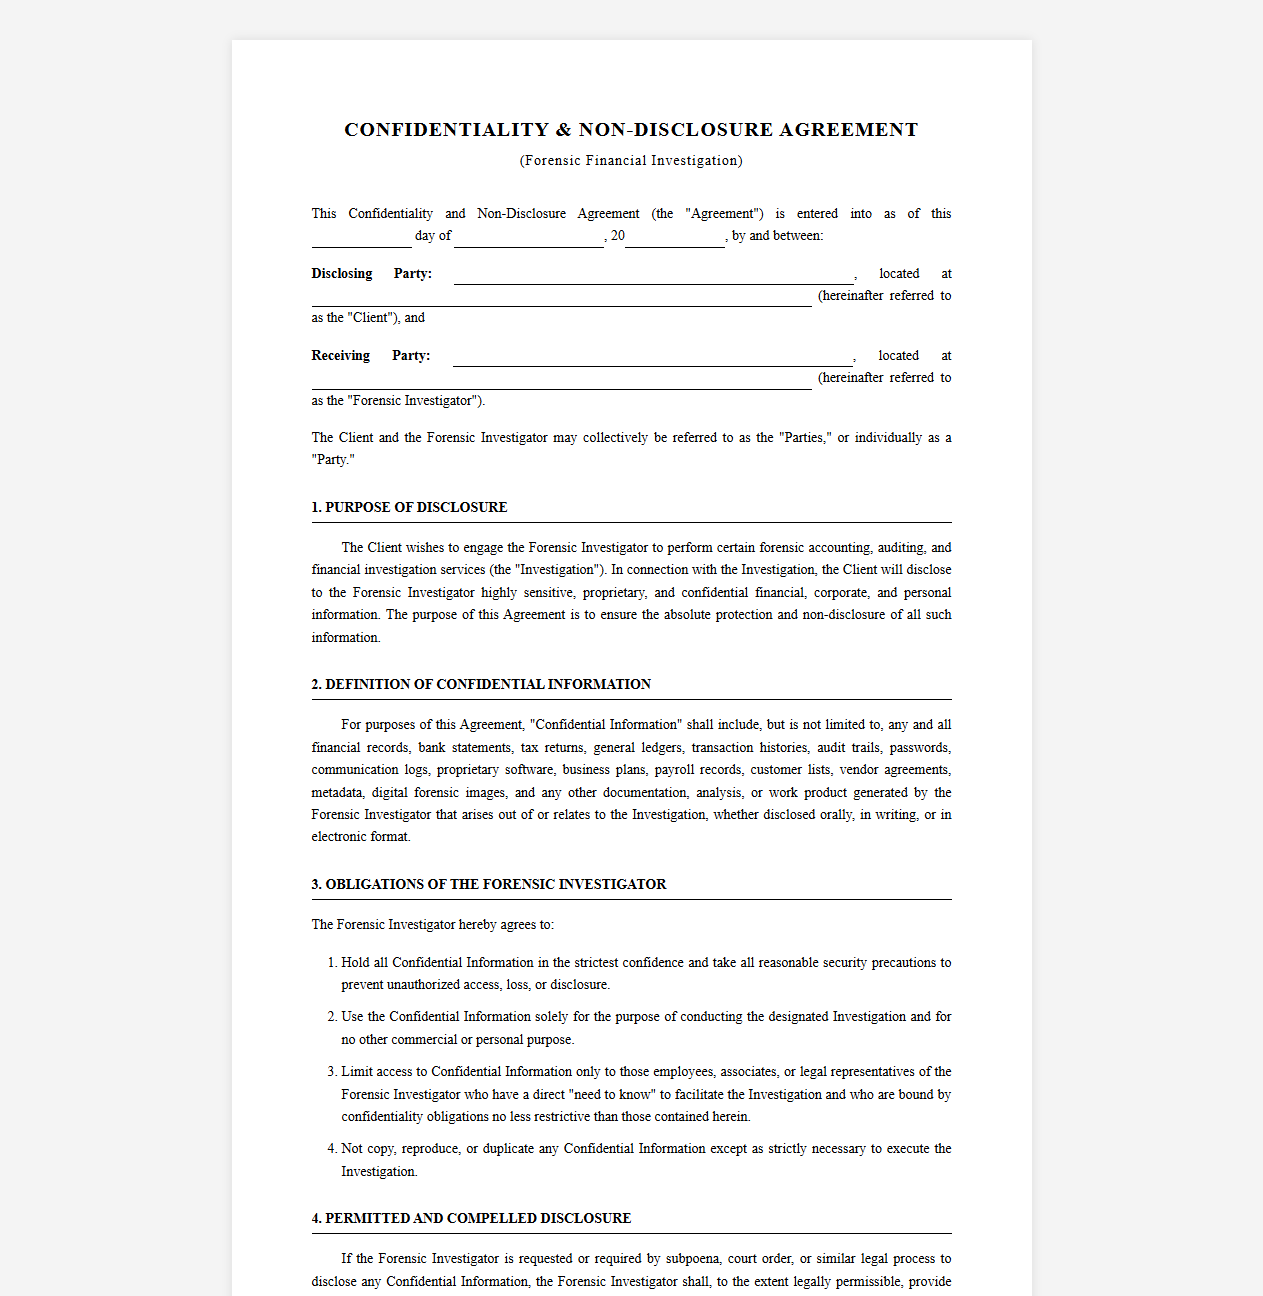 Download: .PDF
Financial Investigation Privacy and Data Security Agreement
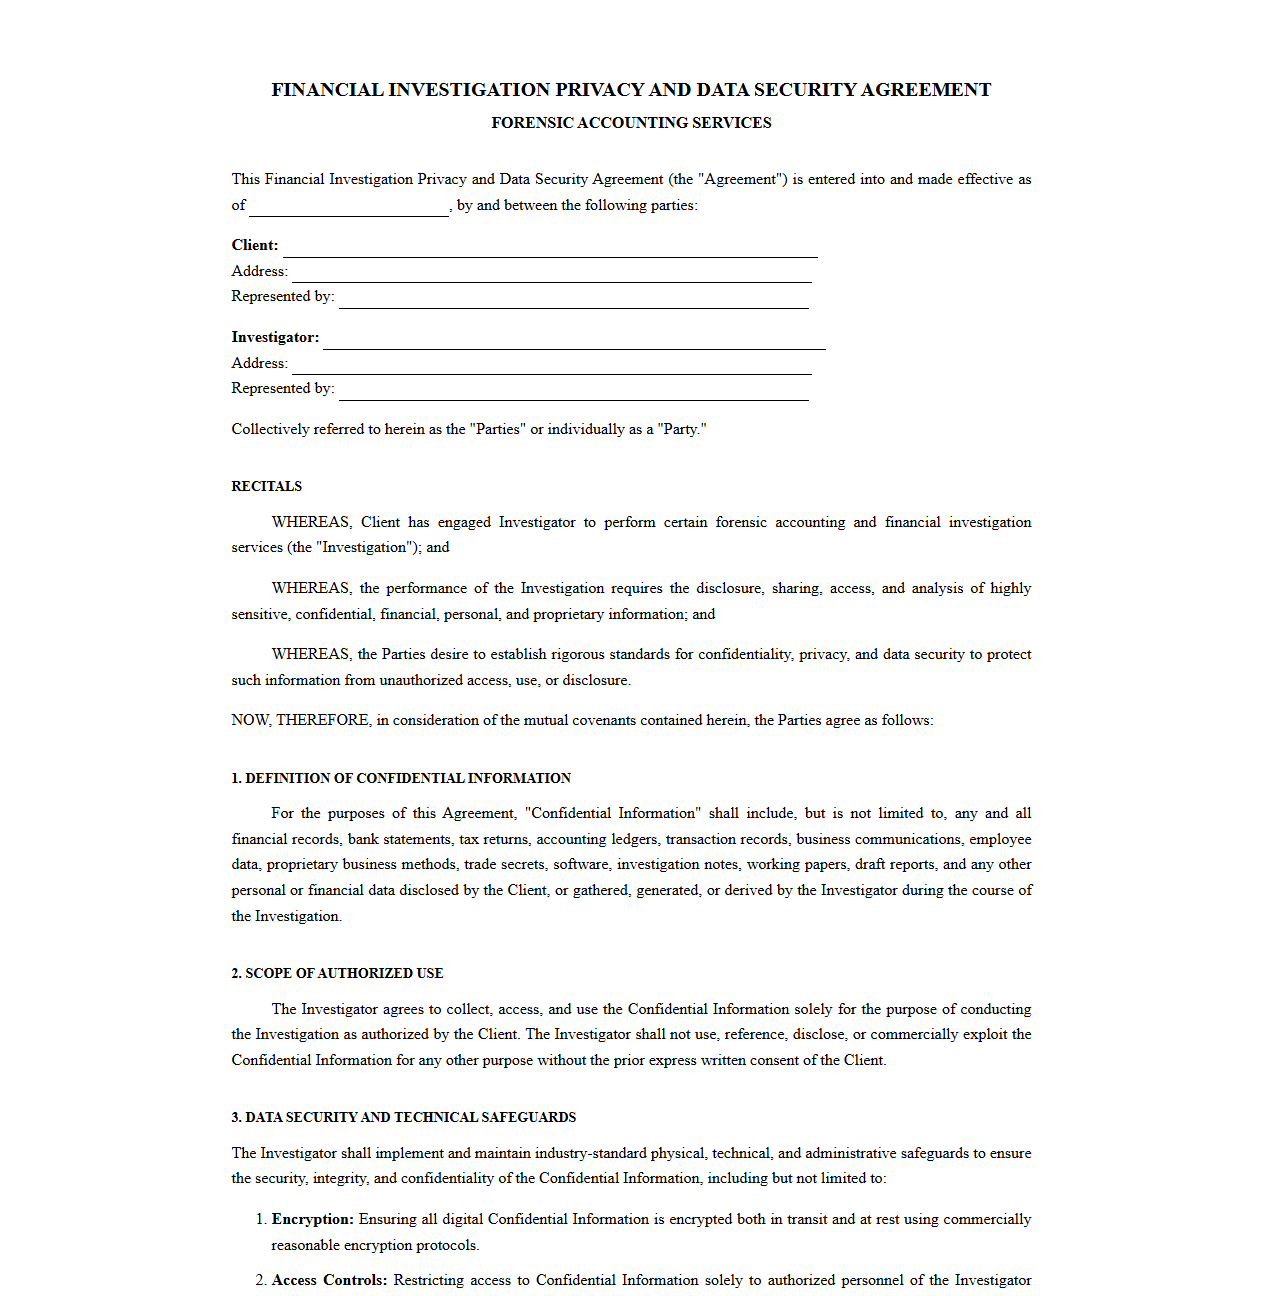 Download: .PDF
Forensic Audit Non Disclosure and Privacy Agreement
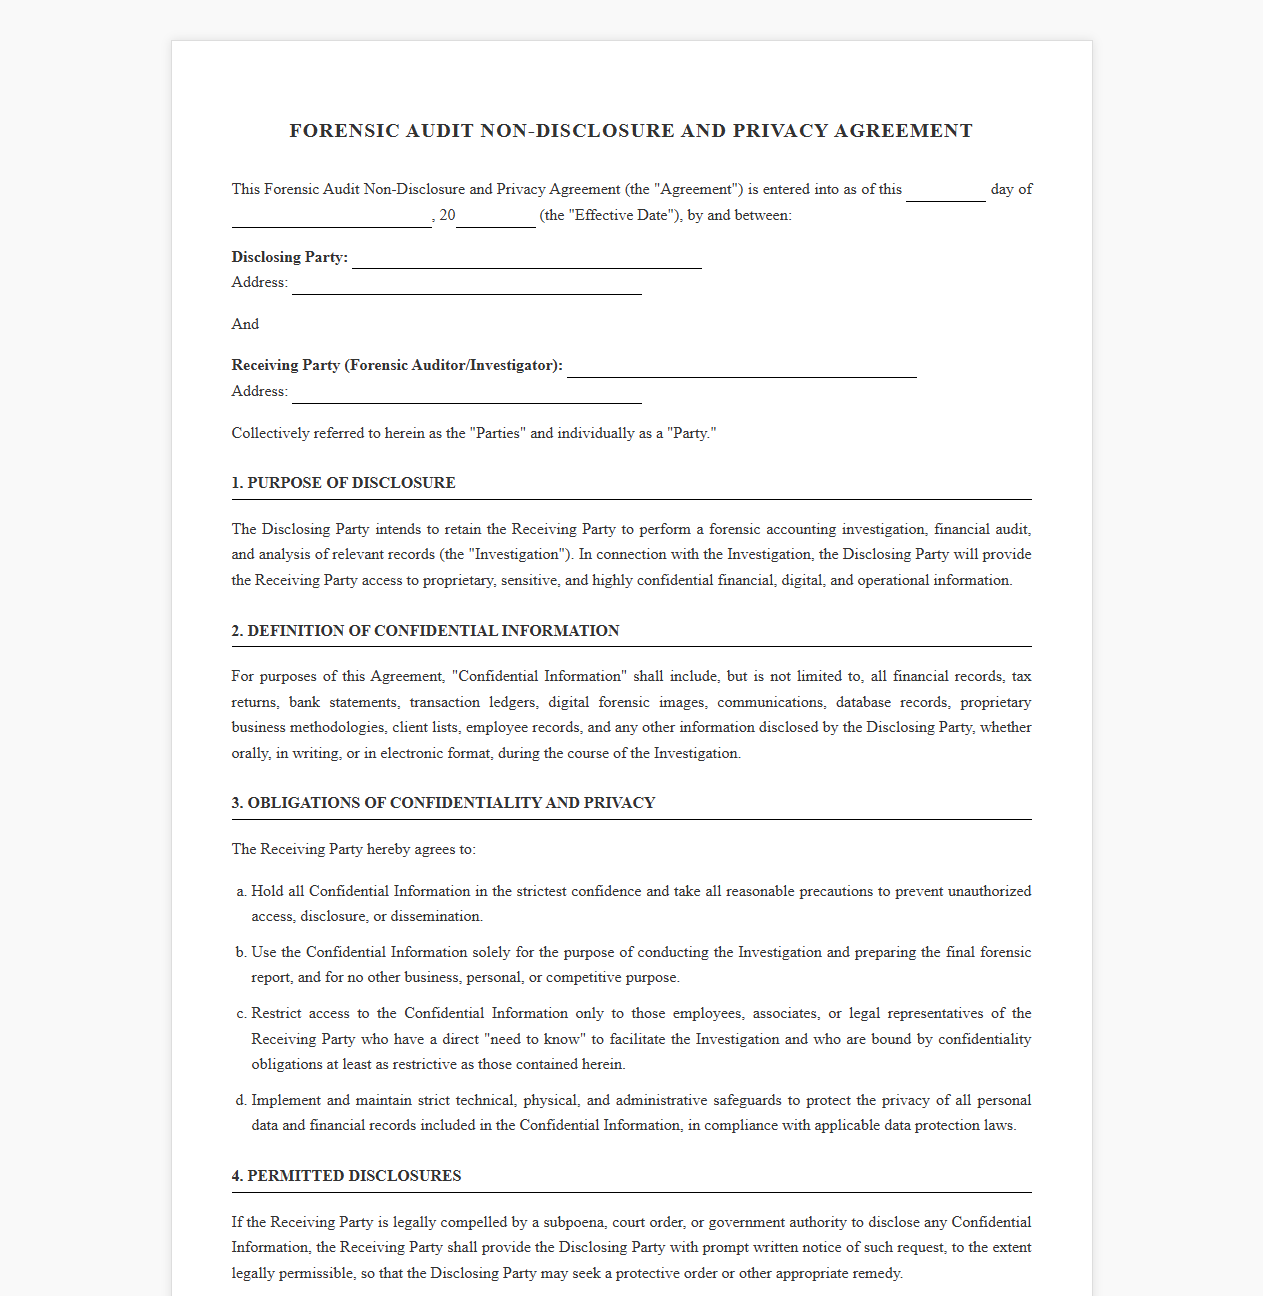 Download: .PDF
Forensic Accounting Investigation Privacy and Secrecy Agreement
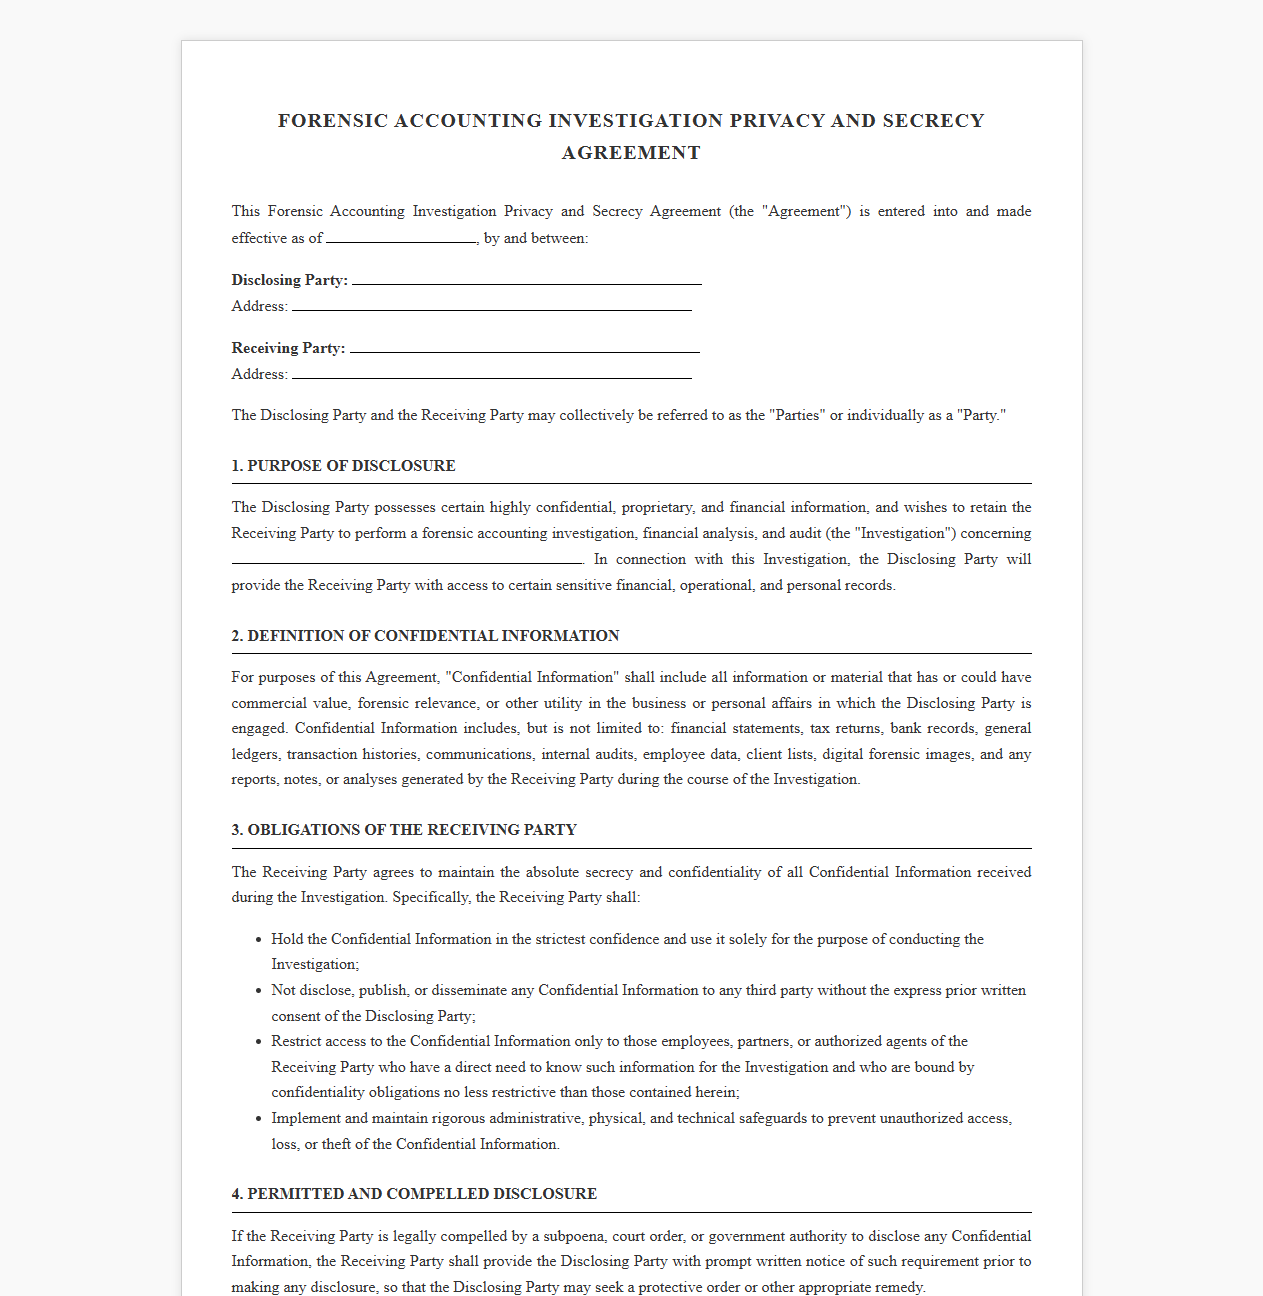 Download: .PDF
Financial Forensic Investigation Data Privacy Agreement
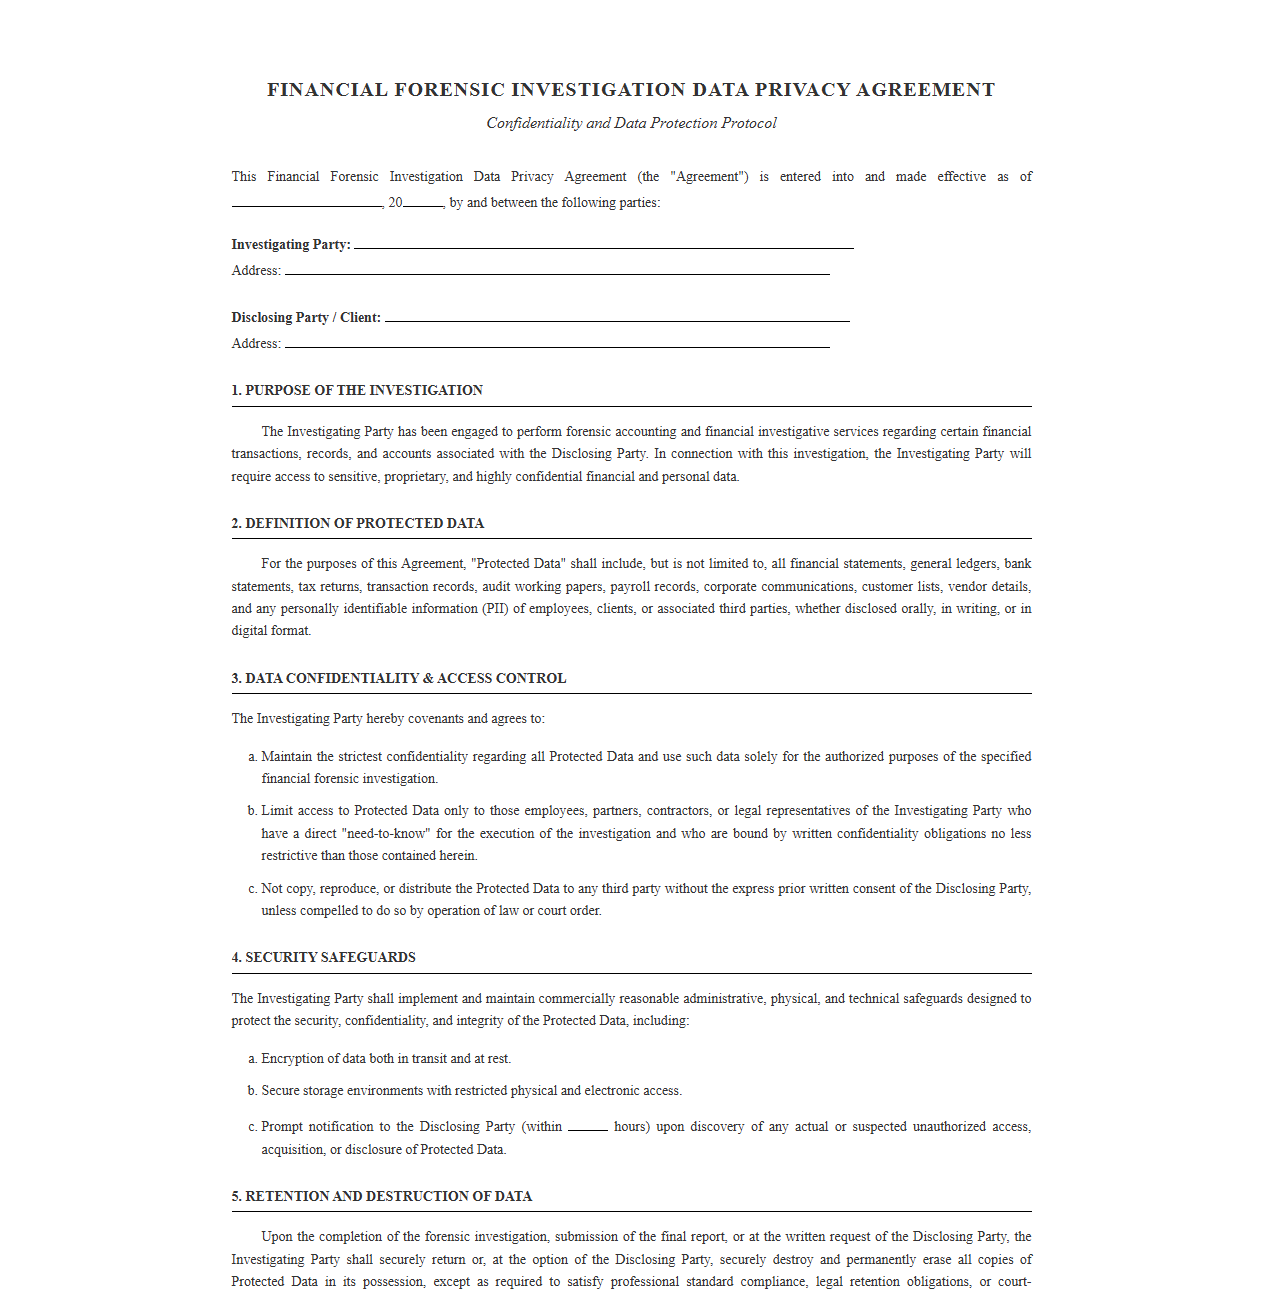 Download: .PDF
The Critical Role of Confidentiality in Forensic Accounting
Forensic accounting investigations delve into the most sensitive layers of an organization's financial operations. Because these investigations often involve allegations of fraud, embezzlement, or corporate misconduct, maintaining absolute confidentiality is paramount. A single data leak can ruin corporate reputations, compromise ongoing litigation, or alert bad actors, allowing them to destroy crucial evidence. To prevent these catastrophic outcomes, forensic accountants must implement robust privacy agreements right from the start. Protecting sensitive financial data safeguards the integrity of the investigation and ensures that findings remain admissible and secure.
Unilateral and Mutual NDAs for Client Onboarding
When initiating a forensic investigation with a new corporate client, establishing a formal Non-Disclosure Agreement (NDA) is the first line of defense. Depending on the nature of the engagement, firms may use unilateral or mutual NDAs. To ensure maximum legal protection, these agreements must contain highly specific clauses:
- Definition of Confidential Information: Clearly identifying what data, documents, and verbal communications are protected under the agreement.
- Permitted Use of Disclosure: Restricting the use of the shared information solely to the scope of the forensic audit.
- Exclusions from Confidentiality: Outlining specific scenarios where disclosure is permitted, such as information that is already public domain or legally subpoenaed.
- Term and Termination: Specifying the duration of the confidentiality obligations, which often extend long after the active investigation concludes.
Joint Defense Agreements in Multi-Party Financial Audits
Complex corporate investigations often involve multiple parties, such as parent corporations, subsidiaries, and separate legal teams. In these multi-party scenarios, Joint Defense Agreements (JDAs) or Common Interest Agreements are essential tools to protect shared legal privilege.
"A Joint Defense Agreement allows separate parties facing a common legal threat to share highly confidential forensic findings and strategy without waiving the attorney-client privilege or work-product doctrine."
Without a formal JDA in place, sharing sensitive financial analysis among co-defendants or collaborative parties could legally destroy the confidentiality of those documents, making them discoverable by opposing counsel in court proceedings.
Staff and Subcontractor Secrecy Protocols
An investigation is only as secure as its weakest link. Internal staff, contract investigators, and third-party IT specialists all require rigorous screening and strict privacy protocols to prevent accidental disclosures.
Firms must mandate that everyone involved in the engagement signs comprehensive secrecy agreements. These agreements must contain specific clauses targeting data handling protocols, non-solicitation of clients, and immediate reporting of data breaches. For external contractors and IT specialists, these contracts must explicitly state that all work completed remains the sole property of the forensic firm, and no investigative techniques or client data may be retained or discussed outside the scope of the project.
- Mandatory training on secure physical and digital document handling.
- Strict access controls limiting file exposure to authorized personnel only.
- Strict penalties for unauthorized disclosures, up to and including immediate termination and legal action.
Data Security and Cloud Storage Privacy Addendums
In the modern digital landscape, forensic accountants routinely handle massive quantities of electronic evidence. Ensuring the secure transmission, processing, and cloud storage of this data requires dedicated Data Protection Addendums (DPAs).
When drafting a DPA with cloud storage providers or specialized software vendors, forensic firms must require end-to-end encryption, multi-factor authentication, and isolated server hosting. The DPA should explicitly state that the vendor acts strictly as a data processor and has no rights to access, index, or analyze the client's financial records. Additionally, the agreement must mandate immediate notification of any suspected security breaches and outline clear protocols for the secure deletion of all data once the retention period ends.
Information Sharing Protocols with Law Enforcement and Regulators
During a financial investigation, forensic accountants may need to share findings with external authorities such as the SEC, IRS, or local law enforcement. Managing this handoff requires a careful framework to avoid inadvertently waiving privilege over the broader investigation.
To navigate these high-stakes transitions, firms utilize structured information sharing protocols and limited-waiver agreements. These frameworks define exactly what evidence is being handed over and establish that the disclosure is made under legal compulsion or a specific regulatory pathway, protecting the rest of the investigative file from public disclosure acts.
Best Practices for Implementing and Reviewing Privacy Agreements
To maintain a defensible security posture, forensic accounting firms must regularly audit and update their confidentiality templates. Laws surrounding data privacy and legal privilege evolve, making outdated templates a liability.
Firms should adopt the following actionable checklist to ensure their privacy agreements remain legally binding and protective:
- Conduct Annual Legal Reviews: Have qualified legal counsel review all NDA, JDA, and subcontractor agreement templates to align with updated state and federal privacy statutes.
- Enforce Role-Based Access: Only grant data access to team members who have signed the specific project-level confidentiality agreements.
- Audit Subcontractor Compliance: Regularly verify that third-party IT partners and contract investigators are adhering to the security standards outlined in their privacy addendums.
- Maintain a Centralized Agreement Registry: Keep an organized database of all active NDAs, including their expiration dates and unique terms, to avoid accidental breaches of contract.
Adhering to these strict standards ensures that forensic firms protect their clients, shield their work product, and preserve the integrity of their findings from start to finish.
Leave a comment