Accountants today face unprecedented professional exposure. As trusted financial advisors, a single perceived misstep in estate management or corporate restructuring can trigger devastating liability claims. While standard professional indemnity insurance offers a baseline safety net, relying solely on commercial policies overlooks the heightened, personal exposures associated with direct fiduciary roles.
Implementing structured Fiduciary Duty Indemnity Agreement Templates grants practitioners a robust, legally binding shield that proactively mitigates these risks. However, these agreements must be framed with careful stipulation; they cannot legally indemnify against gross negligence or fraudulent misconduct. To be effective, templates must feature concrete protections, such as explicit clauses covering third-party litigation expenses and client-initiated breach of duty disputes.
In this guide, we will analyze the essential clauses your templates must contain, examine key legal limitations, and provide actionable steps to integrate these agreements into your practice's risk-management strategy.
Accountant Fiduciary Duty Indemnity Agreement Template
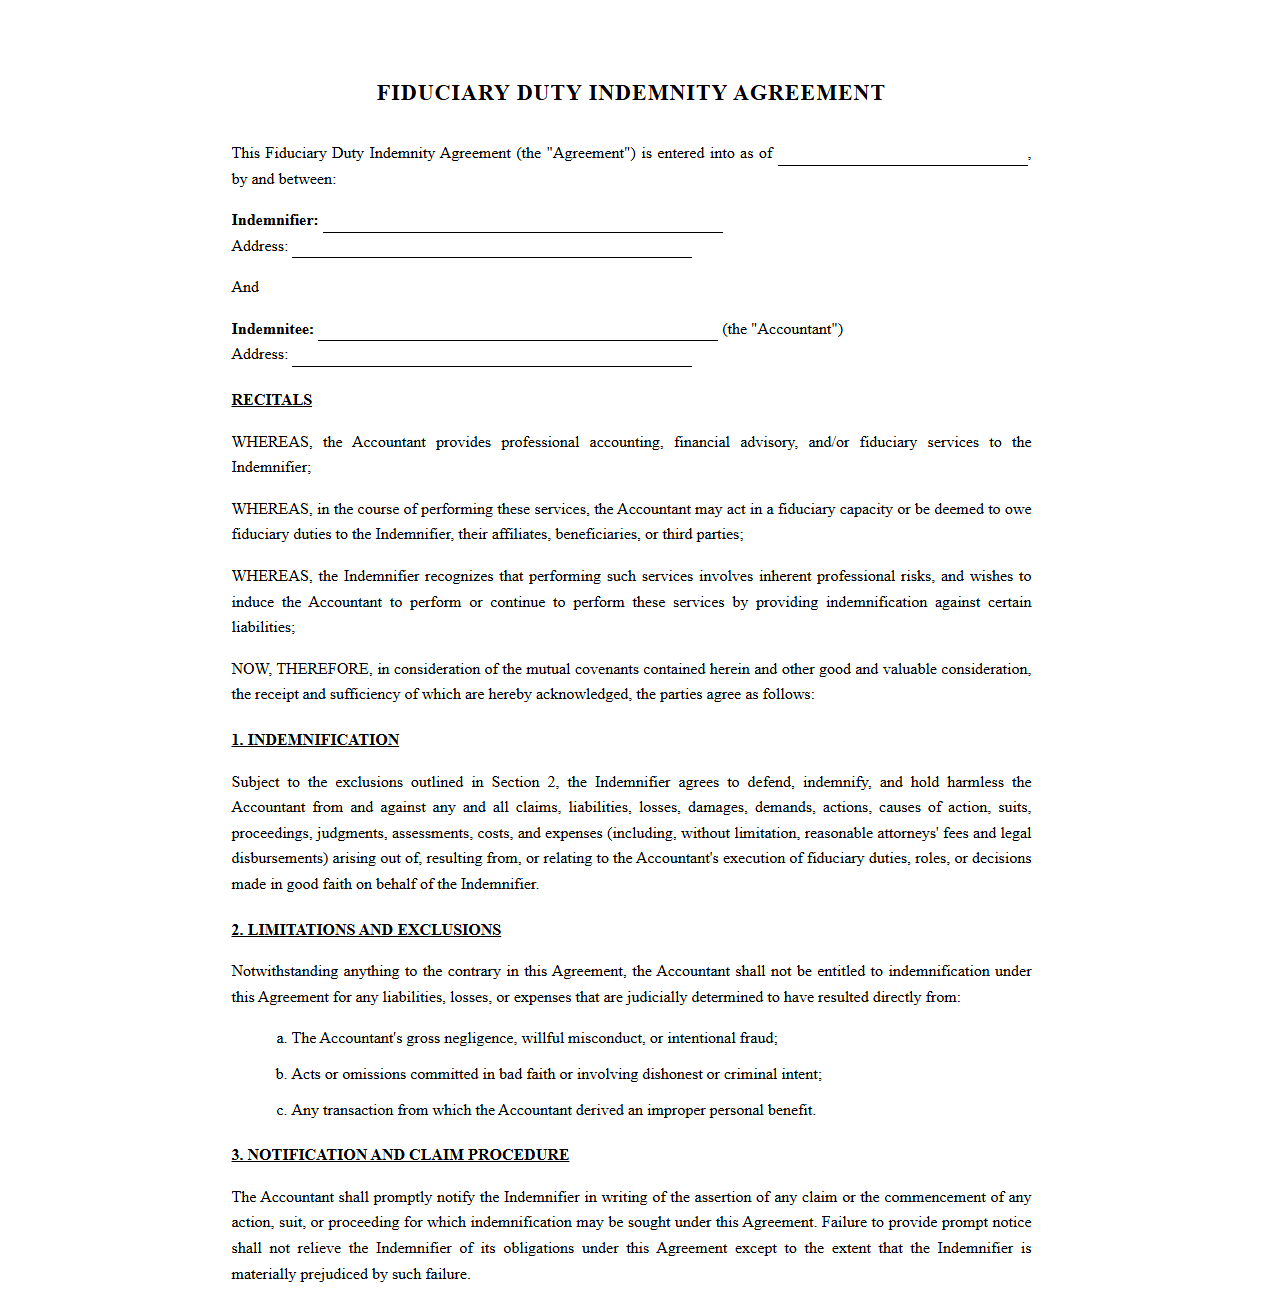 Download: .PDF
Fiduciary Indemnity Agreement for Professional Accountants
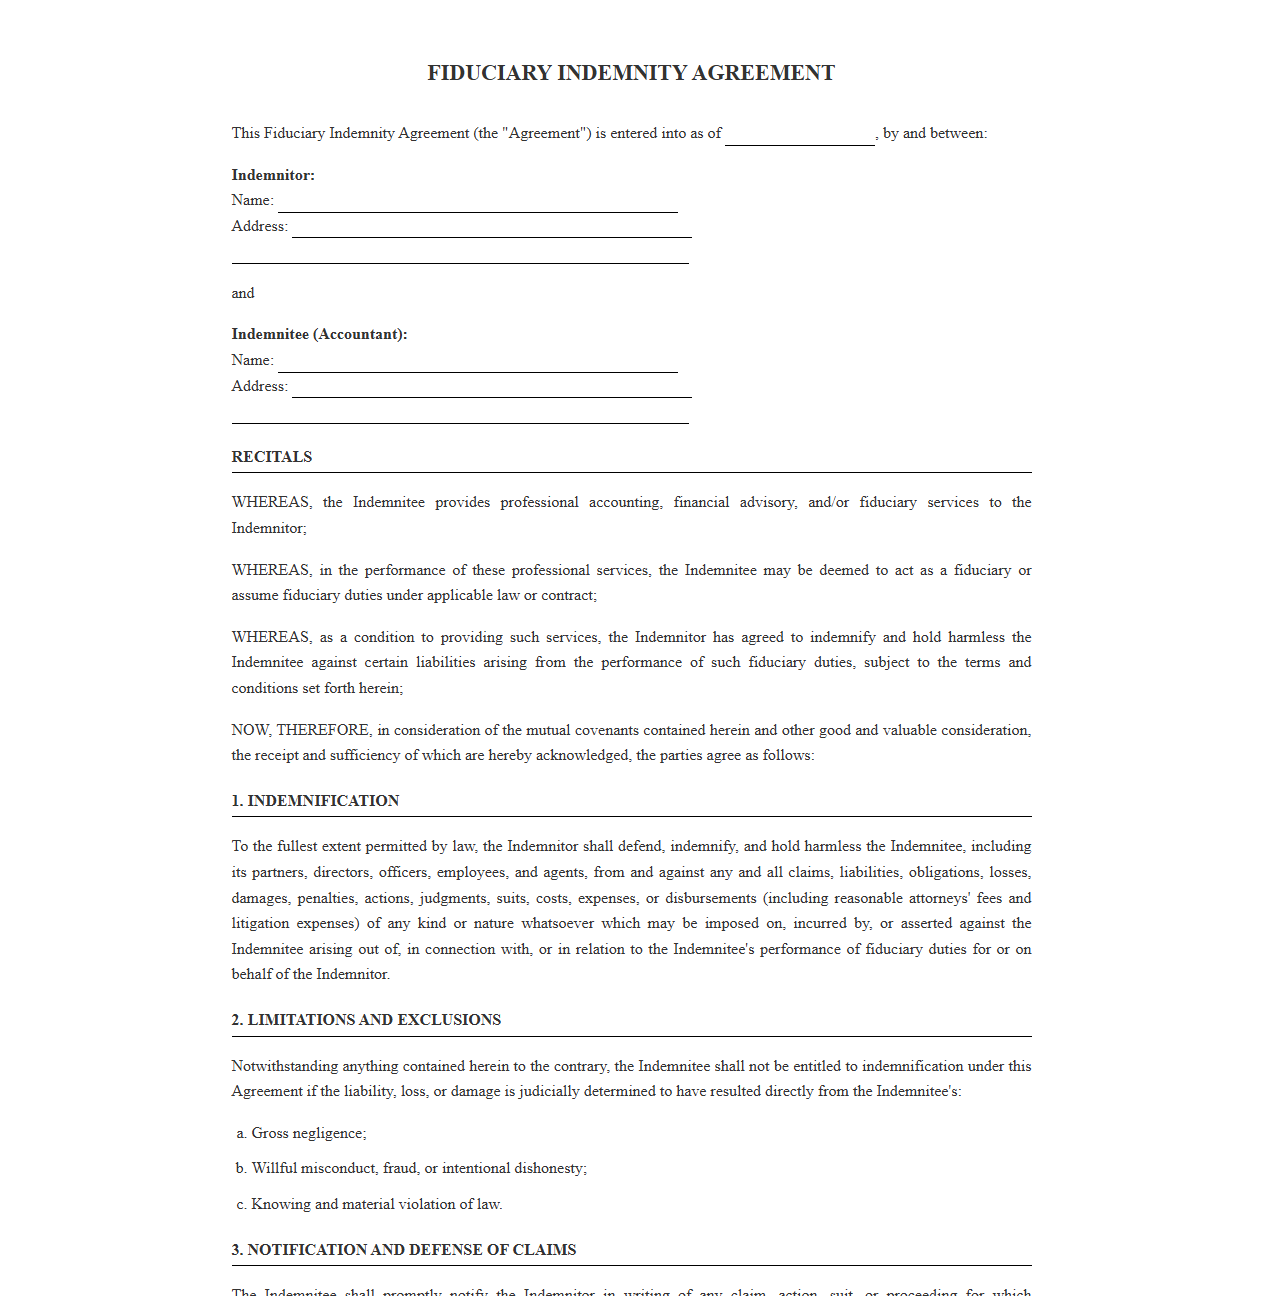 Download: .PDF
Accountants Fiduciary Liability Indemnity Agreement
 Download: .PDF
Fiduciary Duty Indemnification Contract for Accountants
 Download: .PDF
Accountant Fiduciary Liability Indemnity Release Form
 Download: .PDF
Standard Fiduciary Duty Indemnity for Accountants
 Download: .PDF
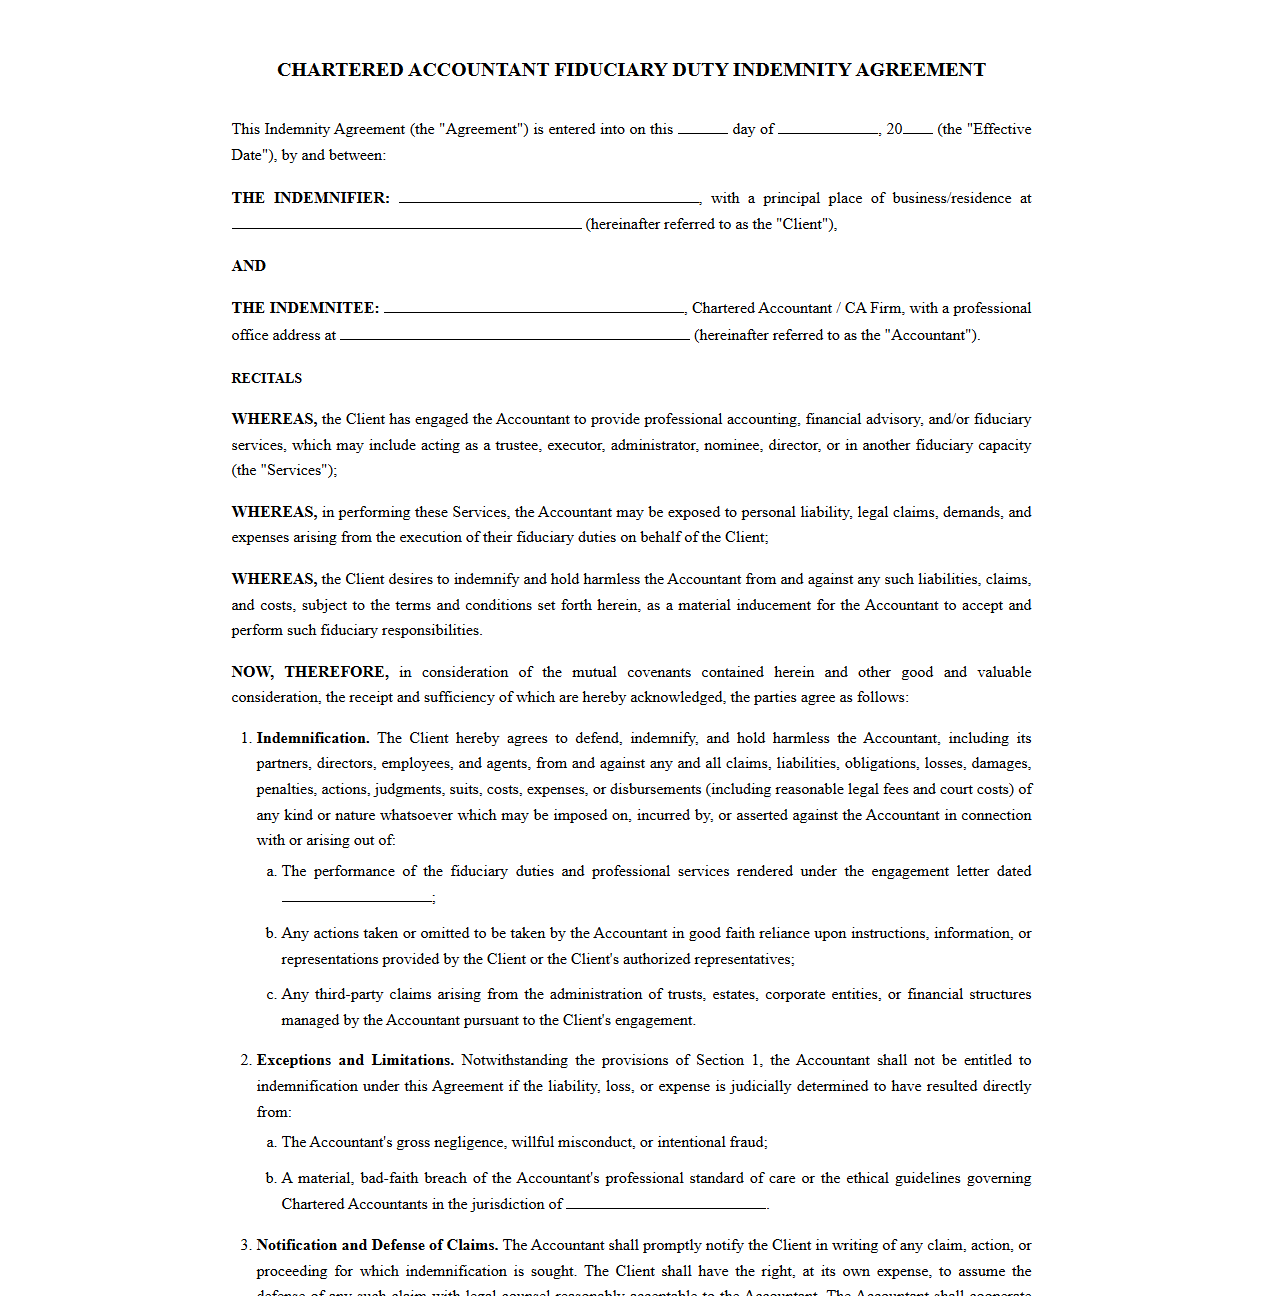
Chartered Accountant Fiduciary Duty Indemnity Agreement
 Download: .PDF
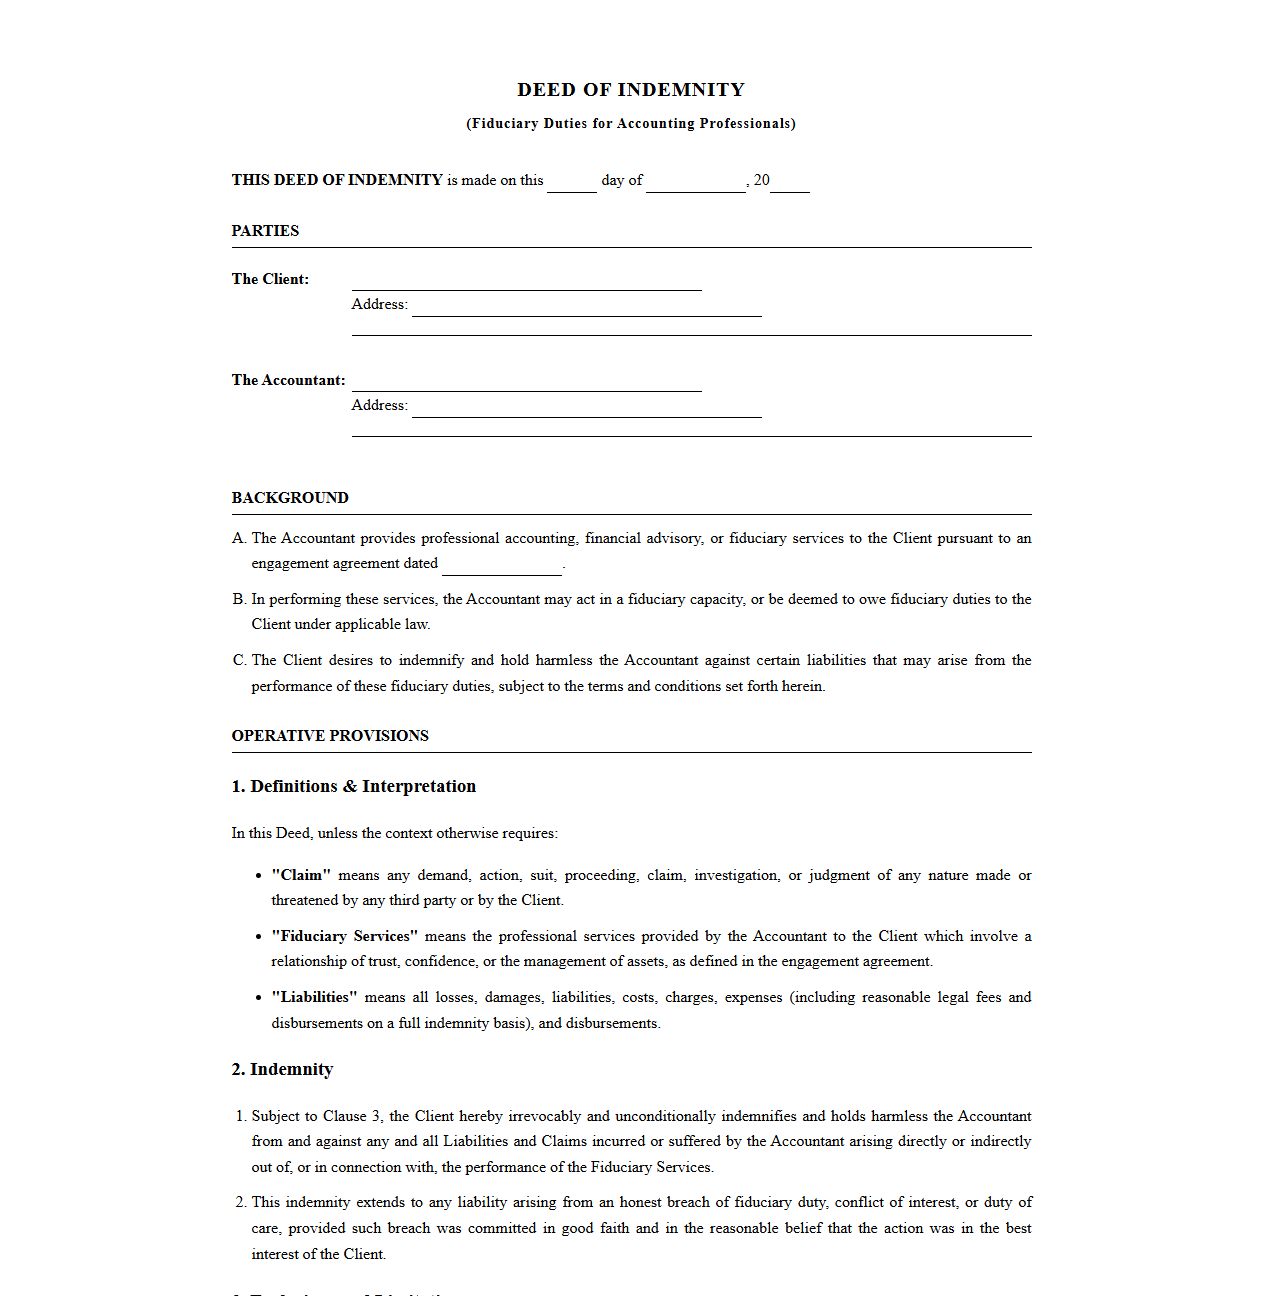
Fiduciary Duty Indemnity Deed for Accounting Professionals
 Download: .PDF
The Escalating Liability Landscape for Today's Accountants
The modern accounting profession is navigating an increasingly volatile legal and regulatory environment. No longer confined to simple bookkeeping, accountants are now strategic partners, wealth advisors, and corporate strategists. With this expanded influence comes heightened exposure to legal and financial liability. A single misstep, misinterpretation of tax law, or oversight in financial reporting can result in catastrophic financial losses and devastating lawsuits for a firm.
At the center of this heightened risk is the concept of fiduciary duty, a strict legal obligation that requires professionals to act solely in the best interests of their clients. When clients suffer financial downturns, they often look to point fingers, and the accountant is frequently the primary target. To survive in this high-stakes environment, firms must deploy proactive defense mechanisms. Fiduciary duty indemnity agreements serve as a crucial shield, establishing clear boundaries of liability and protecting the firm's assets from ruinous litigation.
Defining Fiduciary Duty in the Accounting Profession
Fiduciary duty represents the highest standard of care imposed by both equity and law. In the context of accounting, it goes far beyond the basic contractual obligation to perform services competently. When an accountant is deemed a fiduciary, they are legally bound to act with absolute loyalty, honesty, and good faith toward their client, prioritizing the client's financial interests above their own.
An accountant is typically deemed a fiduciary under specific circumstances, including:
- Discretionary Asset Management: When an accountant has direct control or decision-making authority over a client's funds, investments, or business assets.
- In-Depth Business Advisory: When acting as a strategic consultant where the client places absolute trust and reliance on the advisor's specialized knowledge.
- Estate and Trust Administration: When serving as an executor, trustee, or formal administrator of a client's estate.
The legal implications of a fiduciary relationship are profound. If a client alleges a breach of fiduciary duty, the burden of proof often shifts, requiring the accountant to demonstrate they acted with utmost fairness. Legal remedies for breaches can include disgorgement of fees, compensatory damages, and punitive fines, making clear contractual definitions essential.
Anatomy of a Fiduciary Duty Indemnity Agreement
A Fiduciary Duty Indemnity Agreement is a legally binding contract that reallocates risk between the accountant and the client. It specifies that the client will compensate the accountant for certain losses, damages, or legal costs arising from the services provided, provided the accountant acted in good faith. Rather than leaving liability exposure open-ended, this agreement sets clear parameters around when and how the accountant is protected.
By defining these boundaries, the agreement mitigates the risk of catastrophic lawsuits that could otherwise bankrupt a practice. To illustrate the core philosophy behind these protective contracts, legal professionals often refer to this standard standard of mutual understanding:
"Indemnity is not an escape from professional responsibility, but rather a structured allocation of risk that ensures professional advisors can perform high-value services without facing disproportionate financial ruin."
For practices looking to implement these protections, utilizing well-drafted templates is a highly practical starting point. Templates ensure that the foundational legal terminology is standardized, saving time and reducing legal drafting costs. They can then be customized to reflect the specific risk profile of the engagement.
Key Clauses Every Accountant's Indemnity Template Must Include
To ensure robust protection, an indemnity template cannot rely on vague language. It must contain specific, legally enforceable clauses that define the boundaries of liability. A comprehensive template should always include the following core components:
- Scope of Indemnification: This clause specifies exactly which actions, damages, and legal expenses are covered, ensuring protection applies to claims brought by third parties as well as the client.
- Limitation of Liability: This provision caps the maximum financial exposure of the accountant, often limiting damages to the total fees paid under the
Engagement_Letter. - Hold Harmless Provisions: A clause stating the client agrees not to hold the accountant legally responsible for losses resulting from inaccurate information provided by the client.
- Governing Law and Jurisdiction: This identifies the specific state or regional laws that will govern the interpretation of the contract, such as
state_law_selection, and dictates where disputes must be resolved.
Excluding any of these foundational clauses can leave a firm vulnerable to creative legal arguments during a dispute, rendering the entire indemnity agreement ineffective.
Tailoring Templates to Specific Accounting Roles and Services
A one-size-fits-all approach to indemnity agreements is highly risky. Different accounting roles carry unique risks, requiring targeted modifications to standard templates to ensure the terms match the actual services rendered.
Tax Preparation and Compliance Services
Tax preparation templates must focus on the accuracy of client-provided data. The agreement should emphasize that the accountant is not responsible for audits or penalties resulting from hidden assets, undeclared income, or fraudulent documentation supplied by the client. Limitation of liability clauses should explicitly address interest and penalties assessed by tax authorities.
Forensic Auditing and Fraud Investigation
Forensic accountants dig into financial discrepancies, often in adversarial contexts like shareholder disputes or divorce proceedings. Templates for this niche must protect the accountant from retaliatory lawsuits filed by the investigated parties. The indemnity clause should cover all costs associated with deposition subpoenas and court appearances.
Fractional CFO and Advisory Services
When acting as a fractional CFO, an accountant embedded in a client's management team makes operational decisions. This high-risk role requires robust indemnity that mirrors corporate officer protections. The agreement must state that the advisor is indemnified for business decisions made in good faith, separating professional advisory liability from operational business failures.
Legal Best Practices for Implementing Indemnity Agreements
Having a robust indemnity agreement is only useful if it is legally enforceable and properly integrated into your onboarding process. Failing to execute the agreement correctly can result in a court throwing out the protections when you need them most.
To ensure maximum enforceability, firms should adhere to these critical administrative steps:
- Incorporate into the Engagement Letter: Never present the indemnity agreement as an afterthought. It should be seamlessly integrated into, or physically attached to, the initial engagement letter signed before any work begins.
- Ensure Bilateral Execution: Both parties must sign and date the agreement. Electronic signatures should use secure, compliant platforms that generate a verifiable audit trail.
- Avoid Unconscionable Terms: While protecting your firm is vital, clauses that attempt to indemnify an accountant for gross negligence, willful misconduct, or intentional fraud are generally unenforceable and can invalidate the entire contract.
- Regularly Update the Templates: State laws regarding indemnity and liability caps change frequently. Review your templates annually with qualified legal counsel to ensure compliance with local jurisprudence.
Prioritizing Firm Protection Through Proactive Risk Management
In the modern financial landscape, professional expertise alone is no longer enough to safeguard an accounting practice. The rise in regulatory scrutiny and client litigation requires a structured, proactive approach to risk management. Utilizing robust fiduciary duty indemnity agreement templates is not a defensive sign of distrust, but rather a standard, professional business practice that establishes transparent boundaries.
By clearly defining the limits of liability and securing client agreement before engagement, firms protect both their hard-earned assets and the longevity of their client relationships. Implementing these agreements ensures that your practice can continue to deliver high-value strategic guidance with the confidence that the firm's financial foundation remains secure.
Leave a comment