For businesses utilizing independent talent, the looming threat of worker misclassification audits and unexpected tax liabilities remains a persistent source of financial anxiety. As regulatory bodies tighten their oversight of the modern workforce, establishing clear operational boundaries is no longer optional-it is a critical necessity. Fortunately, deploying a structured Subcontractor Self-Employment Acknowledgement Agreement grants organizations a powerful shield against joint-employment liabilities and costly IRS reclassifications.
However, simply signing a basic waiver is insufficient; these documents must stipulate precise terms regarding tax responsibilities, equipment ownership, and non-exclusivity to hold legal weight. Utilizing concrete frameworks-such as explicit hold-harmless clauses and references to IRS Form SS-8 criteria-serves as demonstrable proof of an independent relationship. This article examines the industry-standard agreement formats, essential clauses to include, and best practices to ensure your compliance strategy remains bulletproof.
Subcontractor Self Employment Tax Acknowledgement Agreement
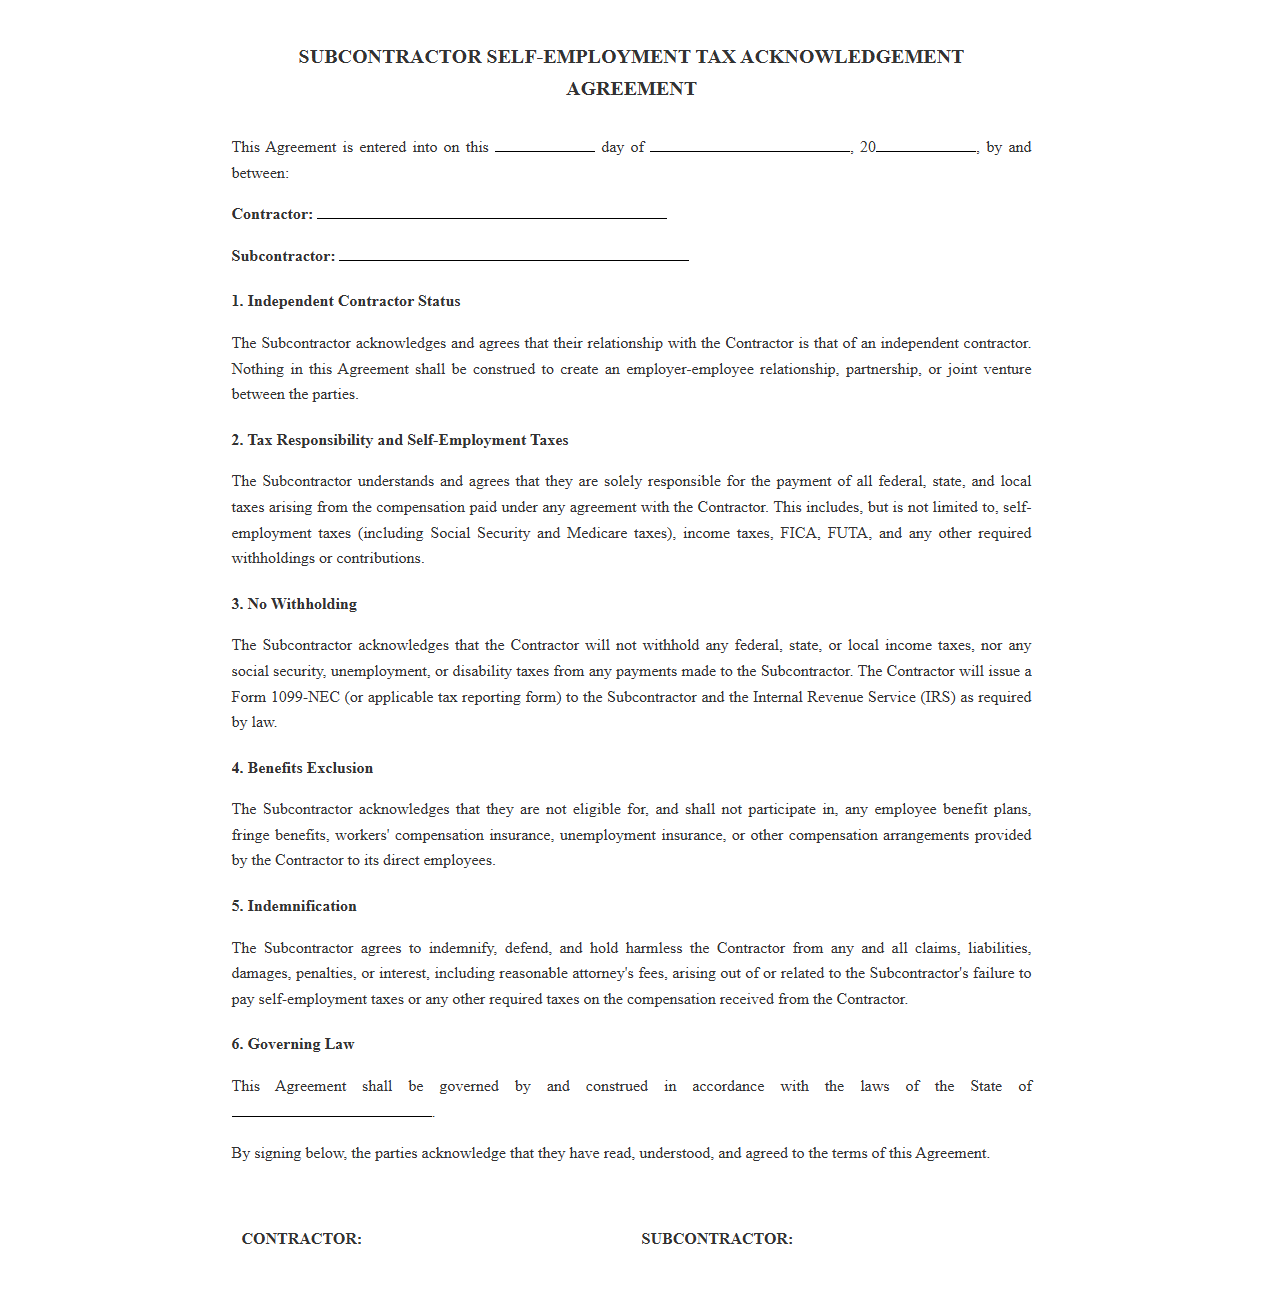 Download: .PDF
Independent Contractor Tax Responsibility Agreement
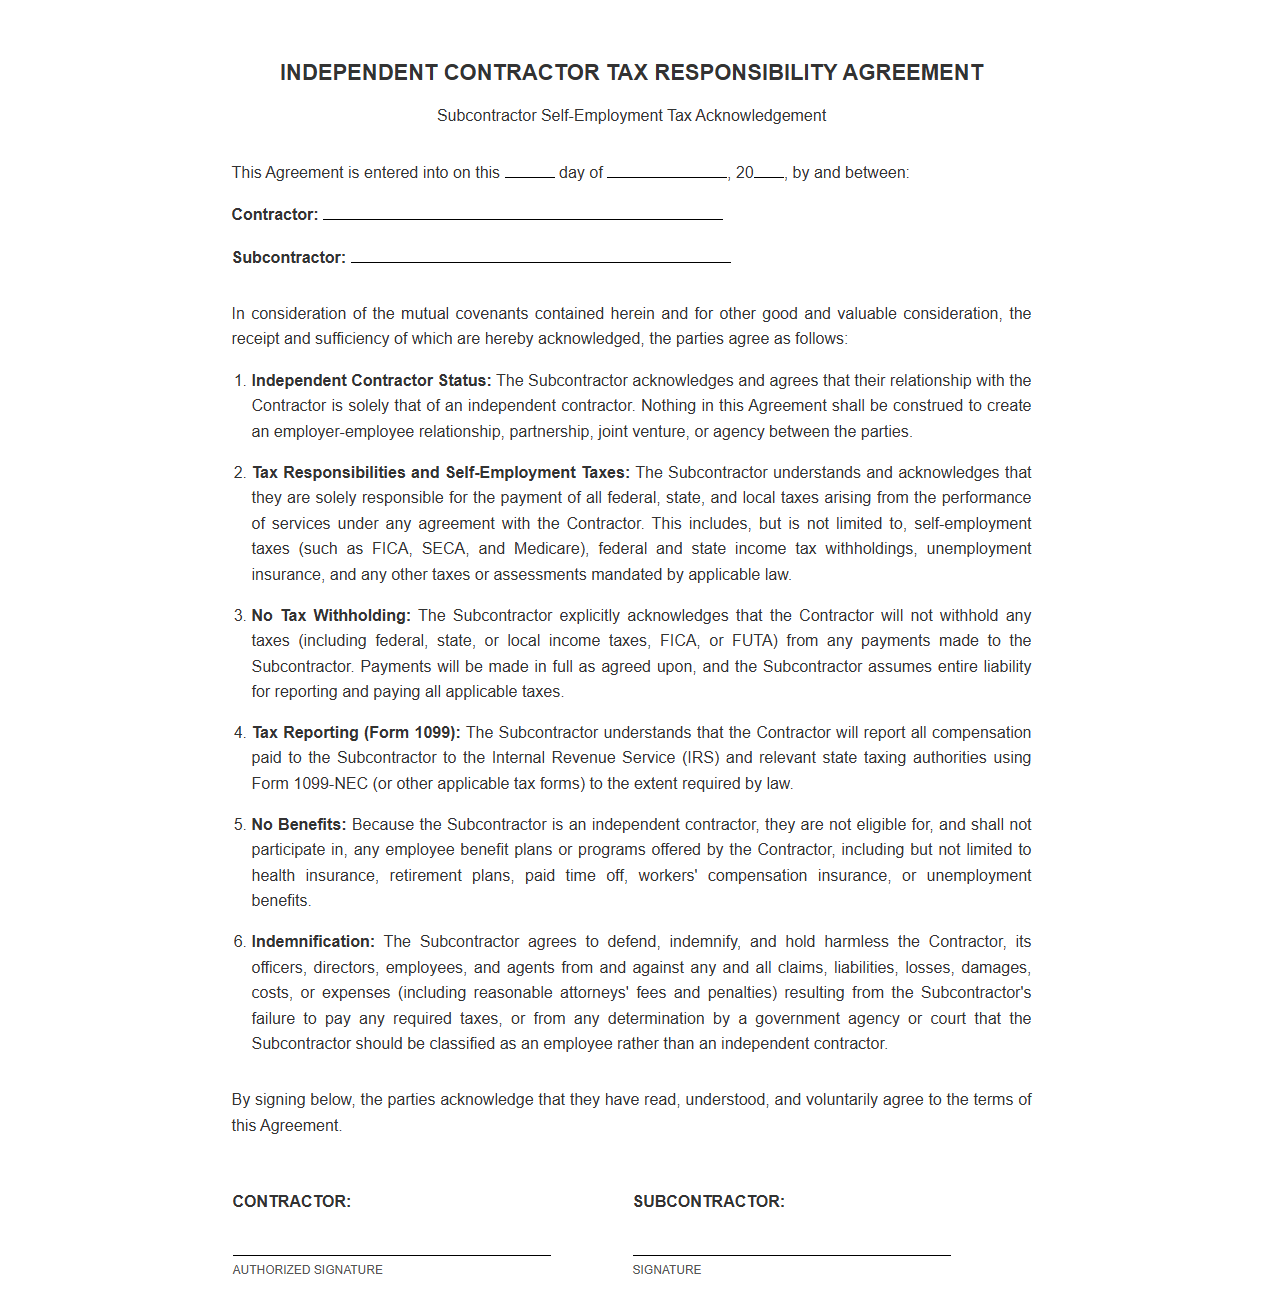 Download: .PDF
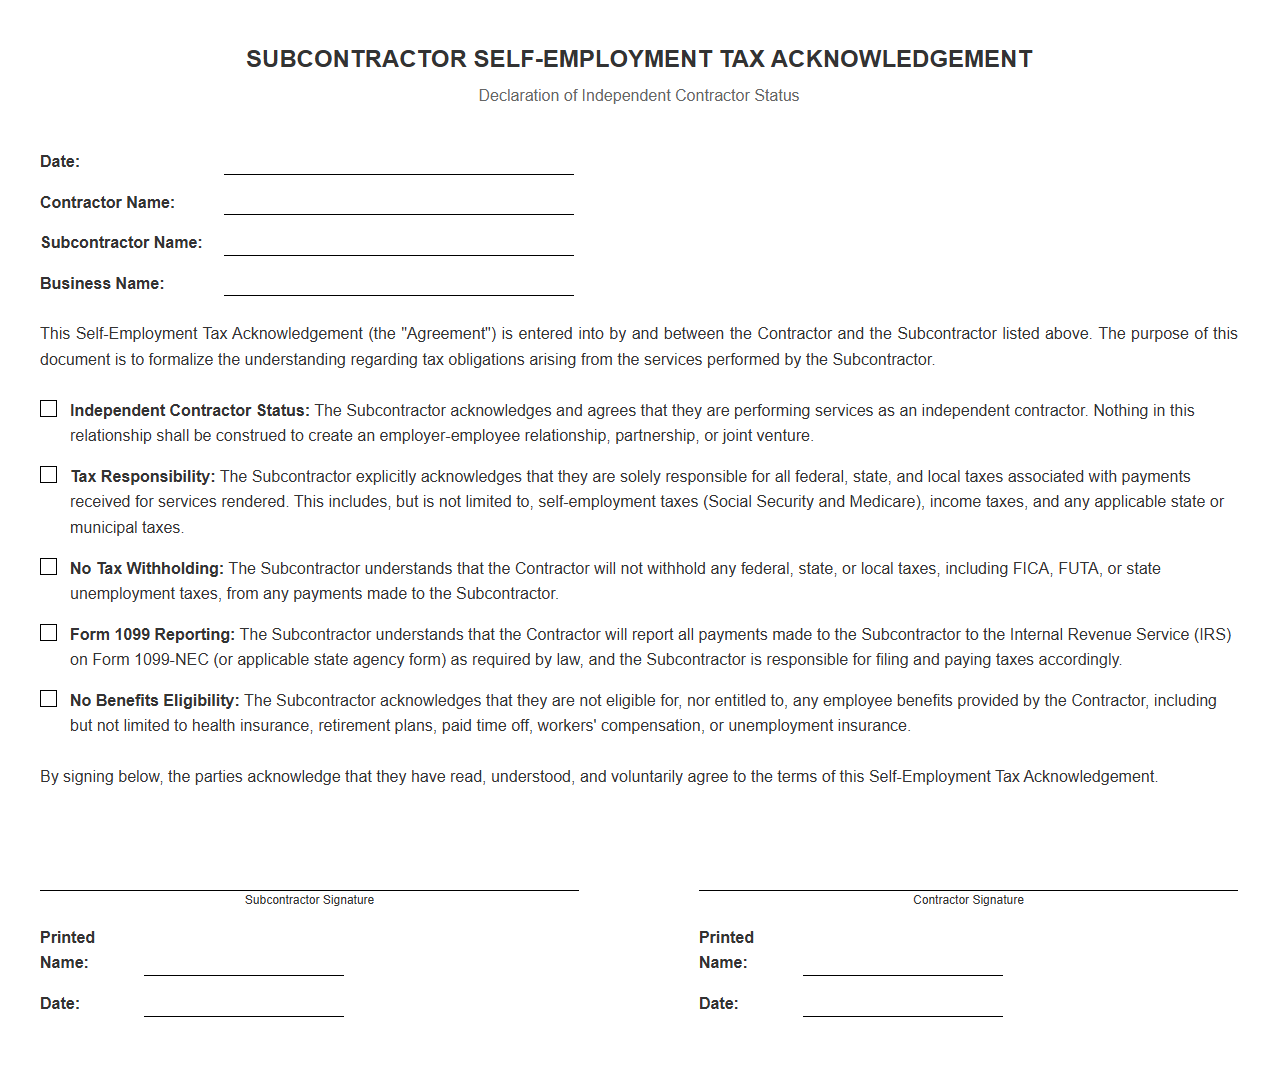
Subcontractor Self Employment Tax Declaration Form
 Download: .PDF
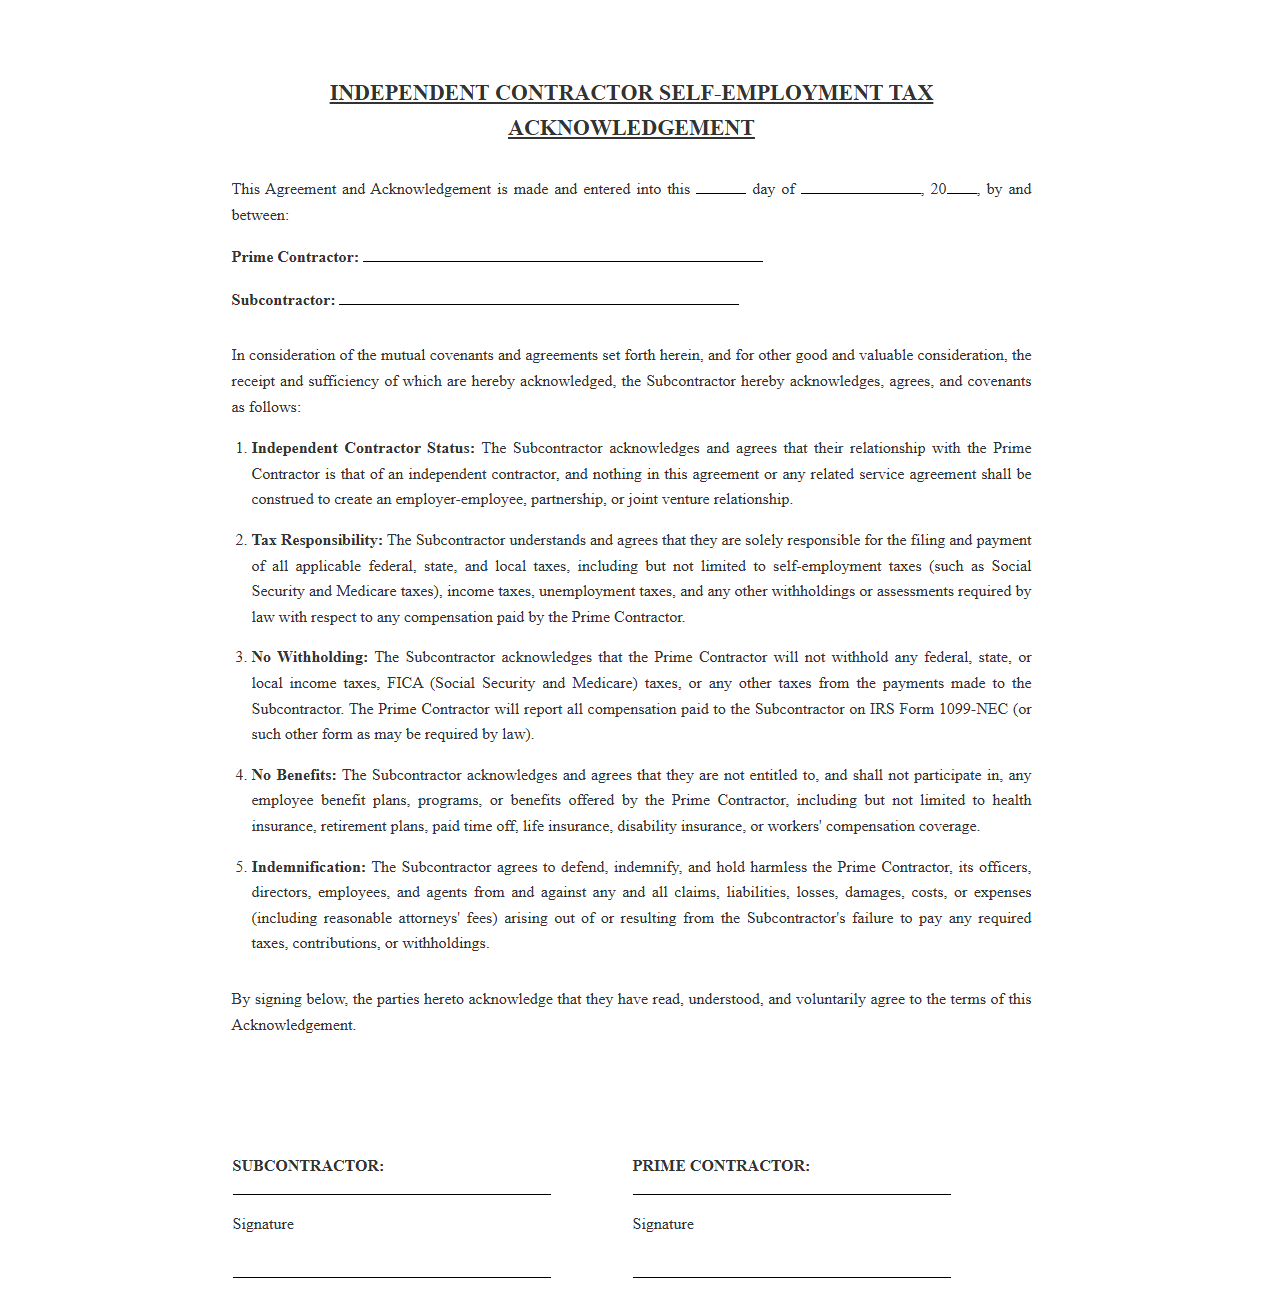
Independent Contractor Self Employment Tax Acknowledgement
 Download: .PDF
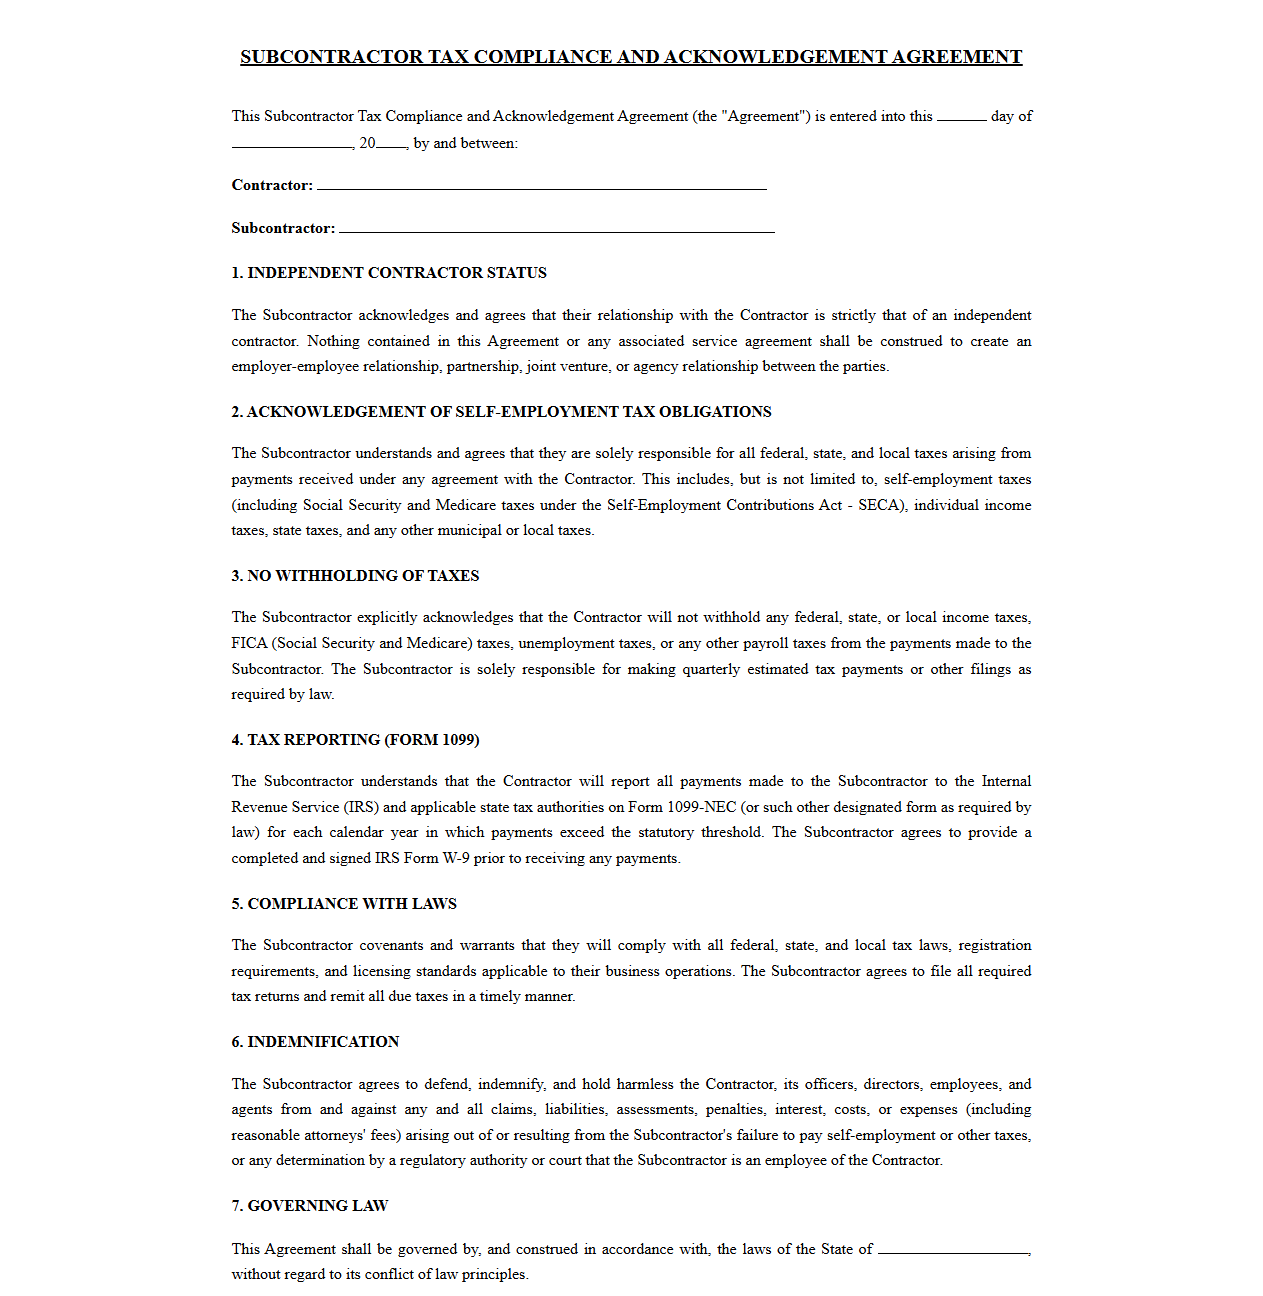
Subcontractor Tax Compliance and Acknowledgement Agreement
 Download: .PDF
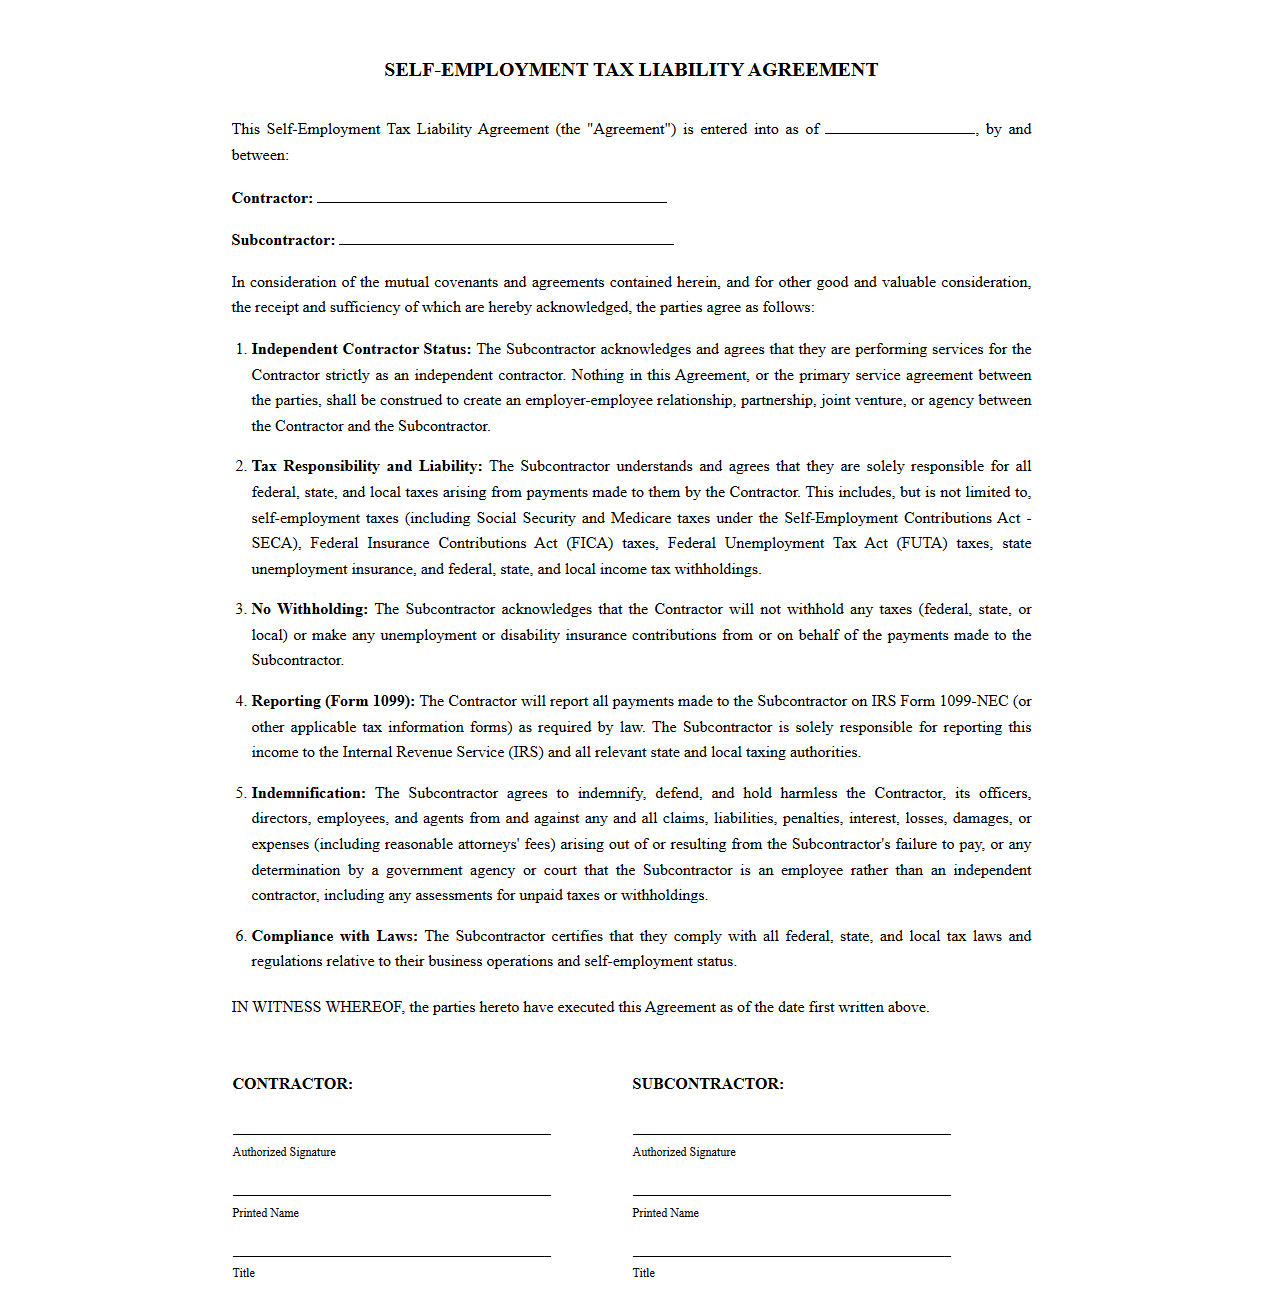
Self Employment Tax Liability Agreement for Subcontractors
 Download: .PDF
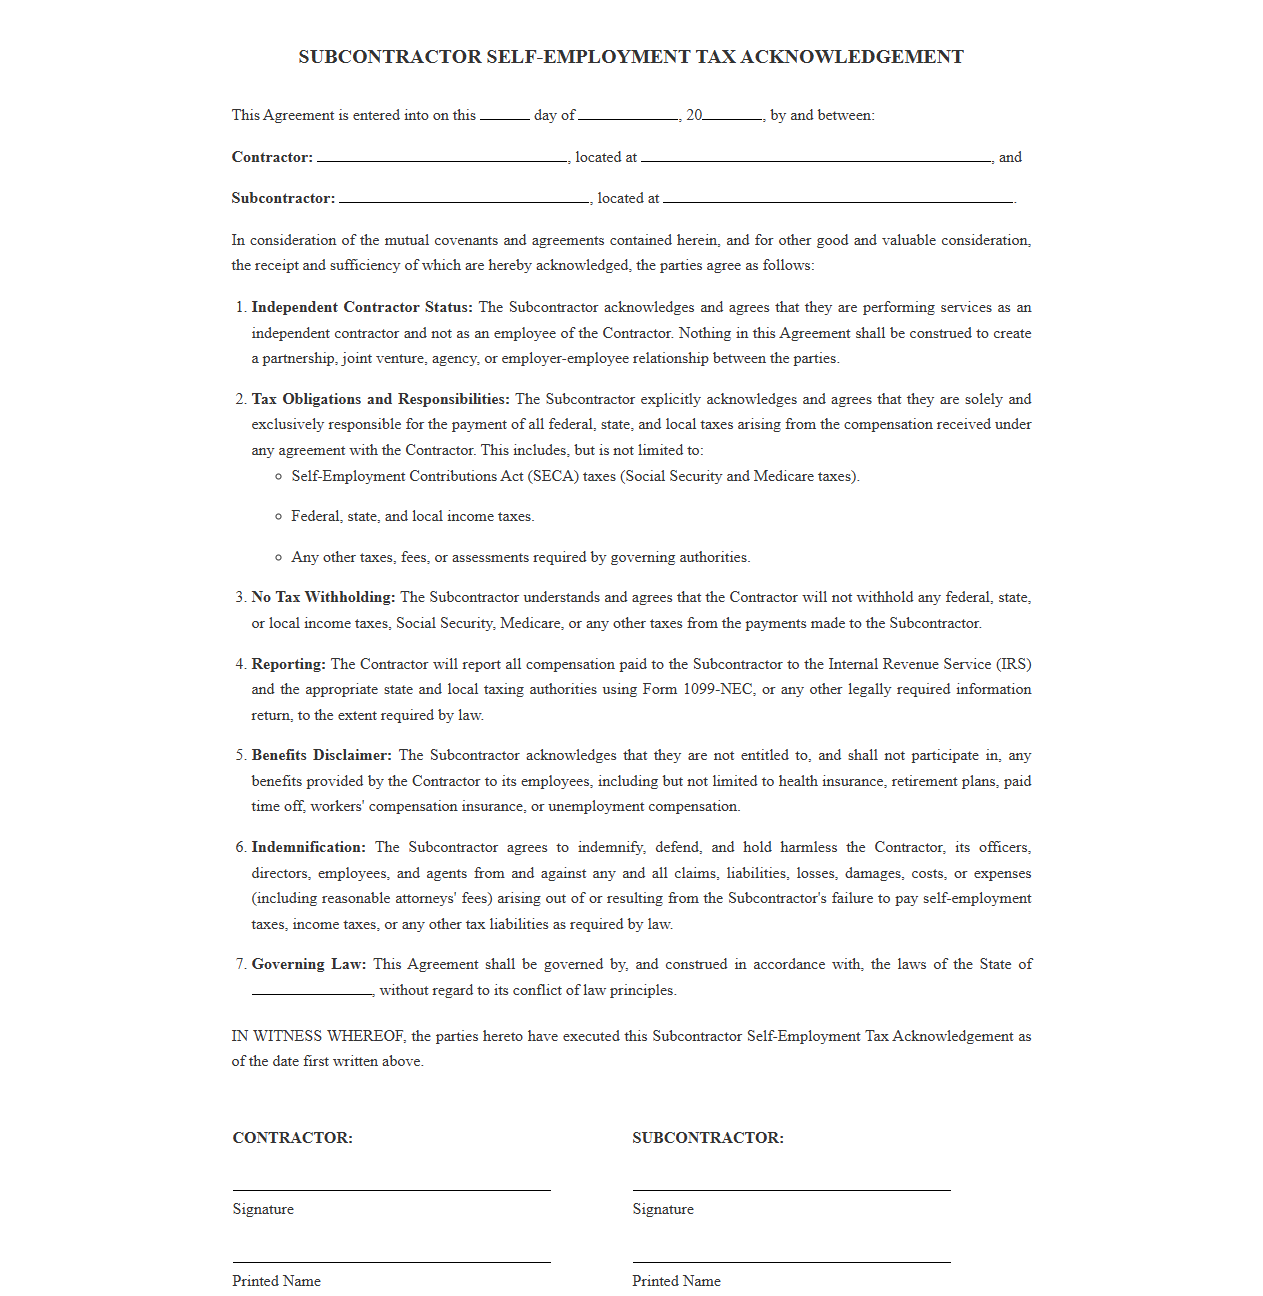
Subcontractor Agreement on Self Employment Tax Obligations
 Download: .PDF
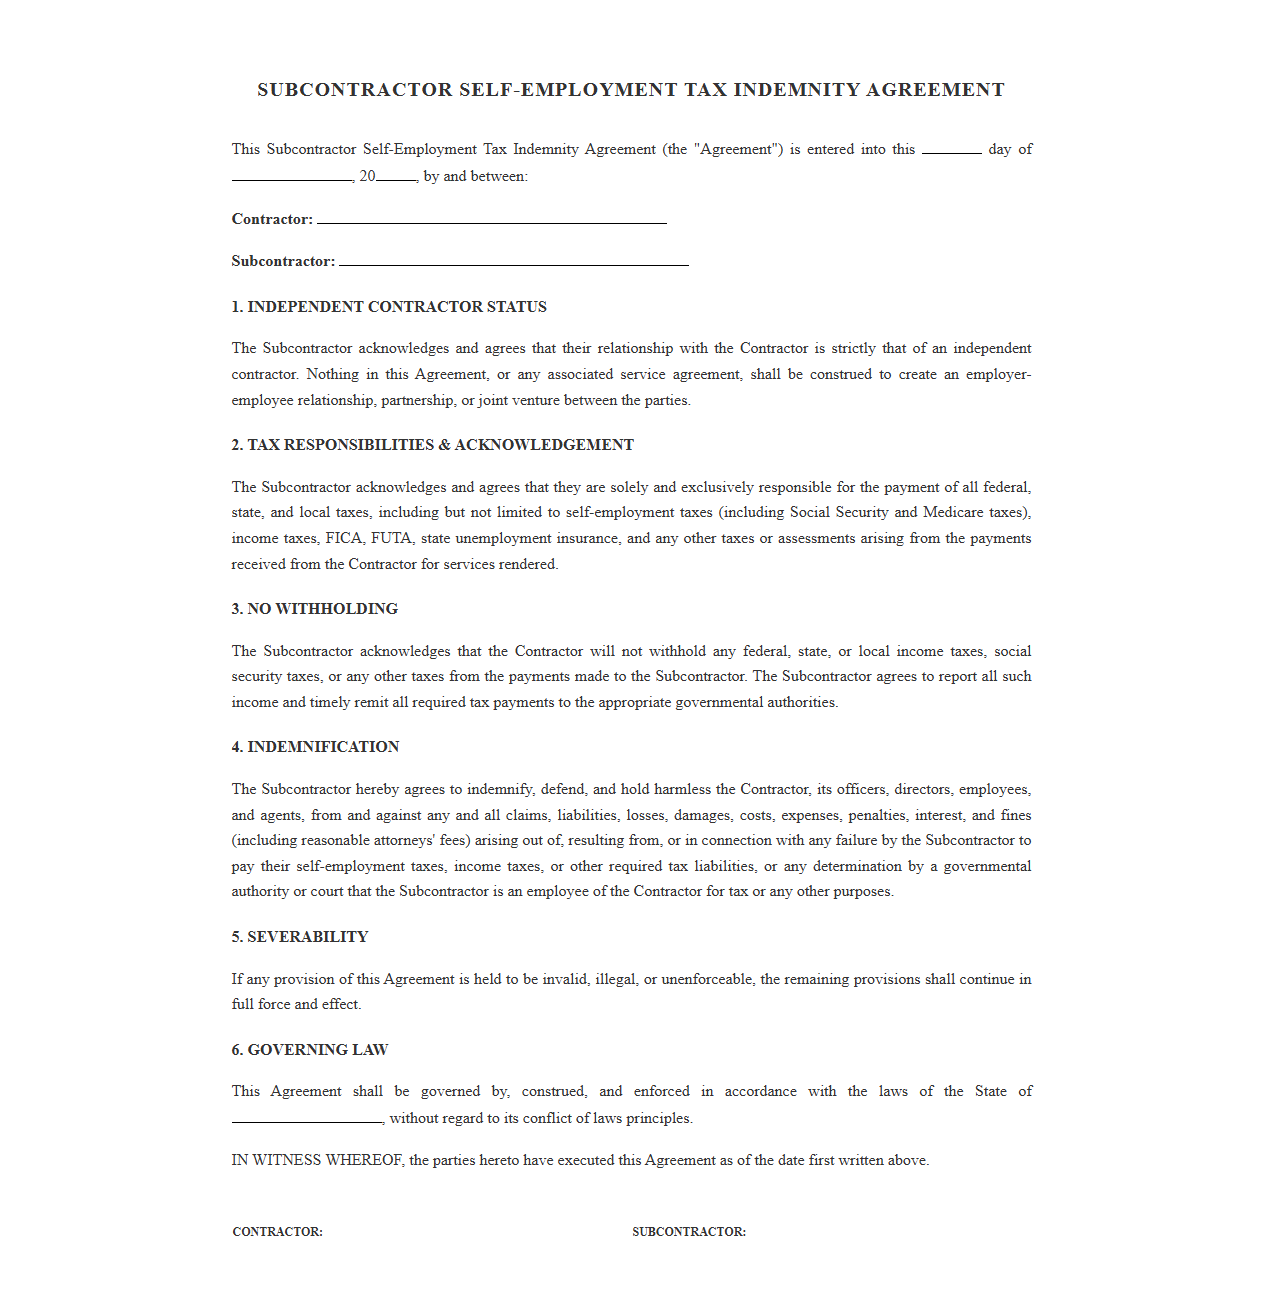
Subcontractor Self Employment Tax Indemnity Agreement
 Download: .PDF
Introduction to Subcontractor Tax Liability Mitigation
Engaging independent subcontractors offers businesses immense operational flexibility, but it also introduces substantial regulatory exposure. Failing to properly document these working relationships can trigger devastating IRS worker misclassification audits, resulting in crippling fines and retroactive payroll demands. To safeguard your business, implementing a robust Self-Employment Acknowledgement Agreement is critical. This document serves as primary evidence of intent, helping businesses mitigate tax liabilities and defend against costly back taxes, interest, and FICA penalties associated with classification errors.
Defining the Parties and the Scope of Independent Work
A legally sound agreement must begin by clearly defining who the contracting parties are and establishing that their relationship is strictly commercial, rather than an employer-employee dynamic. The scope of work detailed within the contract should explicitly demonstrate that the subcontractor operates an independent business entity, maintains control over their schedule, and possesses the specialized expertise required to complete the project without direct managerial oversight.
- Hiring Entity Identification: Legal business name, corporate structure (e.g., LLC, C-Corp), and primary business address.
- Subcontractor Identification: Legal name or registered business name (DBA), entity type, and employer identification number (EIN) or social security number.
- Scope of Services: A precise description of deliverables, milestone deadlines, and the specific, non-employee methods used to complete the project.
- Operational Independence: Explicit statements confirming the subcontractor provides their own tools, equipment, and workspace.
Core Self-Employment and Tax Responsibility Clauses
To withstand regulatory scrutiny, the agreement must contain explicit, unambiguous language regarding financial and tax obligations. The subcontractor must formally acknowledge their status as an independent entity responsible for their own operating costs and government contributions.
Self-Employment Tax Acknowledgment
The subcontractor agrees that they are operating as a self-employed individual or independent business entity. Consequently, they acknowledge sole responsibility for paying all applicable self-employment taxes, including federal, state, and local income levies.
Exclusion from Benefits and Insurance
The subcontractor explicitly waives any entitlement to company-sponsored benefits. They are solely responsible for securing their own worker's compensation insurance, general liability coverage, health benefits, and retirement plans, confirming that the hiring business carries no obligation to provide these protections.
Indemnification and Tax Liability Allocation
An indemnification clause is a vital protective barrier for the hiring entity. This clause formally shifts the financial burden of any future classification disputes to the subcontractor, ensuring that if a tax authority challenges the independent status, the subcontractor will bear the resulting financial consequences.
The agreement must state that the subcontractor agrees to hold the hiring business harmless, indemnifying it against any claims, losses, or damages. This includes paying for back taxes, interest, or administrative penalties that might arise from an audit of the subcontractor's tax filing status.
Standard Formats and Agreement Structures
When implementing these protections, businesses generally choose between two primary structural formats, depending on the complexity and volume of their contracting needs.
Standalone Form vs. MSA Addendum
A standalone Self-Employment Acknowledgement Form is highly effective for quick, one-off projects with individual freelancers. Conversely, integrating the acknowledgement as a standard addendum within a Master Service Agreement (MSA) is ideal for ongoing, long-term business partnerships.
- Standalone Form Pros: Easy to distribute, quick to execute, and highly focused solely on tax and status declarations.
- MSA Addendum Pros: Creates a unified legal framework, ensures tax clauses align with broader confidentiality and IP agreements, and simplifies contract management for recurring vendors.
Execution, Signatures, and Document Retention Best Practices
Simply drafting a strong agreement is insufficient; proper execution and record-keeping are vital to ensuring the document holds up under regulatory scrutiny. The agreement must be fully executed by authorized representatives of both parties prior to the commencement of any billable work.
In addition to dual signatures, the hiring entity should always secure a completed Form W-9 before issuing any payments. Establishing secure, encrypted digital retention policies to archive these signed agreements and tax forms for at least four years is a fundamental defense strategy, ensuring quick access to proof of compliance during a routine audit.
Legal Disclaimer and the Necessity of Professional Review
While standard templates provide an excellent foundation for business operations, tax codes and worker classification laws vary significantly by state and local jurisdiction. A single clause that is compliant in one region may be deemed invalid in another, exposing your business to unexpected liabilities.
Disclaimer: The information contained in this article is for educational purposes only and does not constitute formal legal or tax advice. Businesses must regularly consult with qualified tax attorneys or Certified Public Accountants (CPAs) to review their agreements and ensure continuous compliance with changing labor laws.
Leave a comment