Accounts receivable departments frequently struggle with the administrative headache of reconciling mismatched ledger entries when a previously issued credit note must be reversed. Before addressing these billing discrepancies directly, organizations must first understand how modern ERP systems archive historical debit-credit relationships. Mapping these document flows correctly not only safeguards regulatory compliance but also grants your finance team total audit-readiness and faster dispute resolution.
However, implementing these structures successfully requires a baseline understanding that your accounting system supports multi-layered nested schemas. For example, reversing a transaction like Credit Memo CR-9021-REV demands specific parent-document reference tags to prevent duplicate ledger entries and false revenue inflation.
This article will examine the precise schema modifications, database mapping protocols, and industry-standard document layouts required to resolve reversed credit notes and maintain flawless financial reporting.
Reversed Credit Note Invoice Template
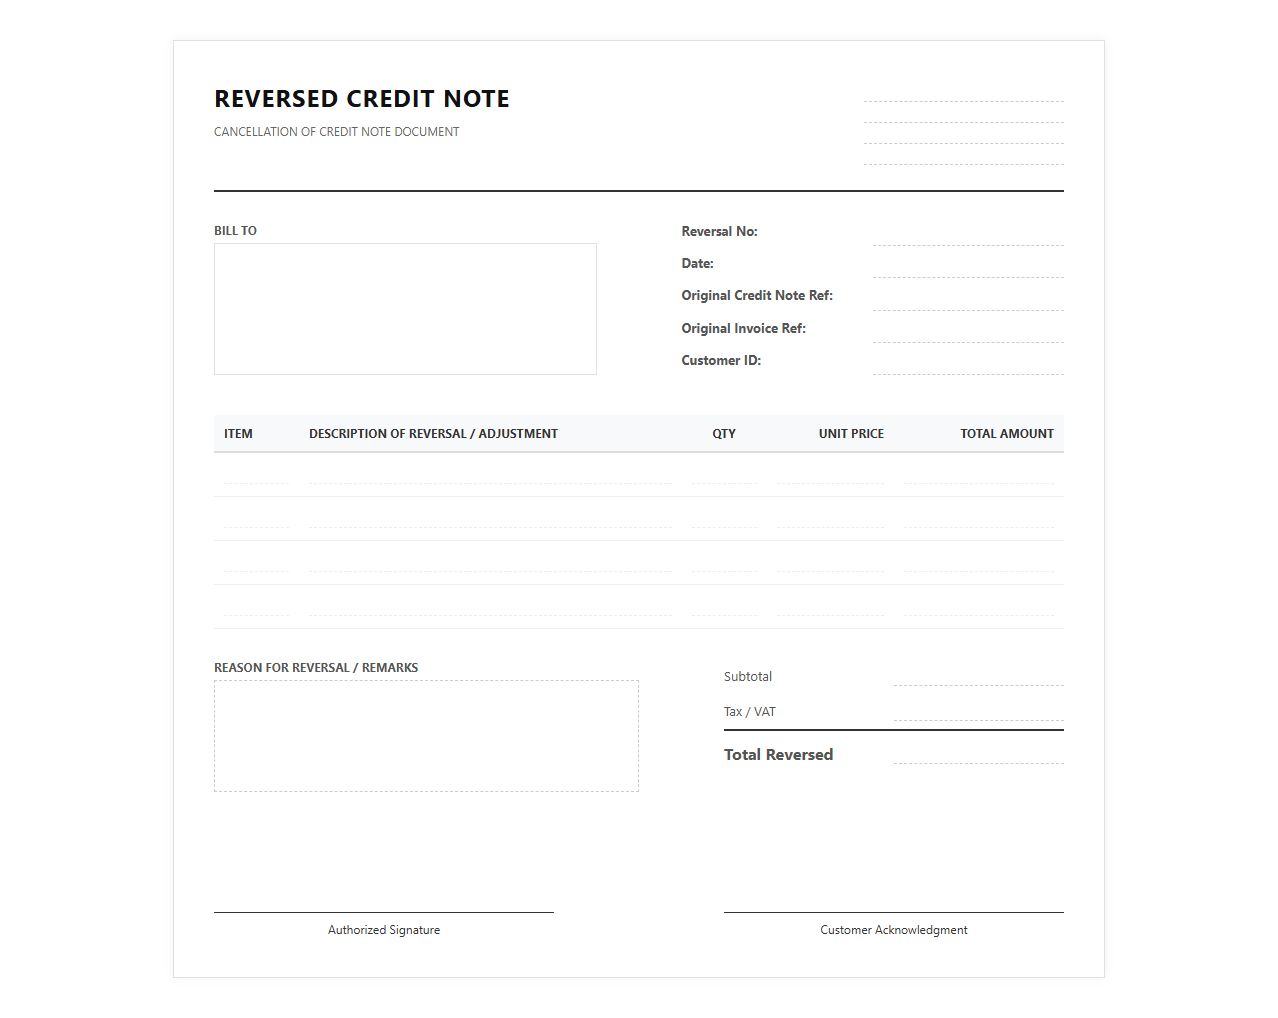 Download: .PDF
Credit Note Reversal Invoice Template
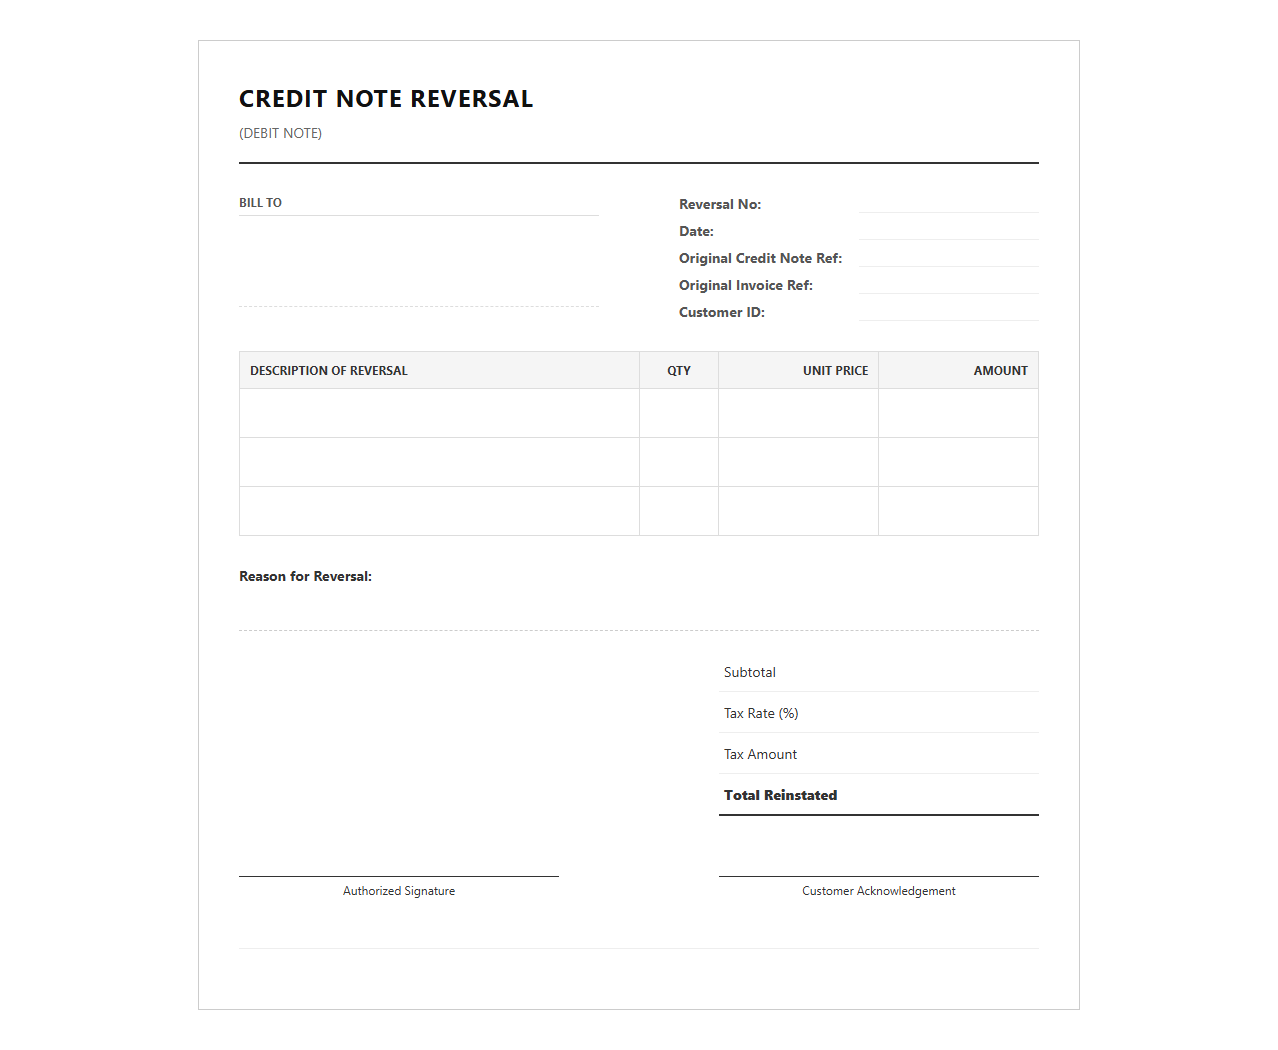 Download: .PDF
Invoice Template for Cancelled Credit Note
 Download: .PDF
Credit Note Cancellation Invoice Template
 Download: .PDF
Invoice for Reversed Credit Memo
 Download: .PDF
Reversing Credit Note Invoice Template
 Download: .PDF
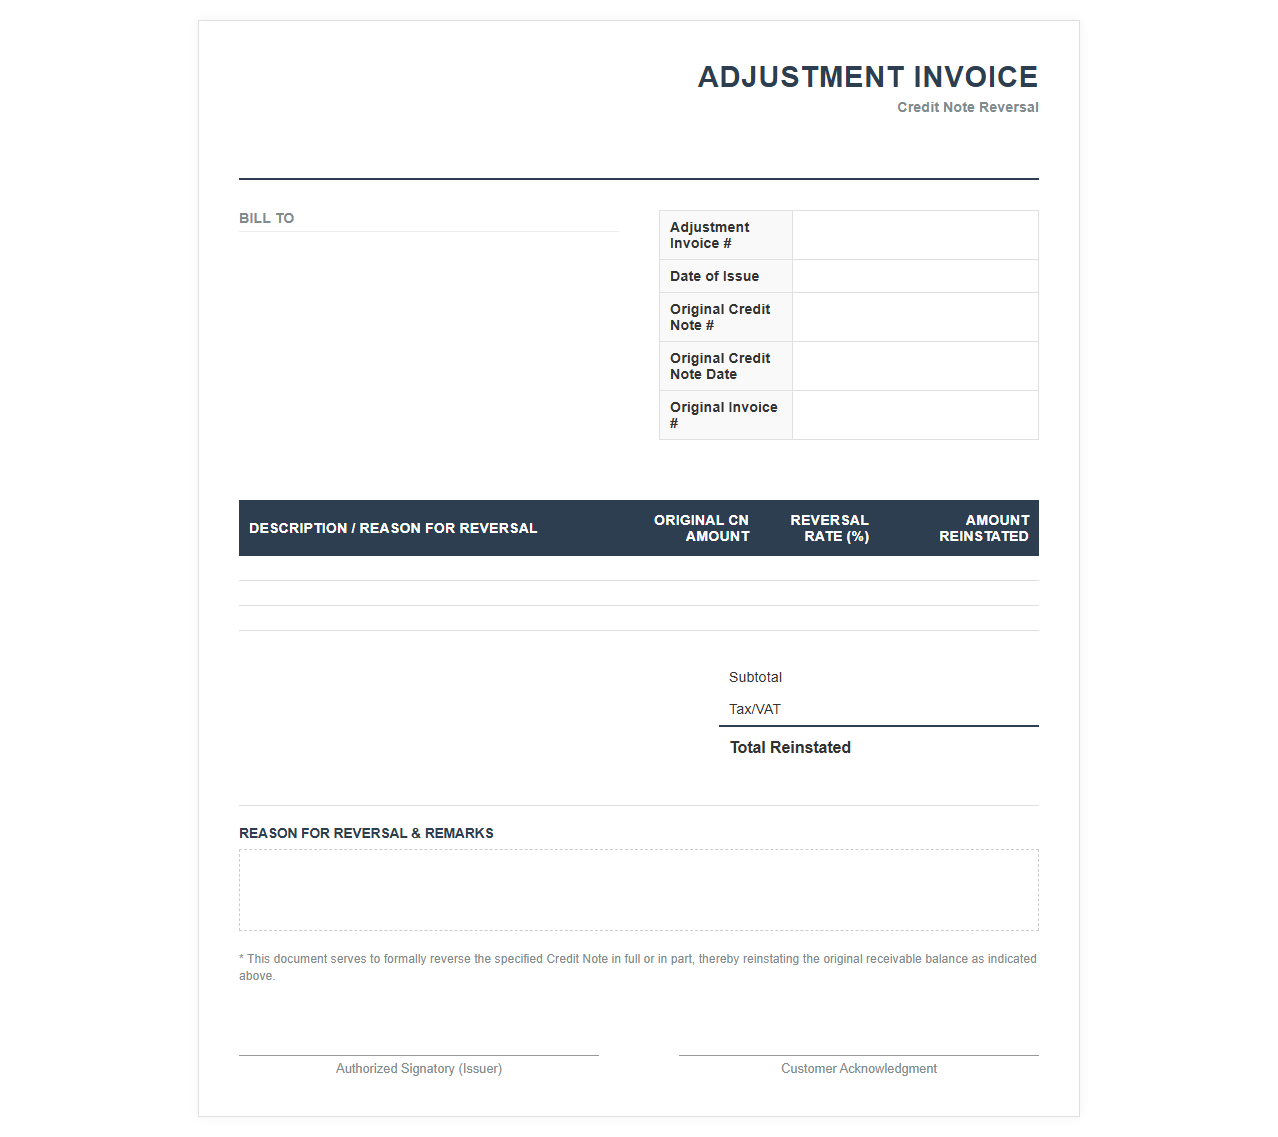
Adjustment Invoice for Credit Note Reversal
 Download: .PDF
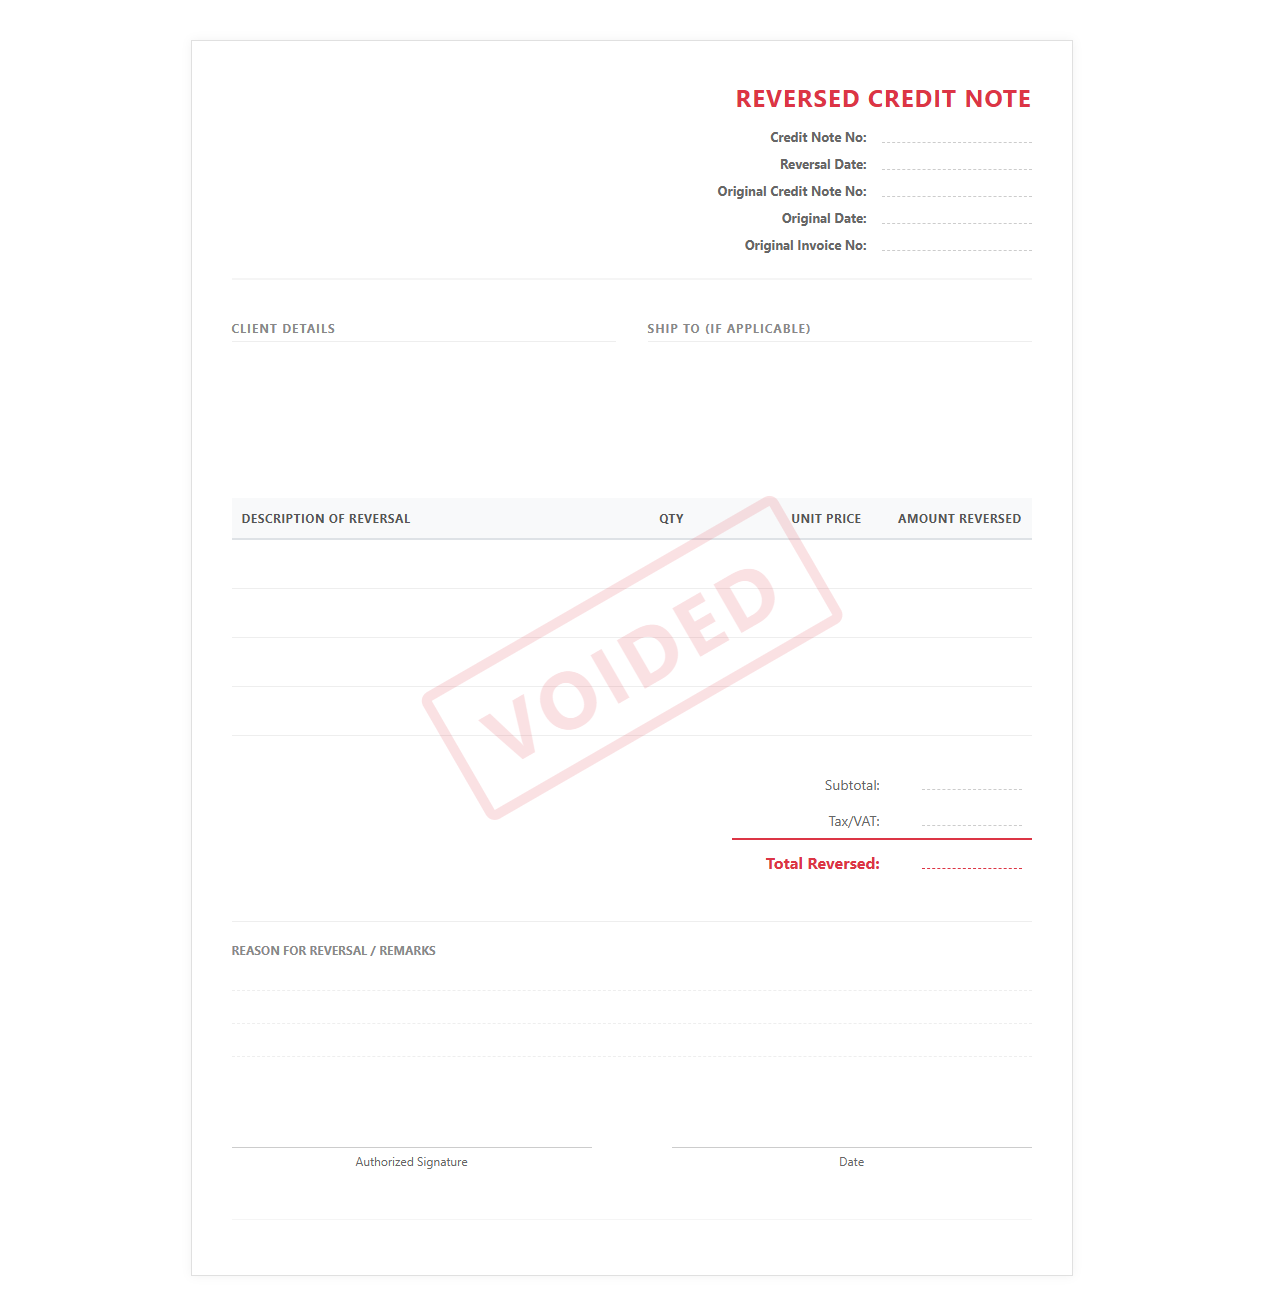
Voided Credit Note Invoice Template
 Download: .PDF
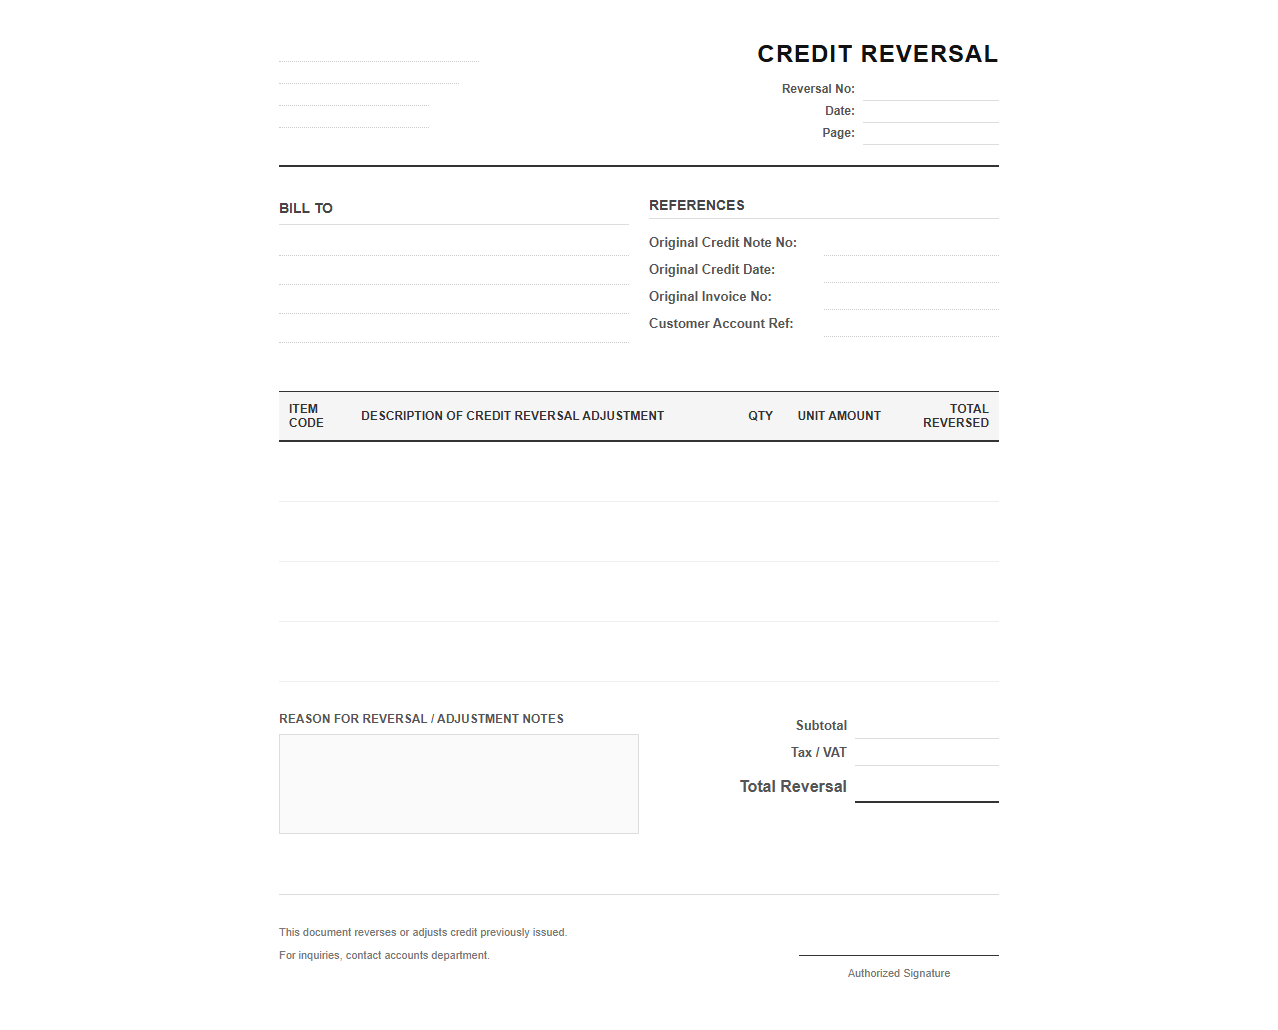
Invoice Template for Credit Reversal Adjustment
 Download: .PDF
Demystifying Reversed Credit Notes in Modern Billing
In modern financial operations, a reversed credit note serves as a critical corrective instrument. When a standard credit note is issued in error-either due to administrative mistakes, incorrect valuations, or duplicate processing-it cannot simply be deleted from the system. Doing so would violate basic accounting integrity and audit standards.
Instead, a reversed credit note is generated to systematically neutralize the erroneous credit. This document plays a pivotal role in correcting financial records, ensuring that the ledger reflects the true state of accounts receivable and liabilities without distorting the historical transactional trail. By using structured reversals, businesses maintain clear, indisputable records for internal controls and external audits.
Structural Differences Between Standard and Reversed Credit Notes
A standard credit note is structured to reduce the amount a buyer owes to a seller. It acts as a negative liability from the perspective of the seller, effectively decreasing outstanding accounts receivable. The directional flow of funds moves away from the seller's recognized revenue, reducing the customer's overall balance.
Essential Metadata and Schema Fields for Compliance
To satisfy regulatory requirements and maintain clear transactional mapping, specific metadata must be embedded within the document's schema.
original_credit_note_reference: The unique identifier of the credit note being neutralized.reversal_document_id: A distinct, auto-generated sequence number dedicated to reversal events.tax_adjustment_flag: A boolean indicator signaling to tax engines that this entry corrects a previous tax write-off.reversal_reason_code: A standardized programmatic code categorizing the operational trigger for the adjustment.
Step-by-Step System Workflow for Document Reversal
To execute a reversal without generating duplicate ledger entries or orphan records, billing engines must follow a strict, state-machine validated sequence.
- Identify the target erroneous credit note and verify its status is marked as 'posted' or 'active'.
- Verify the current balance of the underlying invoice to ensure a reversal will not cause over-billing errors.
- Generate a draft reversal document with a unique cryptographic hash linked directly to the original document.
- Validate tax rates and currency conversion factors against the original posting date's master data.
- Post the reversal to the ledger, simultaneously updating the original credit note's status to 'reversed'.
Resolving Common Schema Errors in ERP Integrations
During ERP integration processes, schema mismatches often occur when the target database expects a positive absolute value but receives a signed negative value for reversals. This mismatch can break validation loops, leading to skipped ledger postings.
{
  "document_type": "REVERSED_CREDIT_NOTE",
  "reference_id": "CN-9902-REV",
  "original_reference": "CN-9902",
  "financial_impact": {
    "reversal_amount": 1500.00,
    "currency": "USD",
    "is_absolute_value": true
  }
}
Ensuring that the database schema utilizes explicit directional fields rather than relying on mathematical sign prefixes prevents calculation anomalies across legacy and modern database engines.
Tax Alignment and Audit Trail Best Practices
Tax authorities require clear visibility into how tax liabilities are corrected. The tax summary block on a reversed credit note must explicitly map back to the tax rate in effect at the time of the original transaction.
| Tax Code | Original Tax Amount | Reversed Tax Amount | Adjustment Status |
|---|---|---|---|
| VAT-20 | -300.00 USD | +300.00 USD | Fully Reinstated |
| GST-10 | -150.00 USD | +150.00 USD | Fully Reinstated |
Future-Proofing Billing Ledgers Against Discrepancies
System errors and manual correction mistakes can be drastically minimized by implementing strict automated guardrails within billing workflows.
By establishing strict schema validation rules and automated reconciliation triggers, organizations can maintain pristine, self-correcting financial ledgers that withstand rigorous tax audits and reduce the need for manual administrative intervention.
Leave a comment