Treasury and finance departments frequently struggle with the manual, error-prone process of reconciling fragmented billing data when submitting line of credit draw requests. Before organizations can automate this funding workflow, they must first address the challenge of processing the sheer diversity of unstructured invoice formats received from global vendors.
Standardizing these inputs into structured document formats grants treasury teams immediate acceleration of capital deployment while drastically reducing operational friction. Transitioning to this model, however, stipulates a fundamental alignment between internal accounts payable systems and lender-specific compliance protocols.
By leveraging structured formats like Universal Business Language (UBL) or standardized JSON schemas, organizations can seamlessly validate concrete data points-such as verified purchase order numbers and tax identifiers-directly against credit agreement terms. This article outlines the technical frameworks required for document standardization, details integration pathways for banking APIs, and provides a roadmap for optimizing your draw request lifecycle.
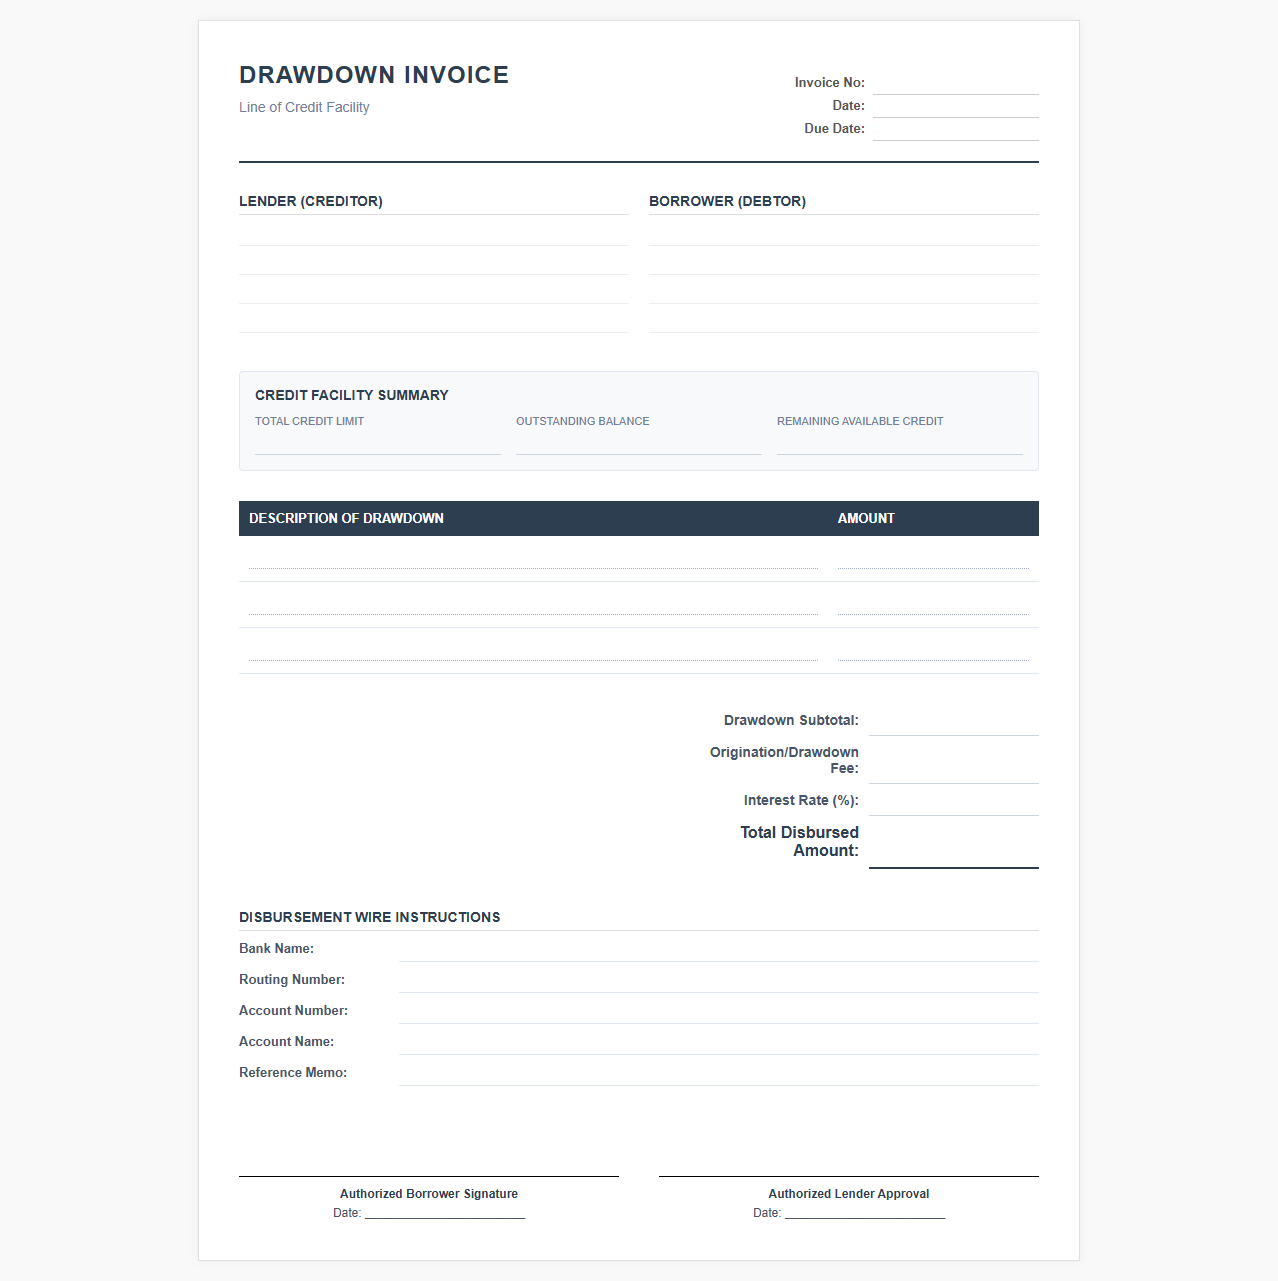
Line of Credit Drawdown Invoice Template
 Download: .PDF
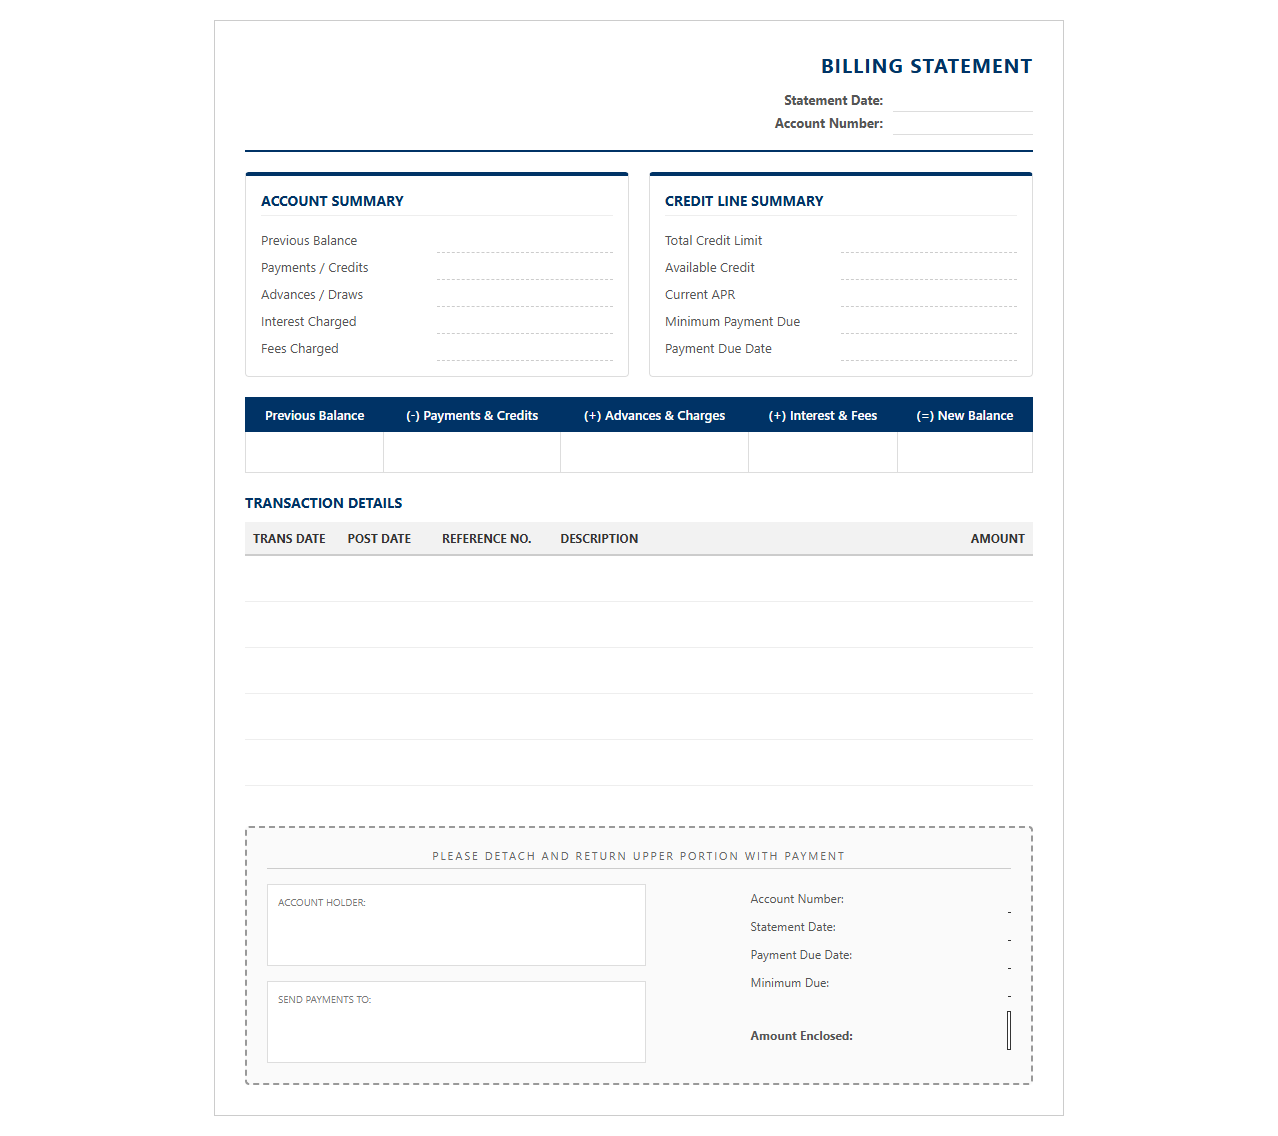
Revolving Credit Line Billing Statement
 Download: .PDF
Commercial Line of Credit Draw Request
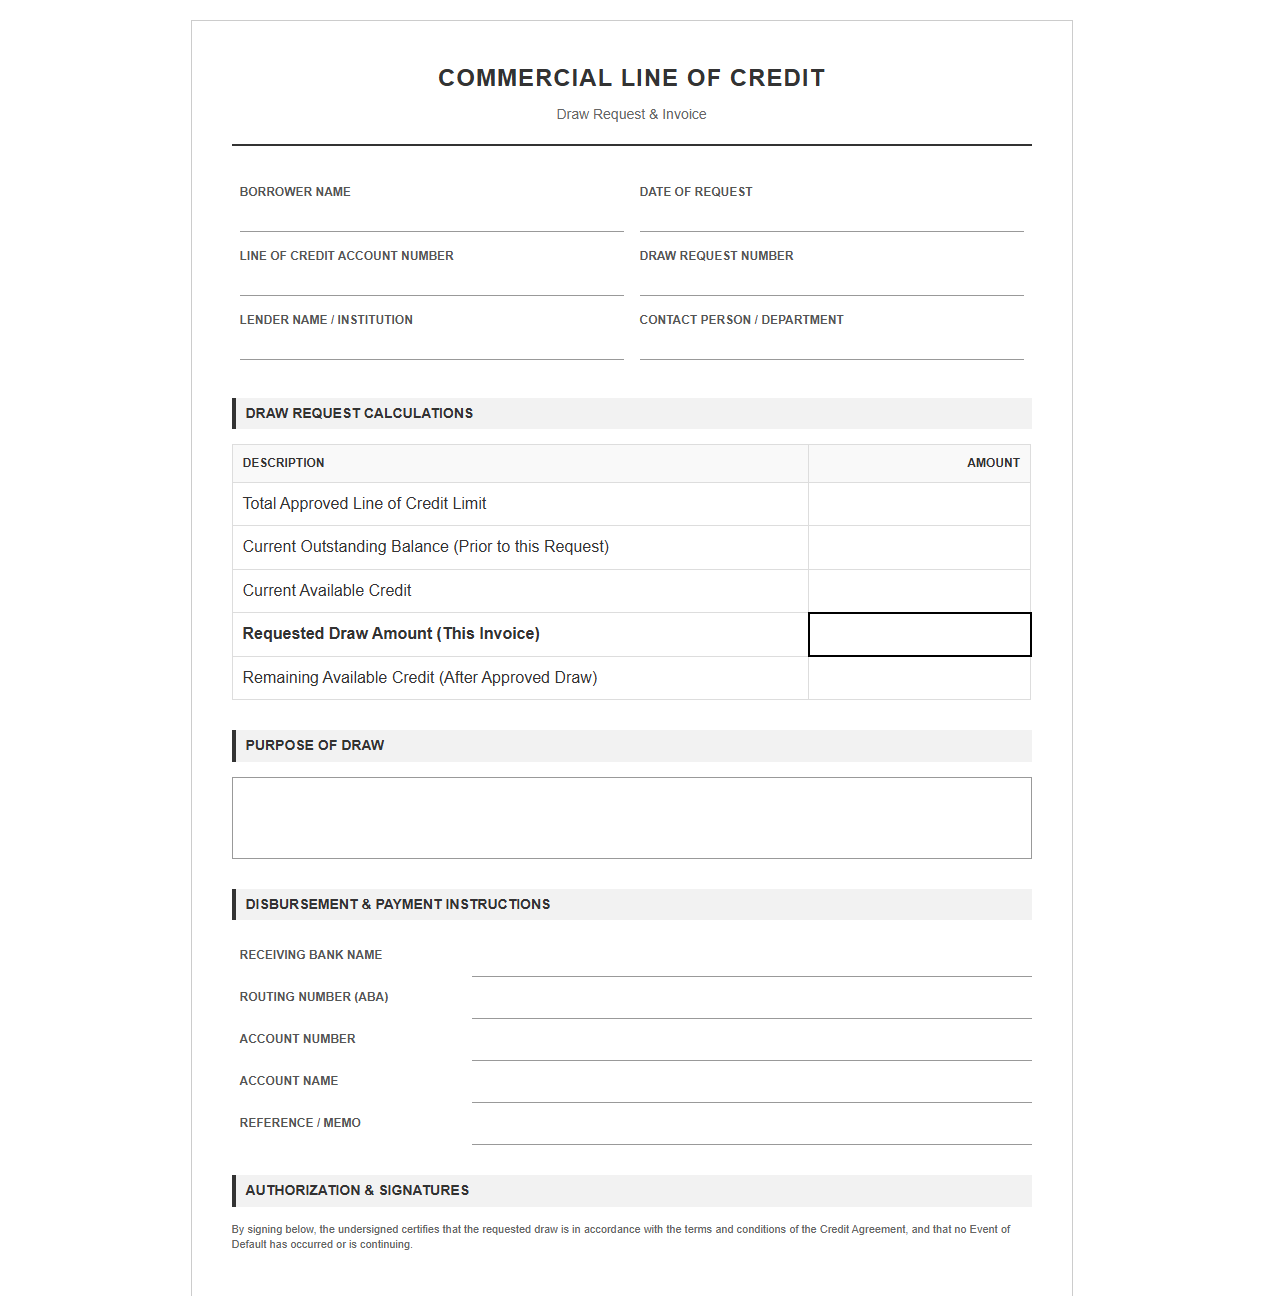 Download: .PDF
Business Credit Facility Invoice Template
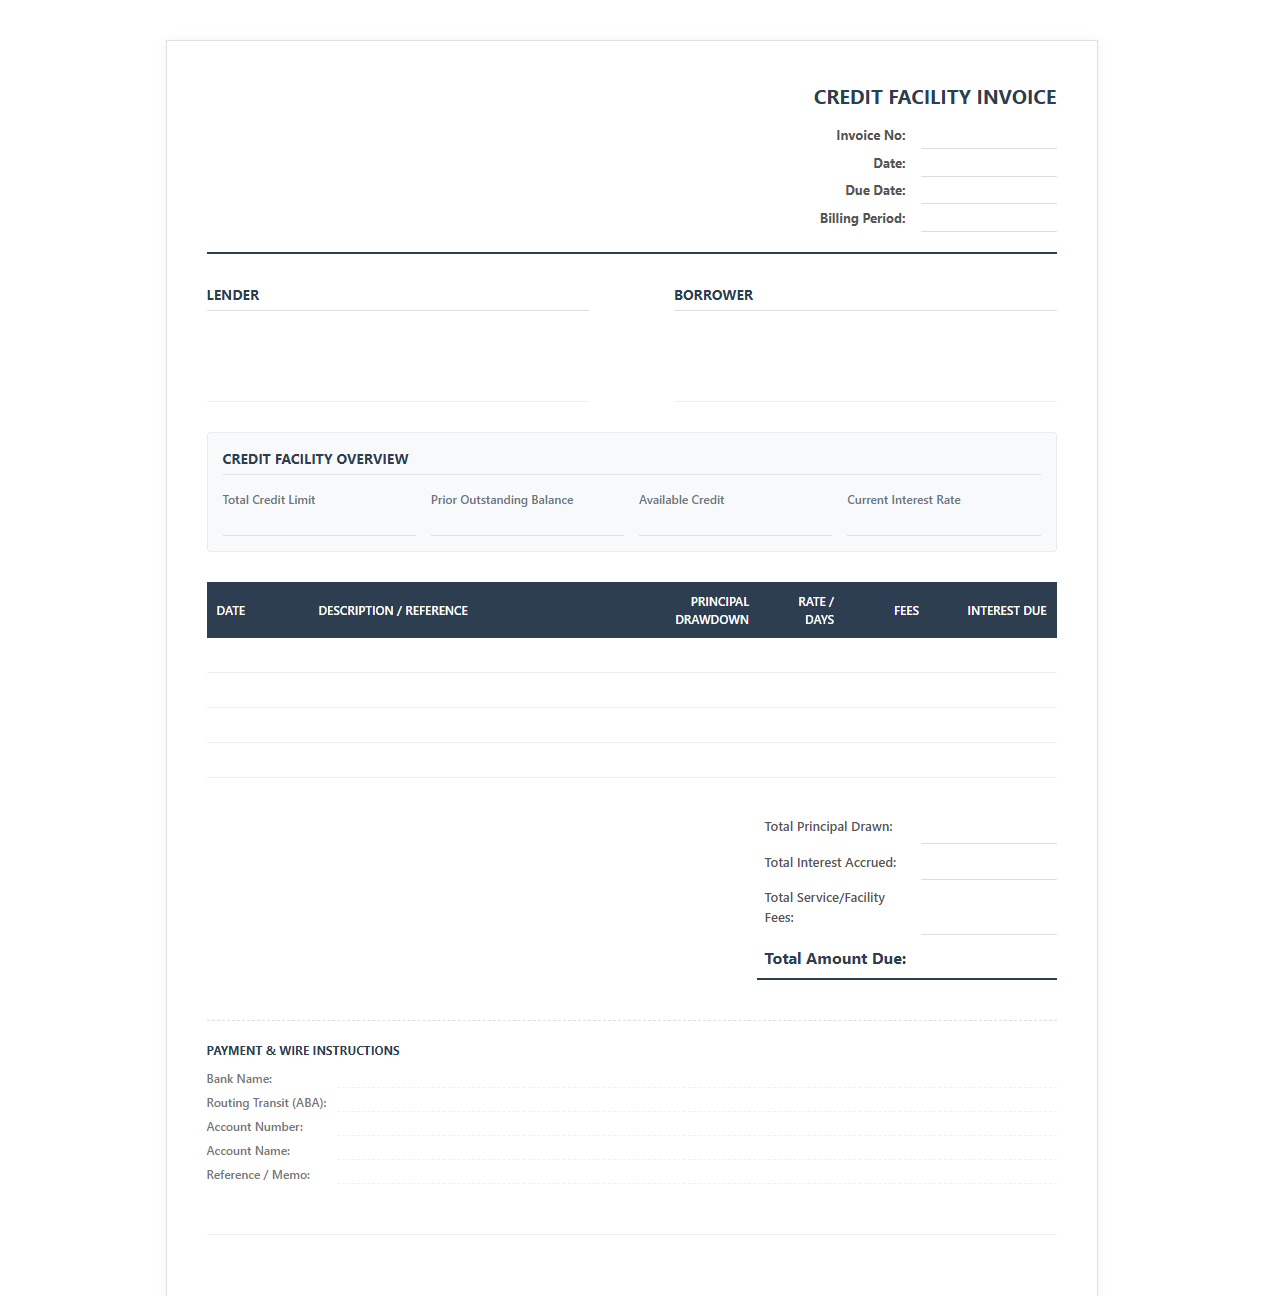 Download: .PDF
Secured Line of Credit Account Invoice
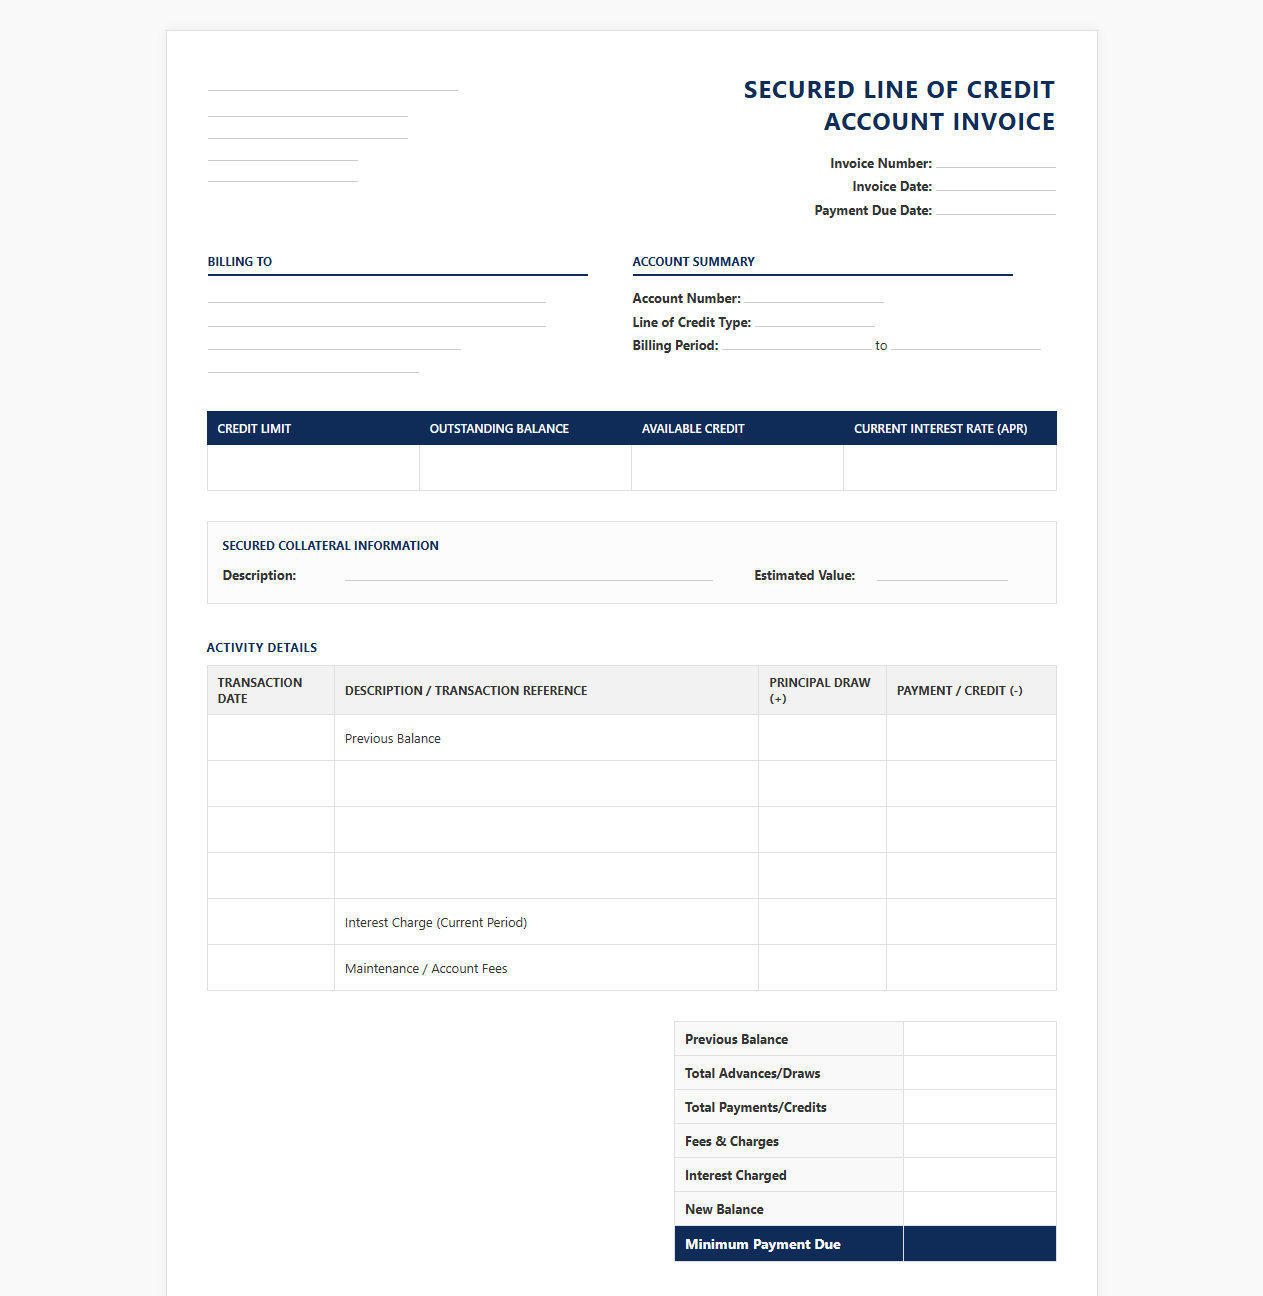 Download: .PDF
Interest Only Line of Credit Invoice
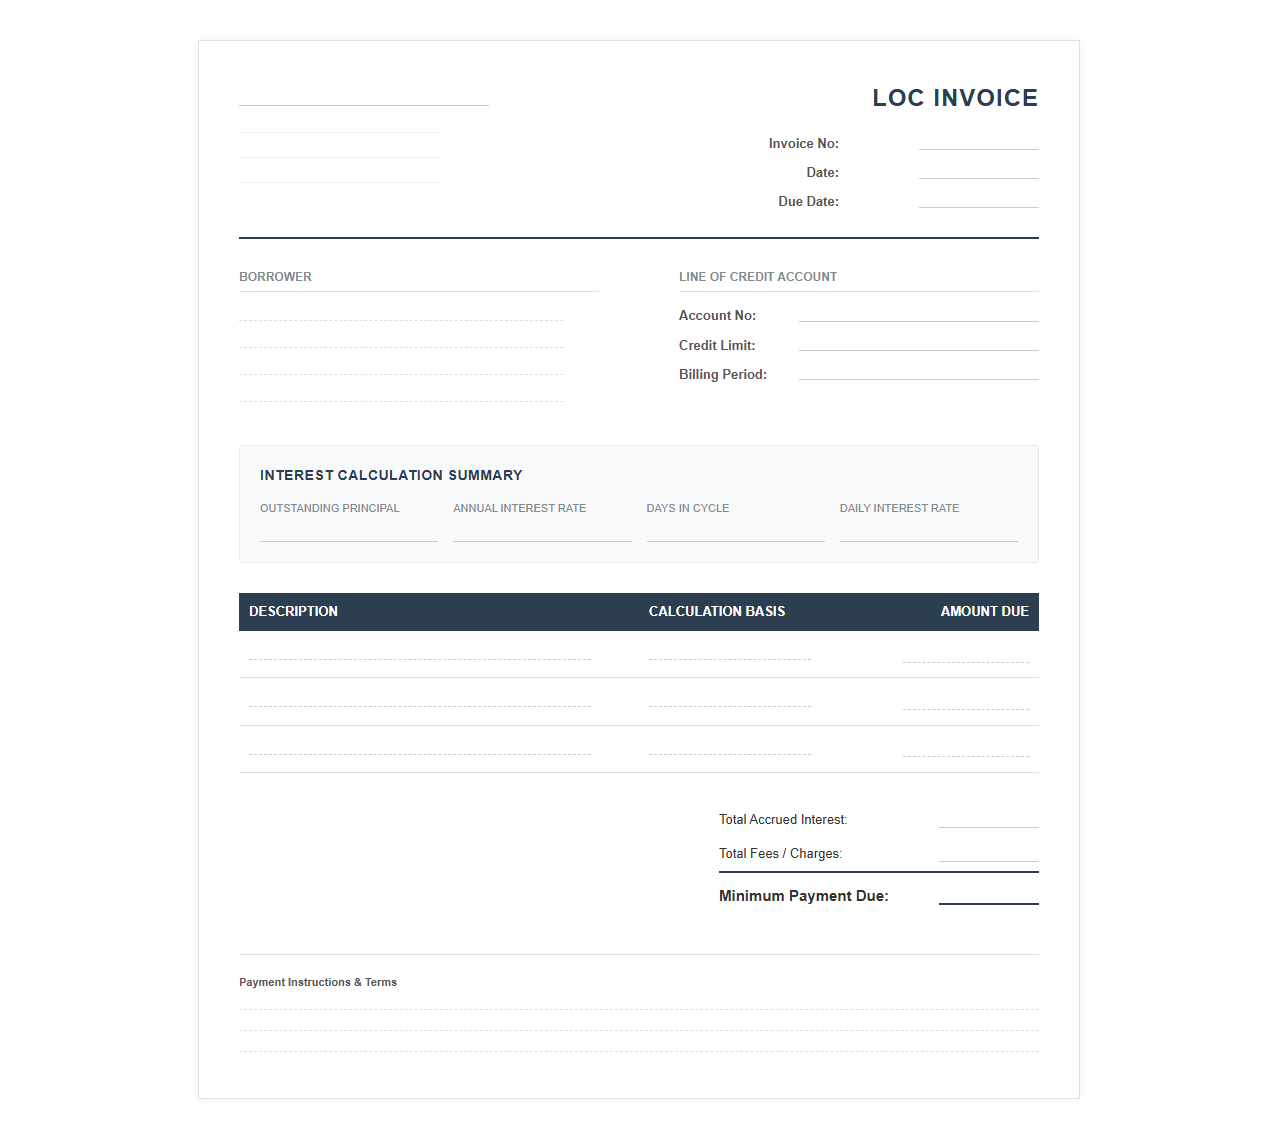 Download: .PDF
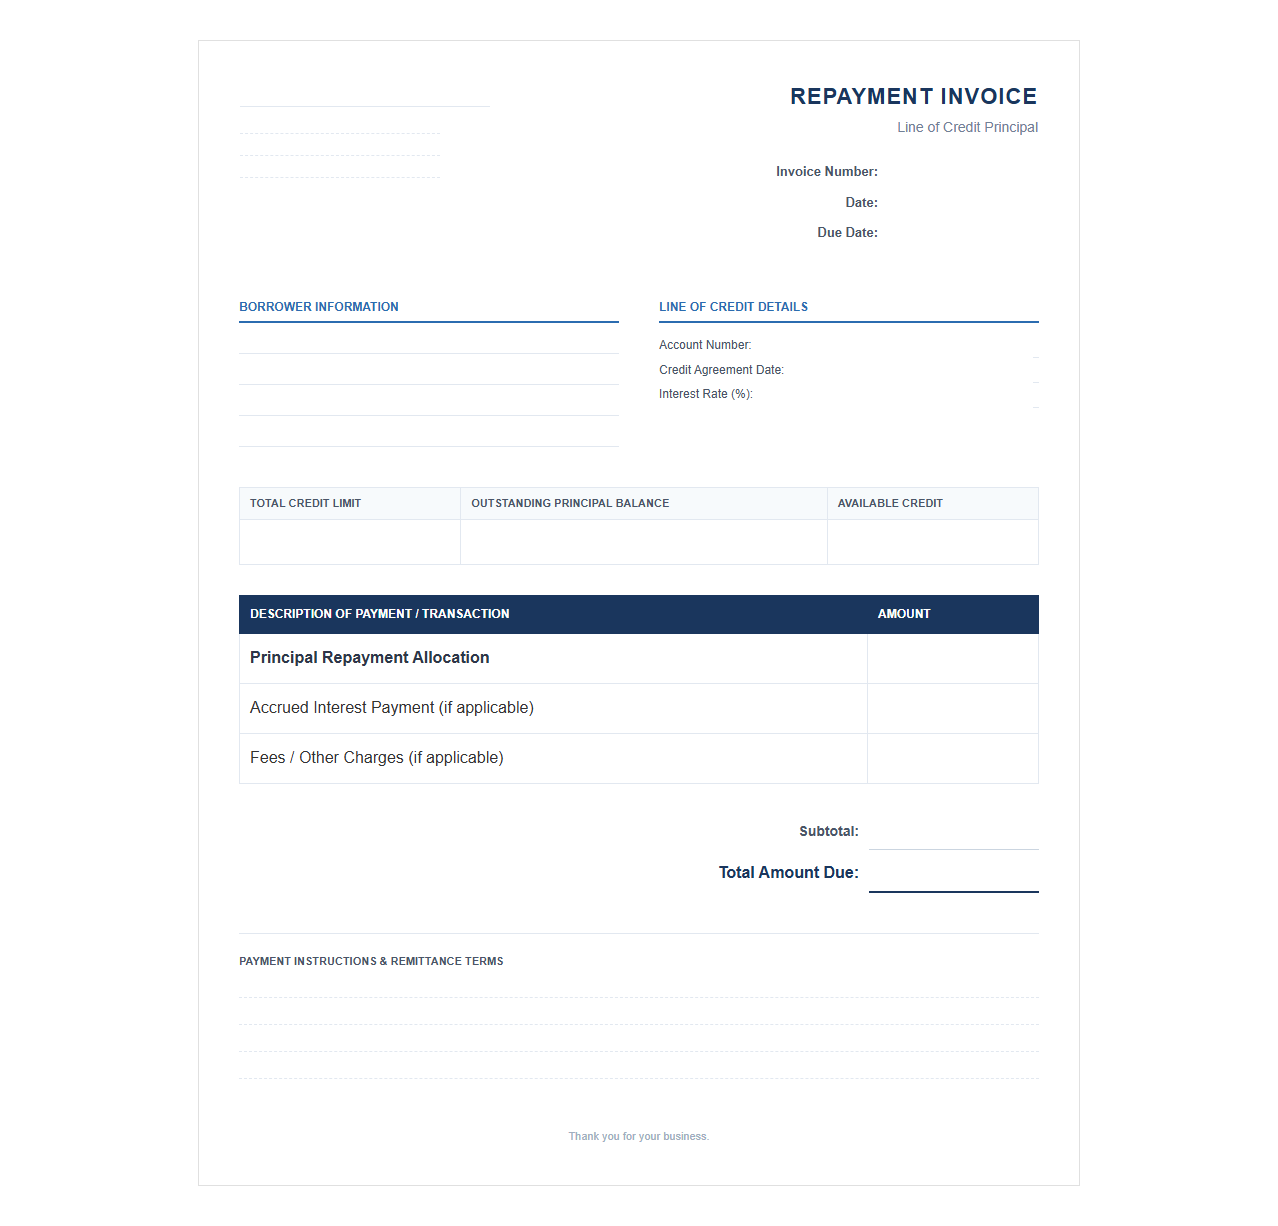
Line of Credit Principal Repayment Invoice
 Download: .PDF
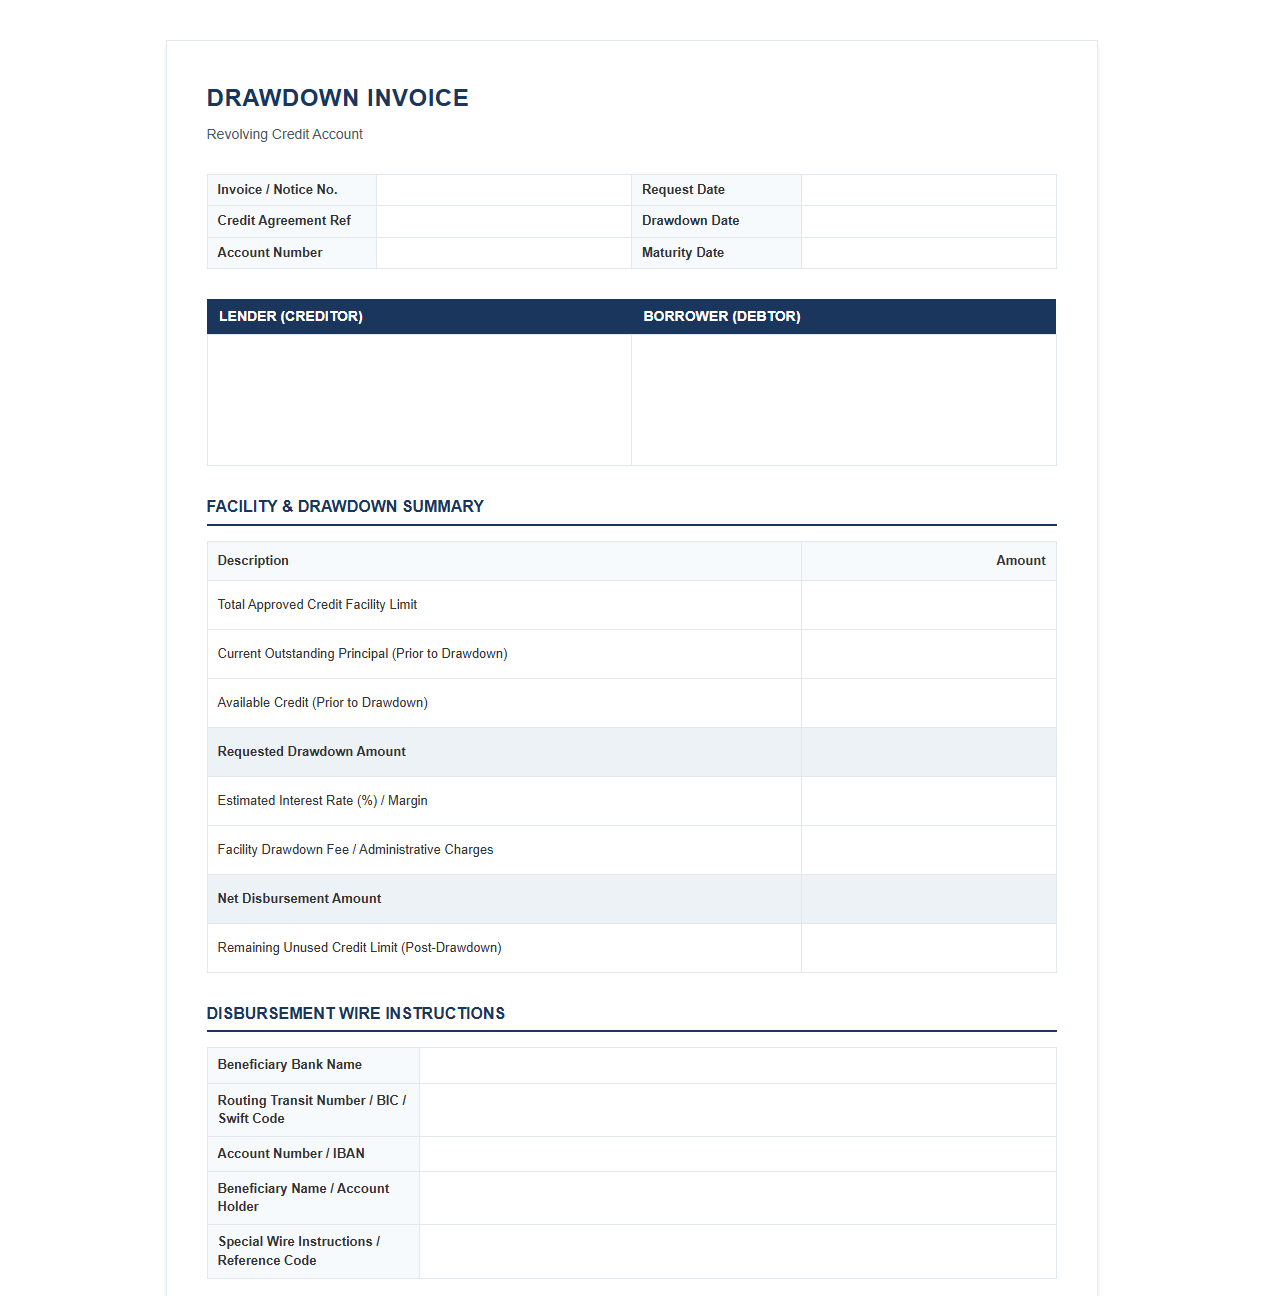
Revolving Credit Account Drawdown Invoice
 Download: .PDF
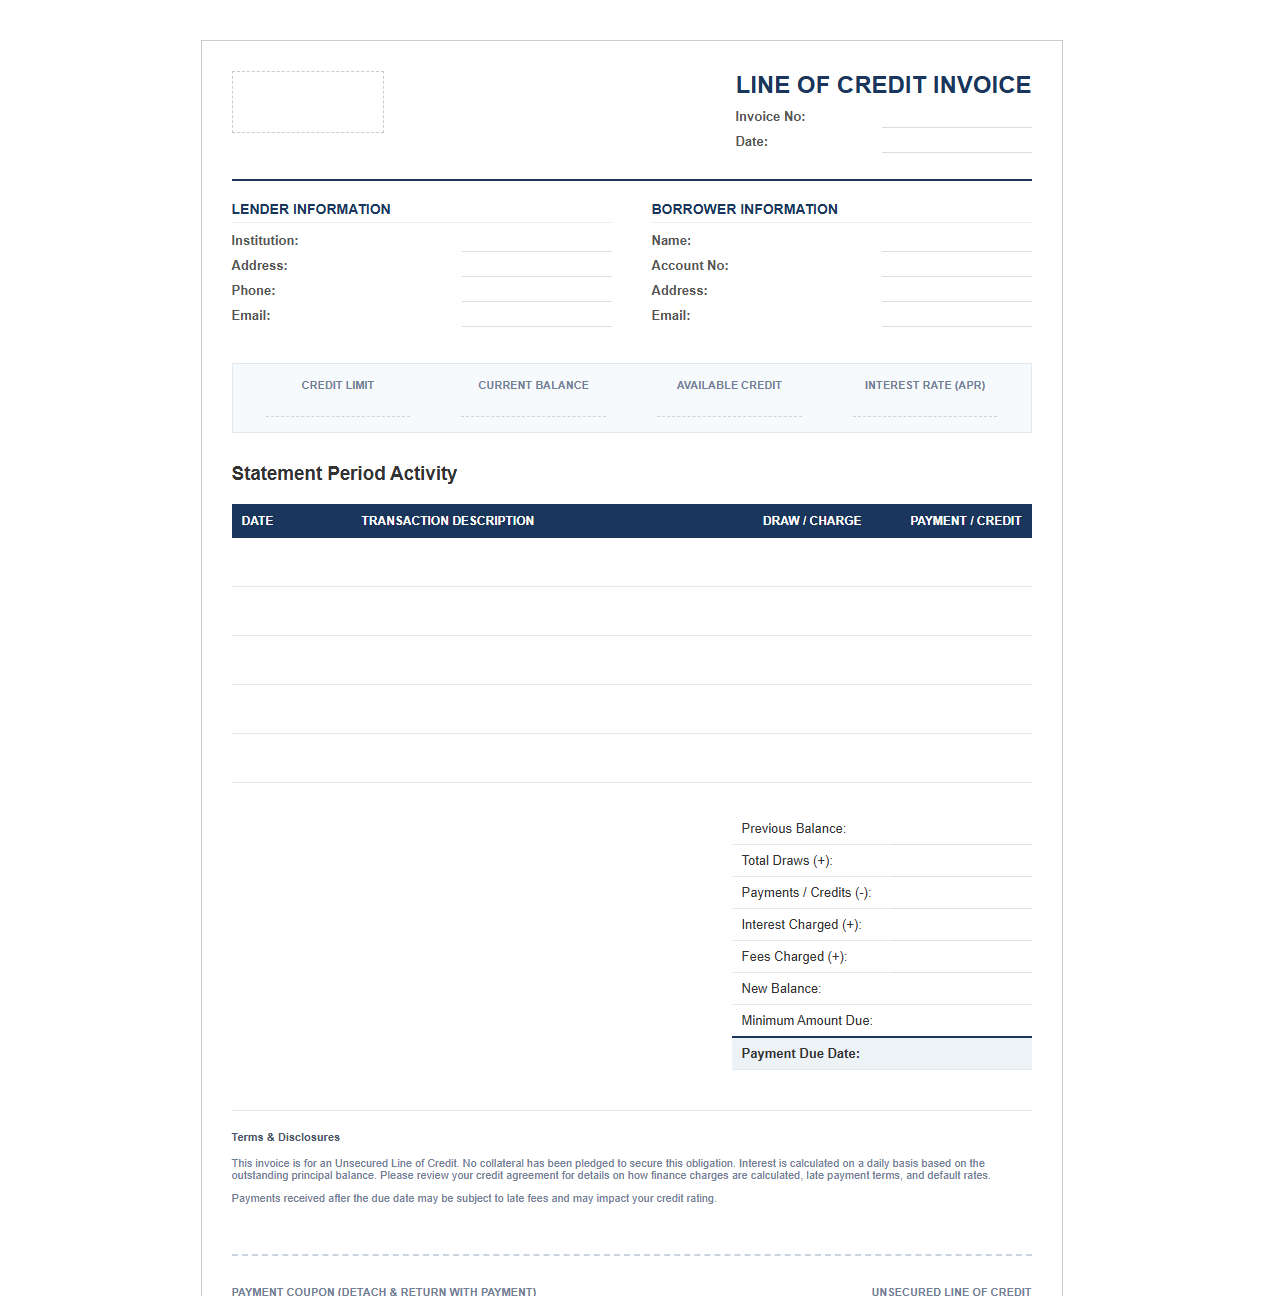
Unsecured Line of Credit Invoice Template
 Download: .PDF
The Challenges of Manual Line of Credit Draw Requests
Traditional commercial lending often relies on paper-based or semi-structured PDF draw requests to access active credit lines. When borrowers submit these manual documents, lenders face severe administrative bottlenecks. Processing staff must manually review, verify, and transcribe invoice details into core banking systems. This fragmented process significantly slows down funding operations and introduces a high probability of data entry errors. A simple typo can delay liquidity deployment for days, harming the borrower's cash flow and increasing operational costs for the financial institution. Operating in this non-standardized environment leaves lenders exposed to inefficiencies that limit scalability.
Adopting Structured Invoice Formats as the Solution
To bridge the operational gap between accounts payable workflows and credit facility management, financial systems must transition to machine-readable document standards. Utilizing uniform formats allows lenders to ingest invoice data automatically and execute verification checks instantly.
UBL XML– A standardized XML format widely adopted in international trade to represent business documents.JSON-LD– A lightweight Linked Data format that integrates easily into modern web APIs and databases.Factur-X– A hybrid PDF/XML standard that provides a human-readable visual invoice alongside structured metadata.
Critical Data Points for Standardized Validation
For automated draw requests to function seamlessly, incoming datasets must contain standardized, mandatory metadata fields. Automated credit platforms rely on these specific parameters to perform systematic risk assessments and ensure compliance before releasing funds.
- Unique Invoice ID: A distinct alphanumeric identifier to track the transaction and prevent duplication.
- Vendor and Debtor Details: Explicit legal names, tax identifiers, and addresses of both parties to verify authenticity.
- Payment Terms and Due Dates: Clear terms governing when the payment is due to assess the aging of the asset.
- Total Invoice Value and Currency: The exact monetary figures being financed, mapped to the approved currency of the credit line.
Automating the Reconciliation and Verification Pipeline
Automated parsing engines process structured invoices to eliminate human oversight in the daily reconciliation loop. These systems continuously compare incoming draw requests against the borrower's total credit facility parameters. By running programmatic checks, the engine confirms that the requested drawdown does not exceed the pre-approved concentration limits or current outstanding balances. When a validation check succeeds, the transaction progresses to disbursement status without manual touchpoints. This level of automated control ensures that compliant drawdowns are executed with absolute precision and speed.
Enhancing Security and Preventing Double-Financing Fraud
One of the most persistent threats in receivables-based lending is double financing, where a borrower submits the same invoice to multiple lenders. Transitioning to structured data facilitates the creation of unique cryptographic hashes for every invoice. Lenders can check these hashes against shared or private ledgers to verify that the asset has not already been leveraged elsewhere.
Cryptographic fingerprinting allows financial institutions to collaborate on risk mitigation without exposing sensitive customer data, neutralizing duplicate financing attempts before funding occurs.Global Trade Finance Association
Step-by-Step Integration for Financial Institutions
Modernizing treasury platforms to natively ingest structured draw requests requires a systematic upgrade of legacy systems. Financial institutions can adopt a clear integration path to transition away from manual processing.
- Expose Ingestion APIs: Build robust endpoints designed to accept structured payloads such as JSON-LD directly from ERP platforms.
- Map Data Schemas: Align incoming structured invoice fields to the core banking ledger and risk engine schemas.
- Implement Rules Engines: Configure automated verification routines to validate debtor concentration limits and credit availability in real time.
- Connect to Treasury Orchestrators: Integrate verified outputs directly into internal clearing networks for instant payment execution.
The Future of Real-Time Liquidity via API-Driven Facilities
The evolution of commercial finance is pointing toward a complete transition away from traditional batch processing. Instead of sending consolidated files at the end of the day, commercial borrowers will rely on programmatic integrations. Working capital systems will trigger instantaneous, API-driven draw requests the moment an eligible transaction is registered in their ERP. These self-executing facilities, governed by smart contracts and embedded business logic, provide borrowers with just-in-time liquidity. Lenders who adopt these instant-access models will capture deeper market share, offering a frictionless user experience while simultaneously reducing operational exposure.
Leave a comment