For innovative companies, claiming the R&D tax credit is a powerful mechanism for fueling growth, yet surviving a subsequent regulatory audit often feels like an administrative nightmare. As tax authorities globally intensify their scrutiny of these claims, the burden of proving eligible activities rests heavily on the quality of your contemporaneous documentation.
Fortunately, structuring your invoice templates correctly safeguards your deserved funding while eliminating audit-related anxiety. However, a template is only as effective as the technical tracking supporting it; it must seamlessly bridge the gap between financial billing and actual engineering efforts. For instance, rather than invoicing a flat-fee "software development" service, compliant invoices should explicitly isolate hours dedicated to qualified phases, such as "iterative algorithm prototyping."
In this article, we will examine how to structure your R&D invoice templates to establish a bulletproof audit trail, detailing the essential data fields and documentation frameworks required to satisfy rigorous tax examiners.
Research and Development Tax Credit Invoice Template
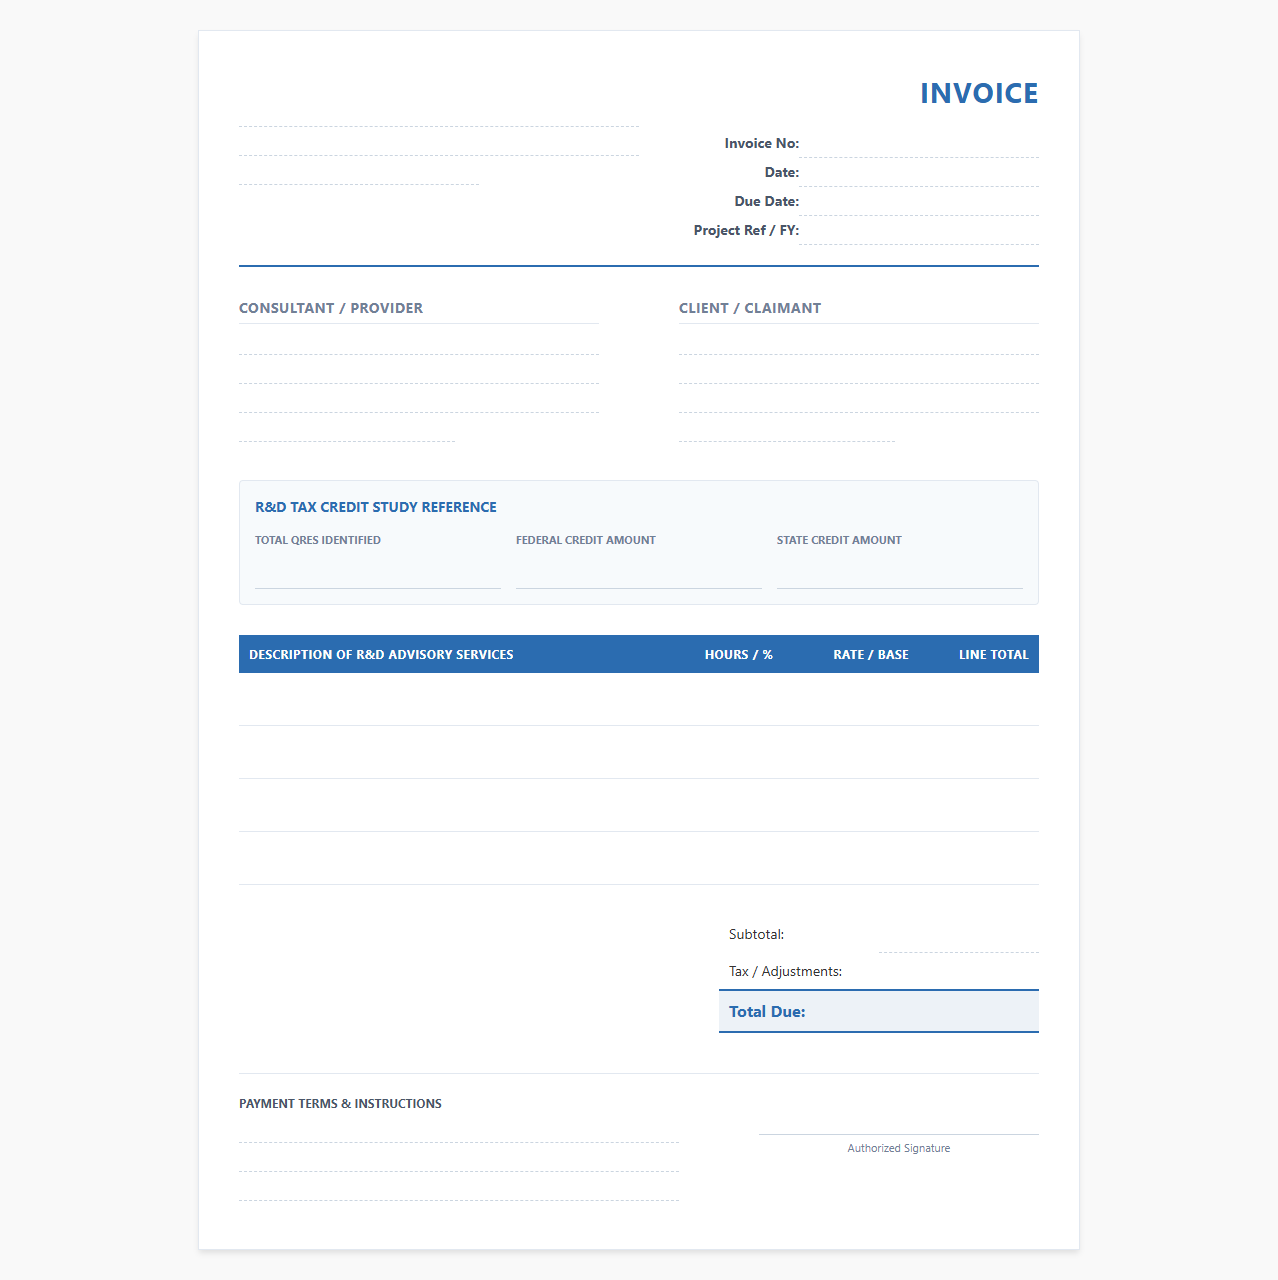 Download: .PDF
R&D Tax Relief Eligible Billing Document
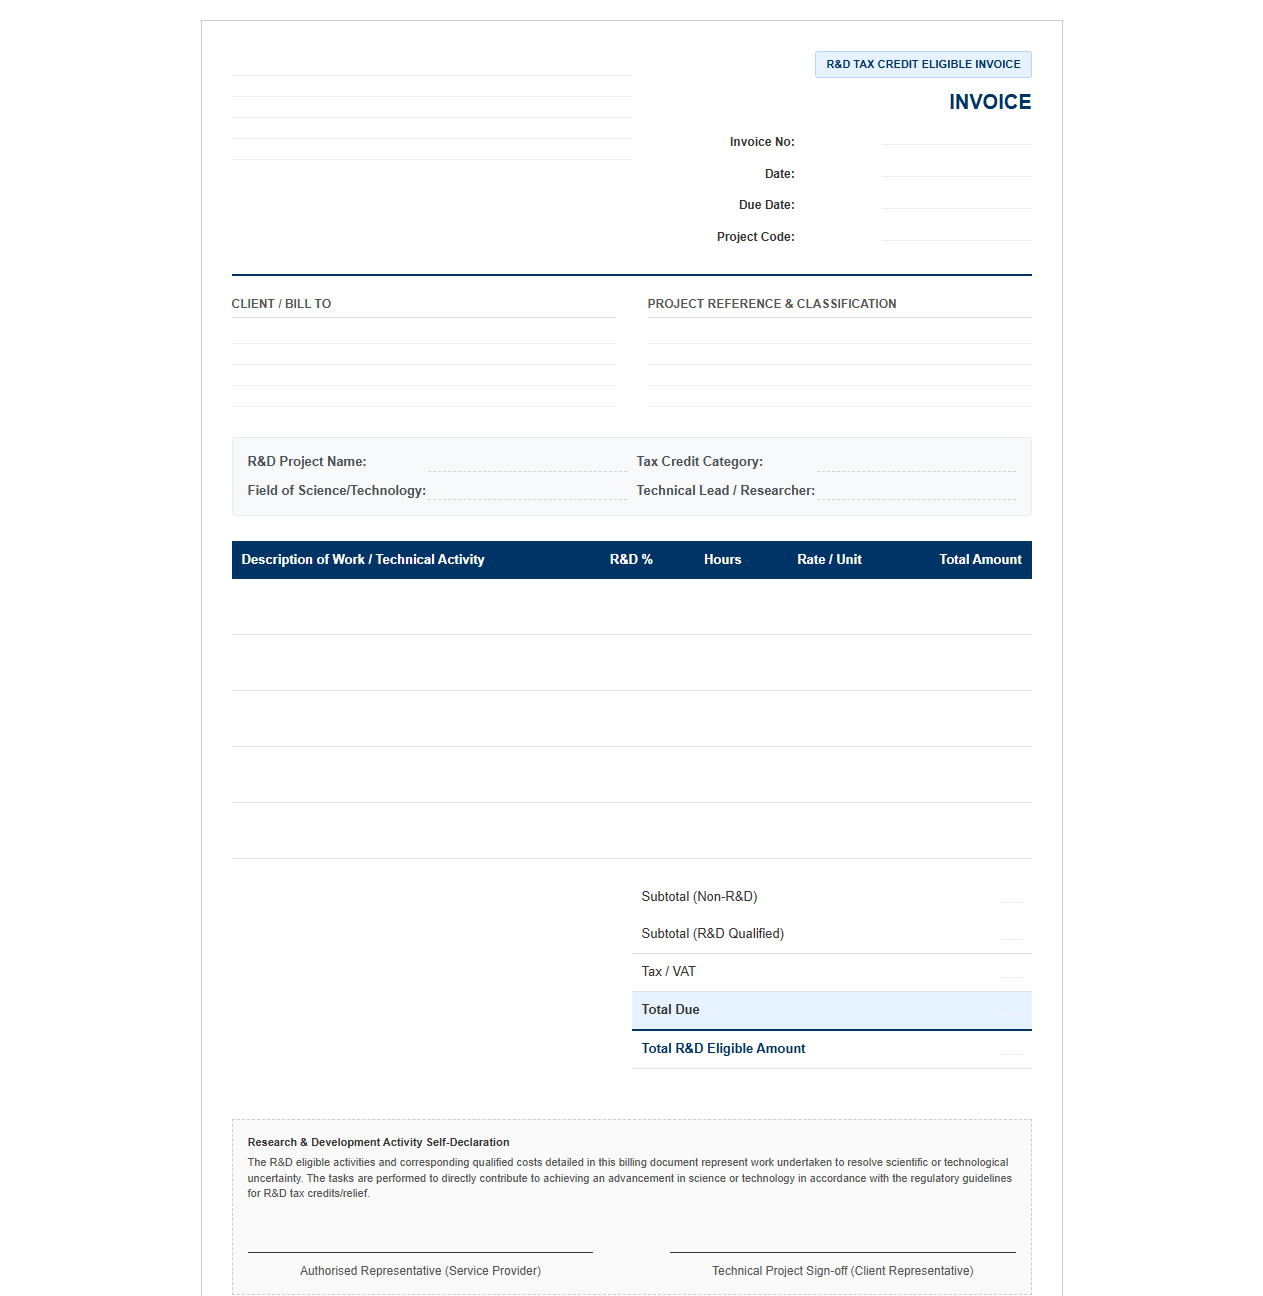 Download: .PDF
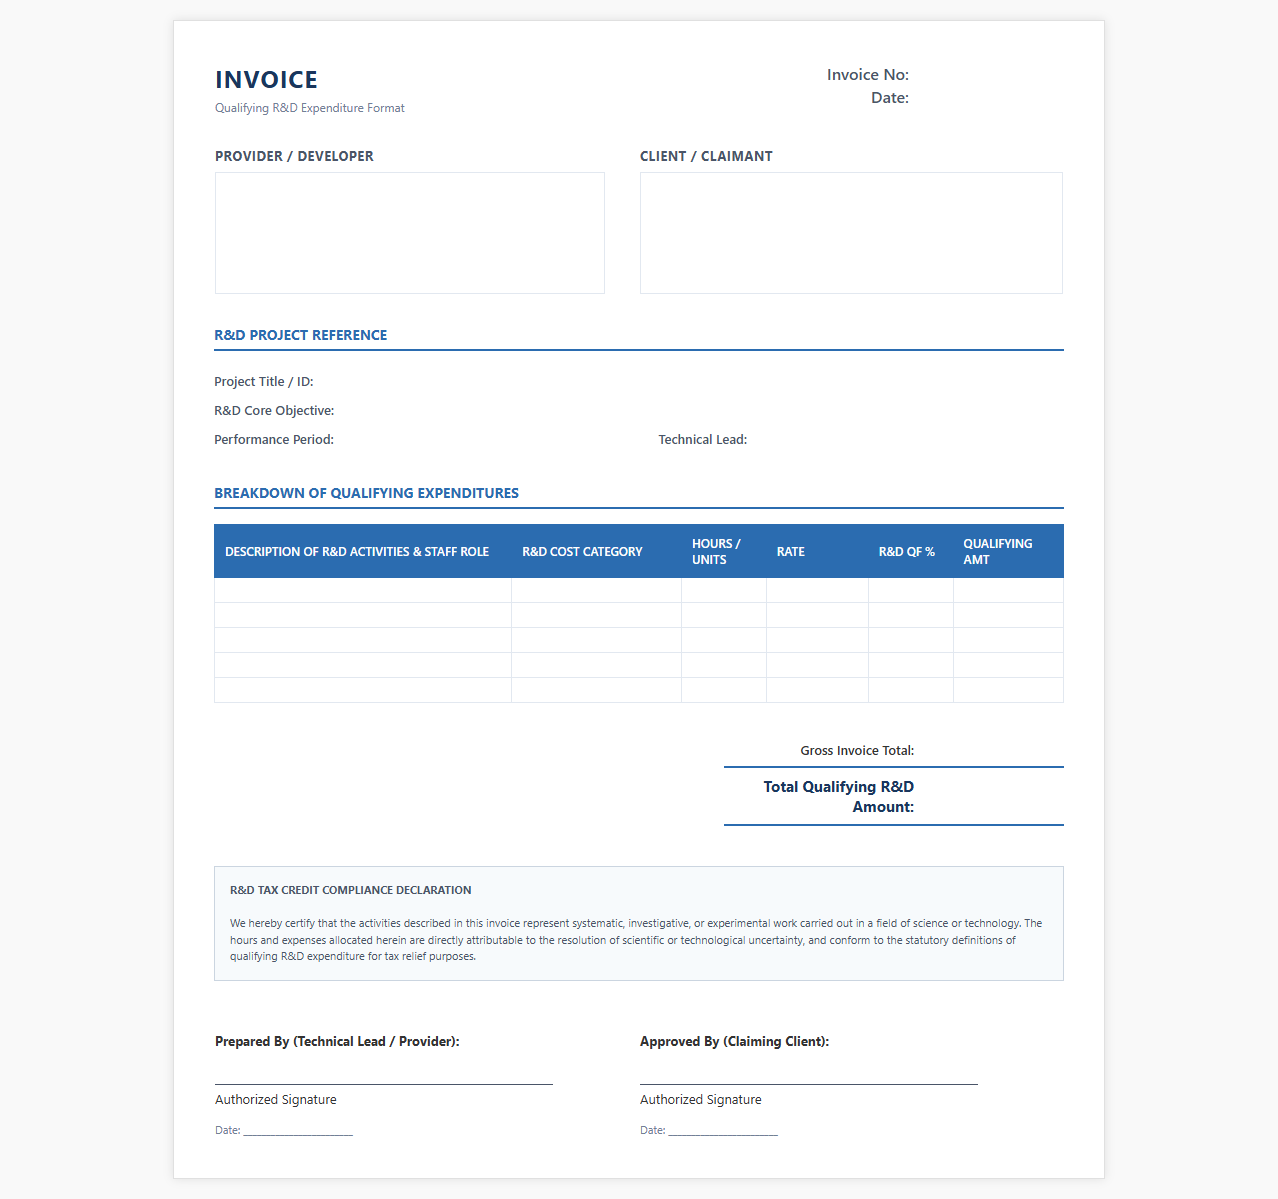
Qualifying R&D Expenditure Invoice Format
 Download: .PDF
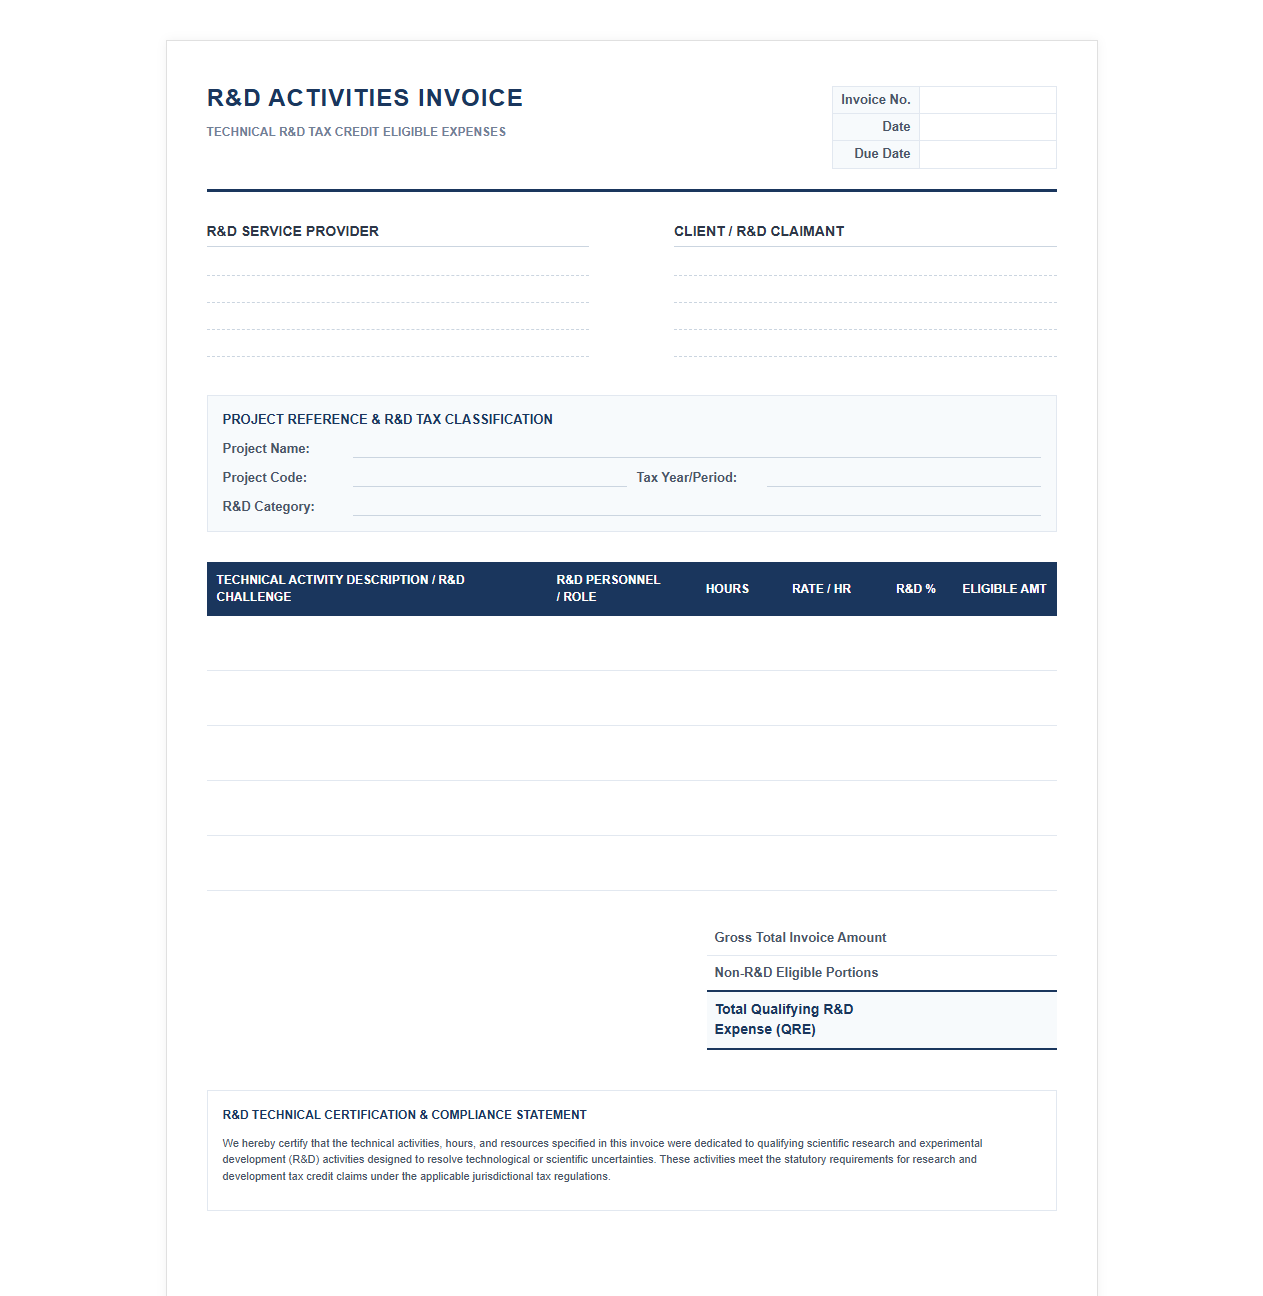
Technical R&D Activities Tax Credit Invoice
 Download: .PDF
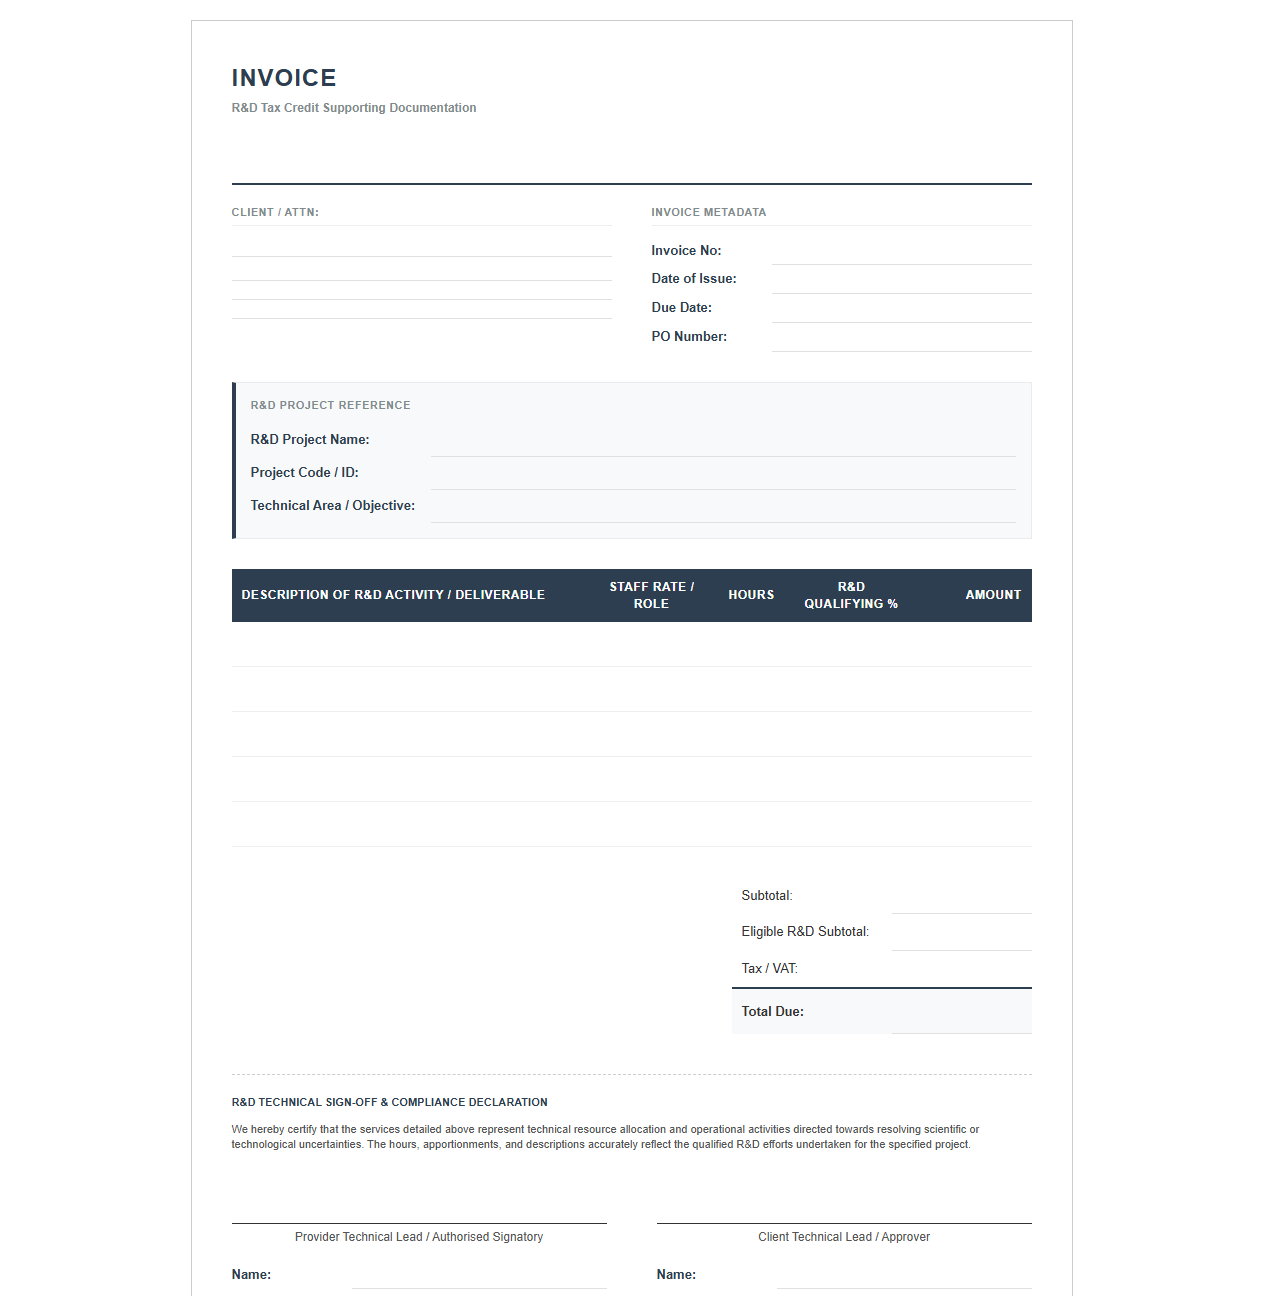
R&D Claim Supporting Invoice Template
 Download: .PDF
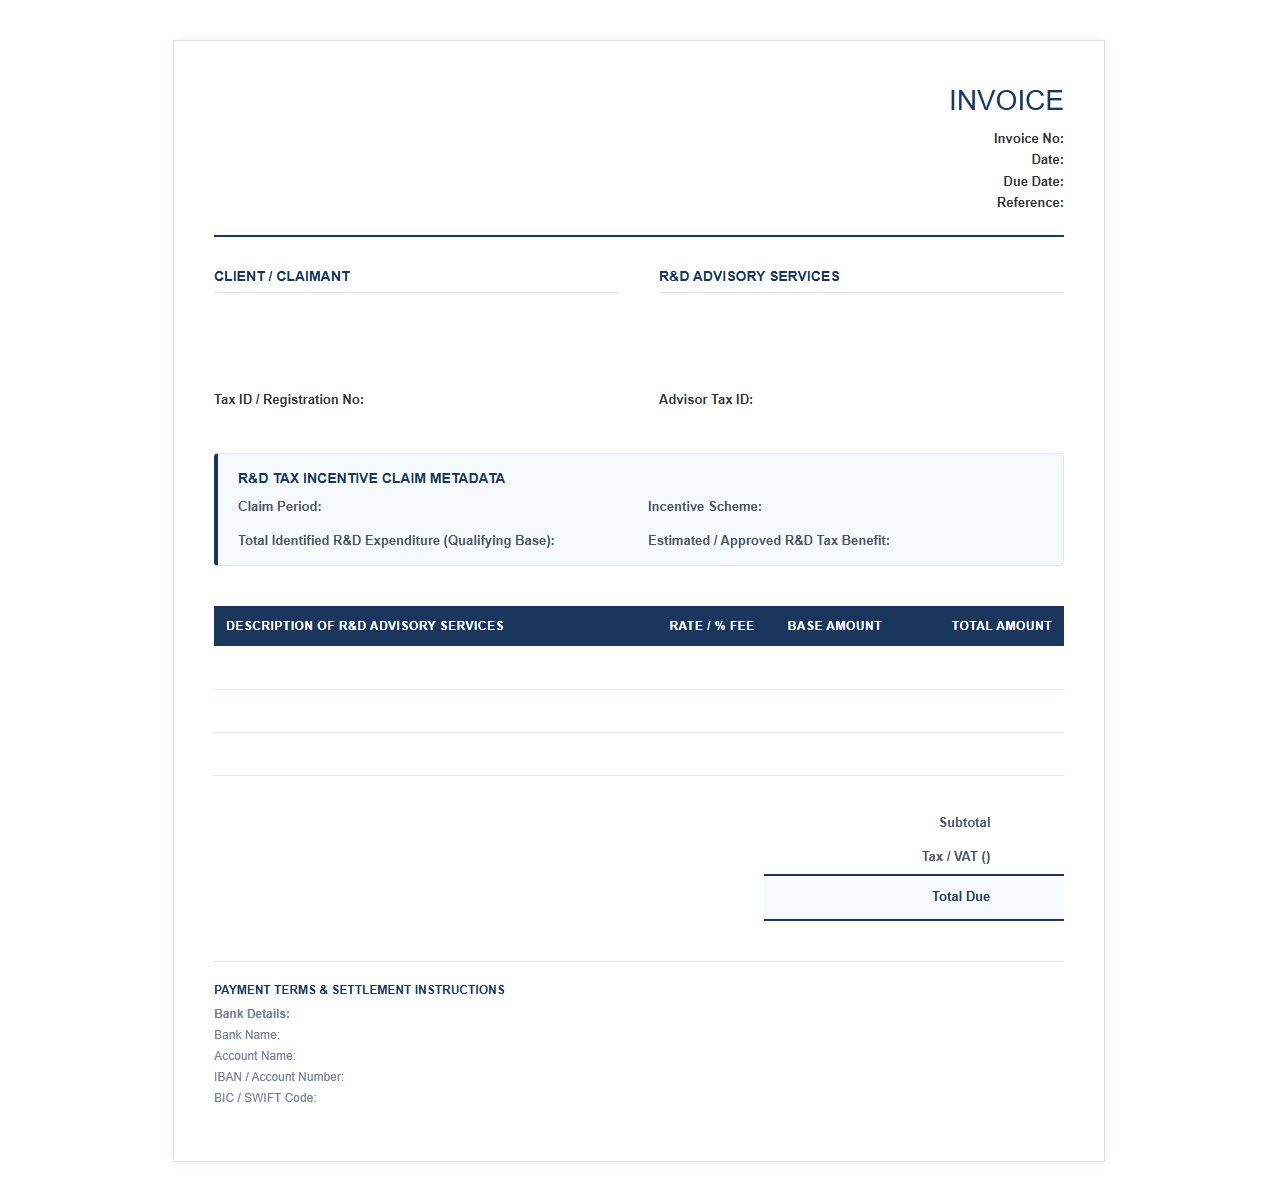
Government R&D Tax Incentive Billing Template
 Download: .PDF
R&D Project Cost Breakdown Invoice
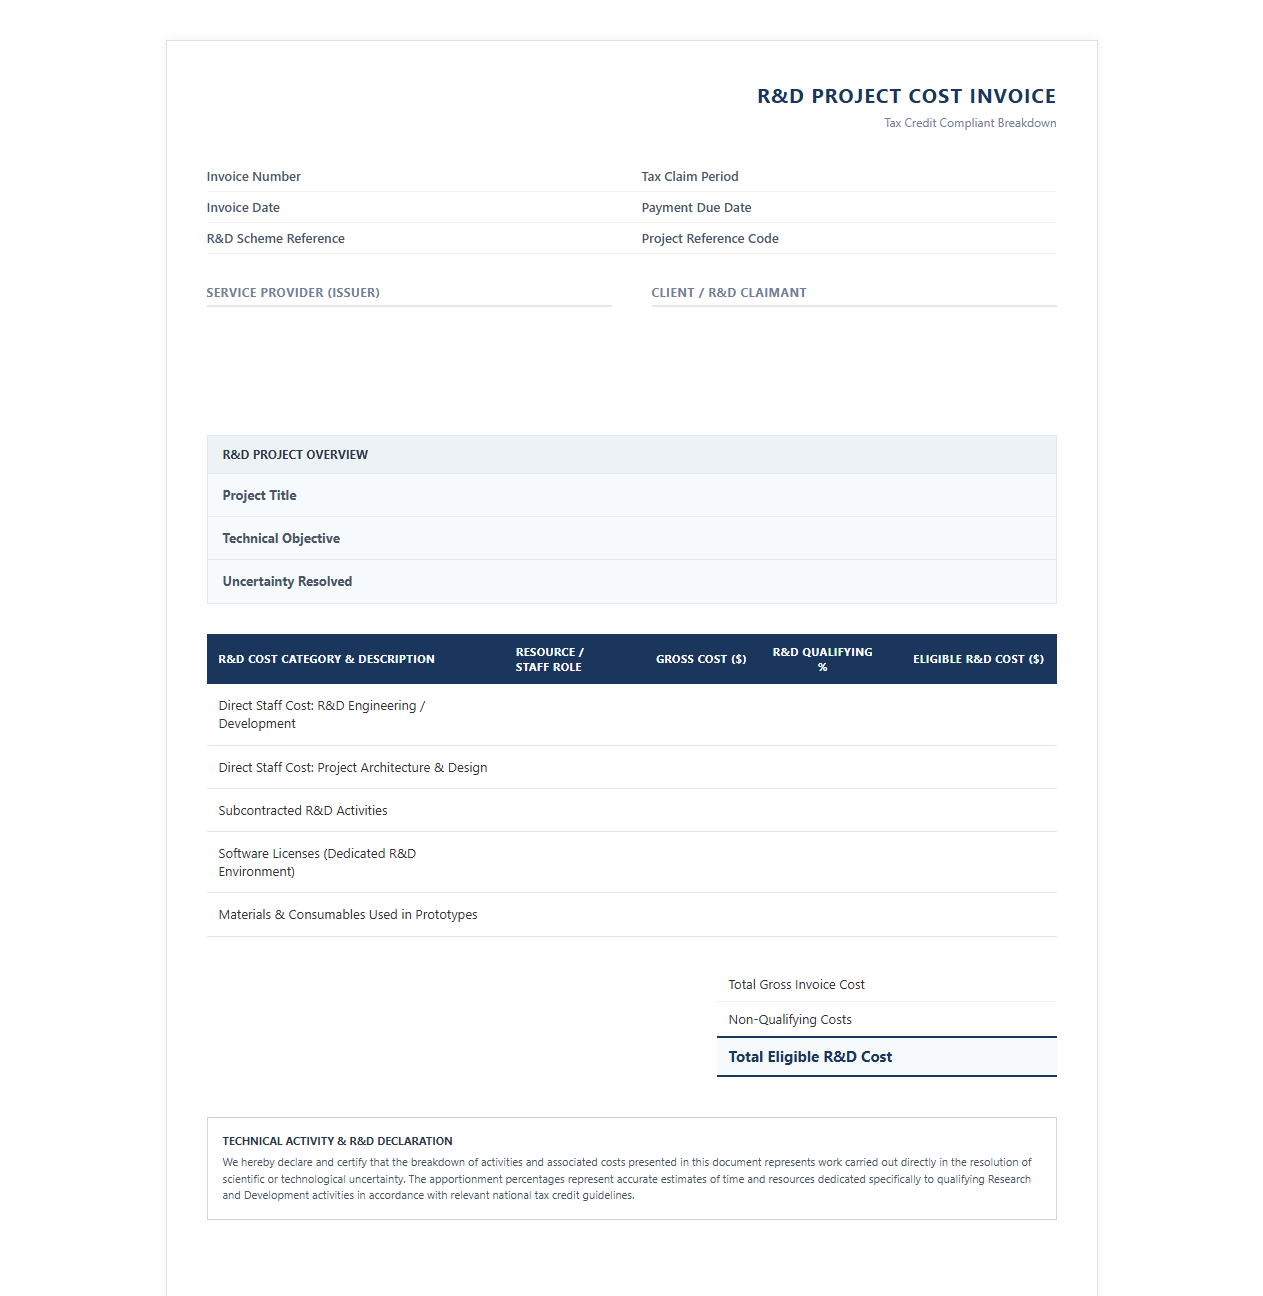 Download: .PDF
R&D Tax Credit Compliant Invoice
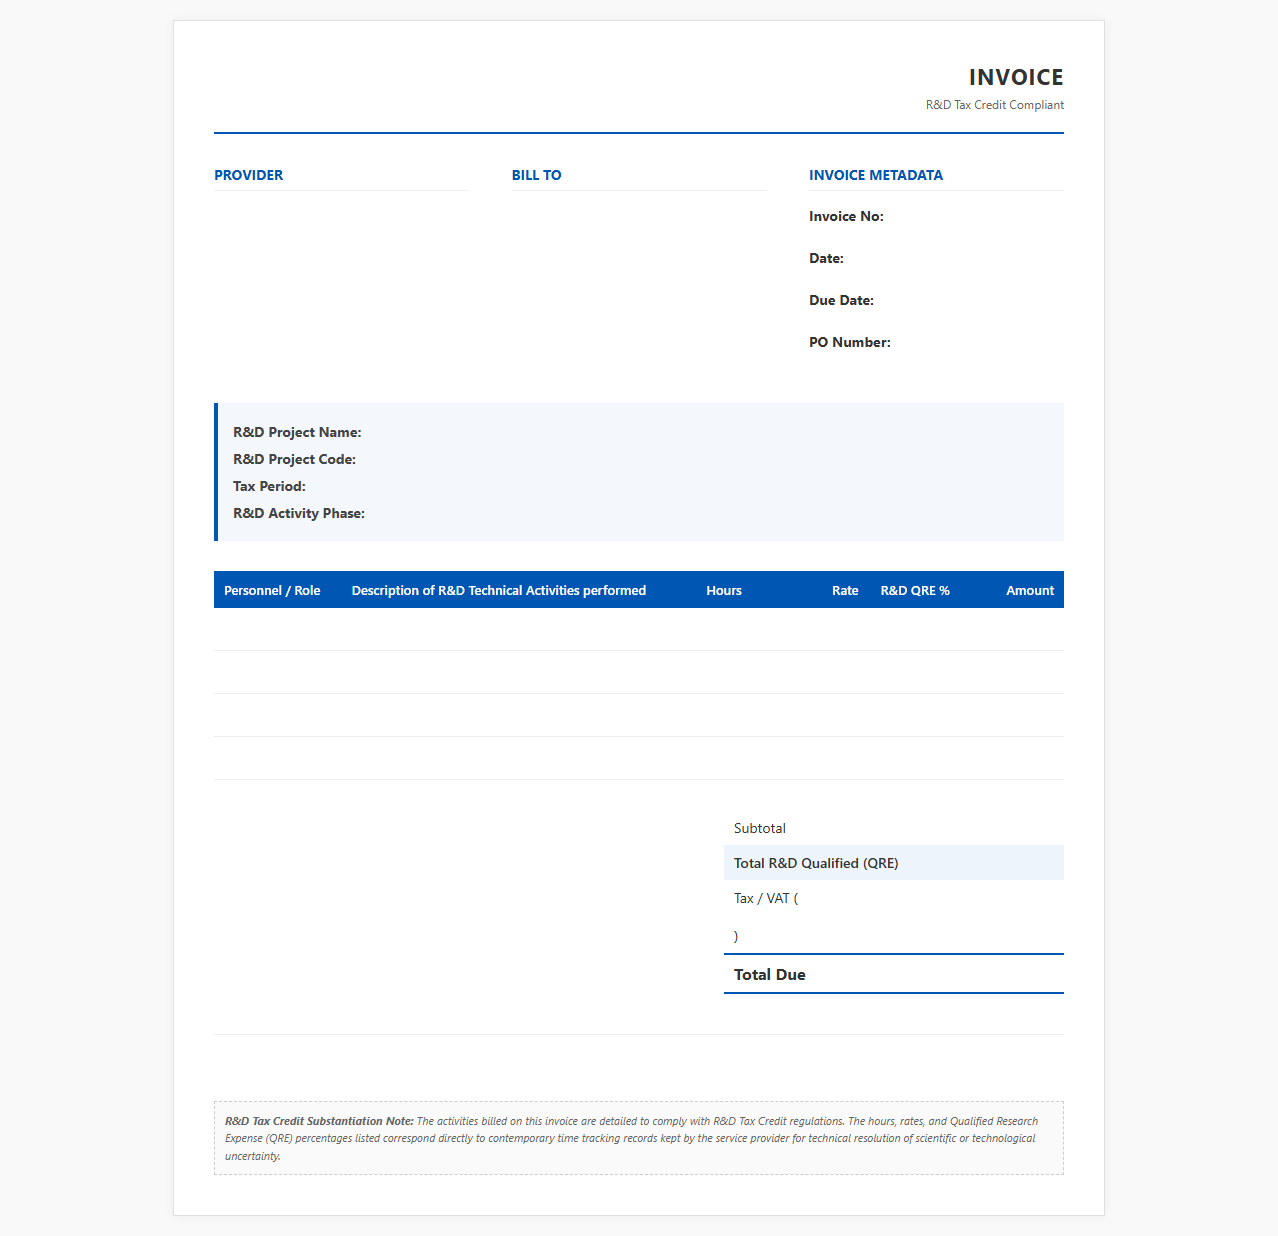 Download: .PDF
Introduction to R&D Tax Credit Compliant Invoicing
Claiming Research and Development (R&D) tax credits can significantly offset innovation costs, but it requires rigorous documentation to withstand scrutiny from tax authorities. Standard commercial invoices often lack the specificity needed to prove that expenses qualify under strict tax guidelines. When an audit occurs, the absence of detailed financial evidence is the primary reason claims are rejected or reduced.
A highly structured invoice serves as the primary bridge between your financial ledger and your technical R&D activities. By embedding precise data into your invoicing workflow, you establish a contemporaneous audit trail that justifies your expenditures from day one. Implementing compliant invoicing structures protects your business from costly adjustments and ensures your technical progress is legally synchronized with your financial claims.
Essential Invoice Metadata and Unique Identifiers
Tax authorities require clear documentation to verify the legitimacy of transactions. Standard invoice metadata must be pristine, leaving no room for ambiguity regarding who performed the work and when it occurred.
Mandatory Administrative Fields
Every invoice submitted as part of an R&D tax credit claim must contain standard, unalterable administrative identifiers. These fields allow auditors to cross-reference transactions with bank statements and general ledgers.
- Unique Invoice Number: A sequential, non-repeating identifier to prevent duplicate claims and prove systematic accounting.
- Complete Issuer Details: The legal name, registered business address, and tax identification number (TIN) of the contractor or partner entity.
- Clear Recipient Details: The exact legal name of your entity claiming the credit, matching your tax filings precisely.
- Issue Date and Tax Point: The exact date the invoice was generated, which dictates the tax year and credit cycle the qualifying expenses belong to.
Structuring Granular R&D Project Line Items
Generic descriptions like "IT consulting services" or "software development support" are major red flags for auditors. Invoices must isolate qualifying activities from routine commercial work by employing granular line-item breakdowns.
"Invoices must clearly delineate the technical challenges addressed, separating eligible experimentation from standard maintenance or post-release support."
To establish a bulletproof audit defense, ensure every line item links directly to a specific R&D project phase. Descriptions should reflect the systematic investigation process, highlighting activities such as prototype modeling, algorithmic optimization, iterative testing, or physical material experimentation. This structural clarity proves to tax examiners that you are only claiming activities that meet the statutory definitions of research and development.
Documenting Eligible Labor and Time Allocation
Labor constitutes the largest portion of most R&D claims. When utilizing external contractors or specialized staff, your invoices must explicitly connect financial compensation to specific units of time and technical roles.
Labor Cost Breakdown
The table below demonstrates how to format labor-related invoice items to satisfy the documentation requirements of tax authorities.
| Personnel Role | Project / Activity Phase | Hourly Rate ($) | Hours Worked | Total Cost ($) |
|---|---|---|---|---|
| Senior Lead Architect | Phase 2: Algorithmic Scalability Testing | 150.00 | 45.5 | 6,825.00 |
| DevOps Engineer | Phase 3: Automated Sandbox Simulation | 110.00 | 30.0 | 3,300.00 |
Linking Financial Invoices to Technical R&D Evidence
An invoice should never exist in a financial vacuum. To maximize compliance, the invoice should contain direct references to your technical documentation, creating an integrated, easily navigable audit trail. By inserting specific identifiers-such as Jira epic keys, GitHub repository commits, or internal project codes-directly into the billing text, you explicitly link the financial cost to the technological breakthrough being pursued.
This cross-referencing strategy allows tax auditors to quickly verify the technical reality behind the financial numbers. If an auditor wants to check the validity of a $10,000 billing line for "machine learning integration," they can follow the referenced project code directly to your government-compliant technical report or development sprints, expediting the review process and securing your credit.
Accounting for Retainers, Milestones, and Contingency Fees
Payment terms can influence how tax authorities view the eligibility of your expenses. Flat-rate retainers and complex contingency fees require careful structuring to ensure they do not disqualify your research claims.
When dealing with milestones, payments must be tied to the delivery of specific, documented technical outcomes rather than arbitrary calendar dates. Furthermore, contingency fee structures-where payments are dependent on the success of the tax credit claim-must be fully disclosed and documented. Tax authorities closely scrutinize these arrangements to ensure that the scientific risk of the project was genuinely borne by the claiming taxpayer.
- Define milestone payments by technical deliverables (e.g., "Successful completion of Phase 1 stress testing").
- Avoid vague billing descriptions like "Monthly installment 3 of 6."
- Ensure all service contracts explicitly state which party retains the intellectual property rights and bears the financial risk of failure.
Pre-Submission Compliance Checklist for R&D Invoices
Before submitting any invoice for accounting or preparing your tax credit documentation, perform a final review to ensure perfect alignment with compliance standards. Use this checklist as a quality control gateway.
- Verify that the invoice contains a unique invoice number, correct tax dates, and exact corporate names for both parties.
- Confirm that all generic service descriptions have been replaced with specific, R&D-aligned terminology.
- Check that hourly rates, total hours worked, and personnel roles are clearly detailed for all labor-based line items.
- Ensure that every technical activity billed is cross-referenced with your internal project documentation, timesheets, or code repositories.
- Review any milestone or retainer billing to ensure it is explicitly tied to technical progress rather than generalized commercial retainers.
Leave a comment