For corporate controllers and tax departments, accurately tracking unpaid consumer use tax remains a persistent, high-stakes administrative headache. Before addressing ledger design, however, one must navigate the increasingly complex web of multi-jurisdictional tax rules that complicate manual self-assessment. Standardizing this process with a dedicated ledger template grants your team immediate audit-readiness and eliminates the risk of costly state penalties.
Please note: while standardized templates streamline operational compliance, they serve as a structural tool and should not substitute for certified CPA counsel. To be effective, your ledger must track specific concrete data, such as out-of-state asset acquisitions, untaxed digital service invoices, and localized tax rate differentials. Below, we will outline the essential anatomy of a standardized use tax payable ledger, detail best practices for monthly reconciliation, and provide actionable framework templates to insulate your organization from liability risks.
Use Tax Payable Ledger Sheet
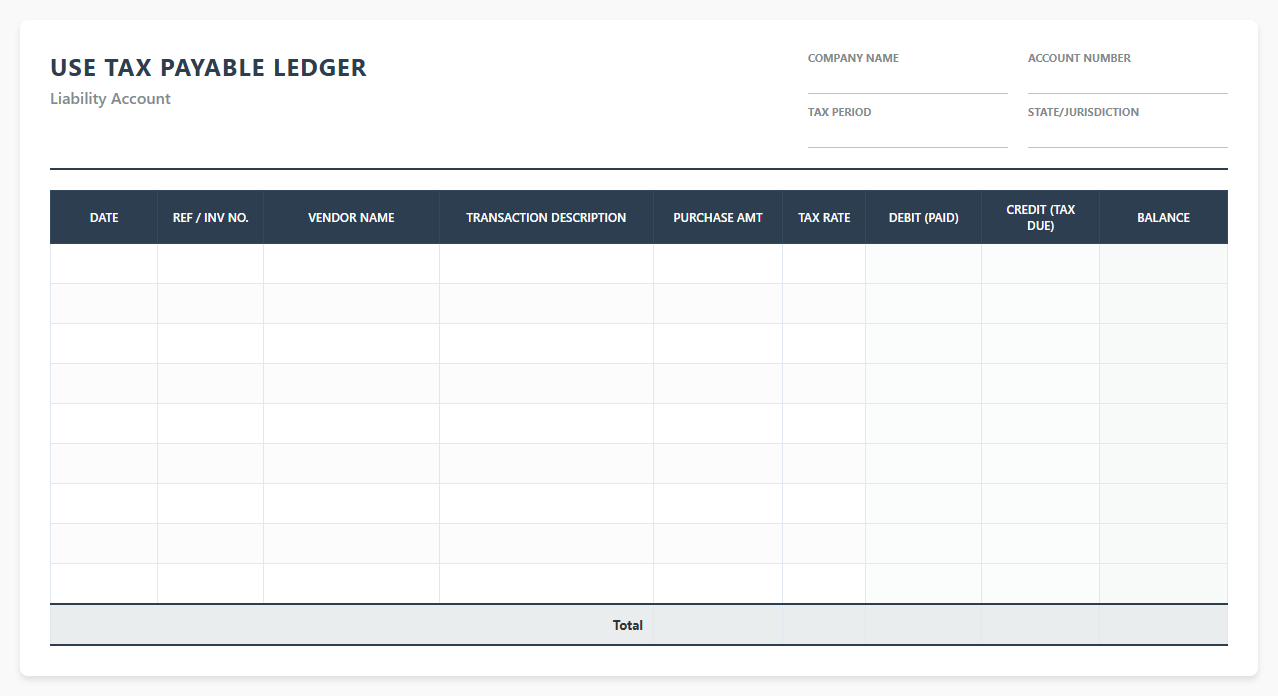 Download: .PDF
Out-of-State Use Tax Liability Ledger
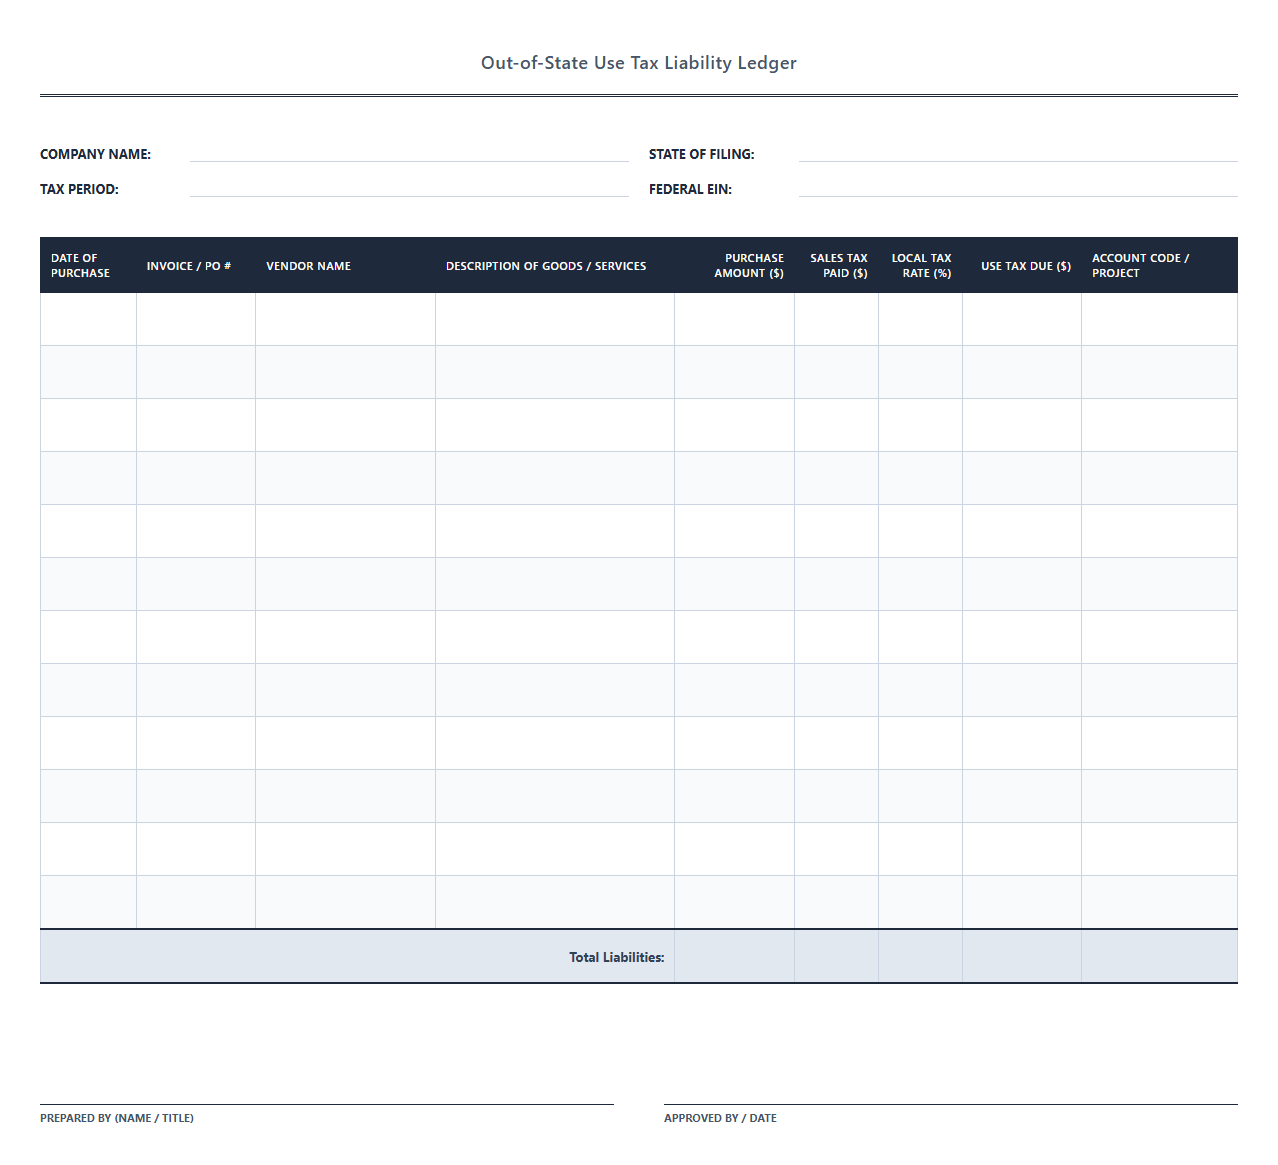 Download: .PDF
Monthly Use Tax Payable Reconciliation Ledger
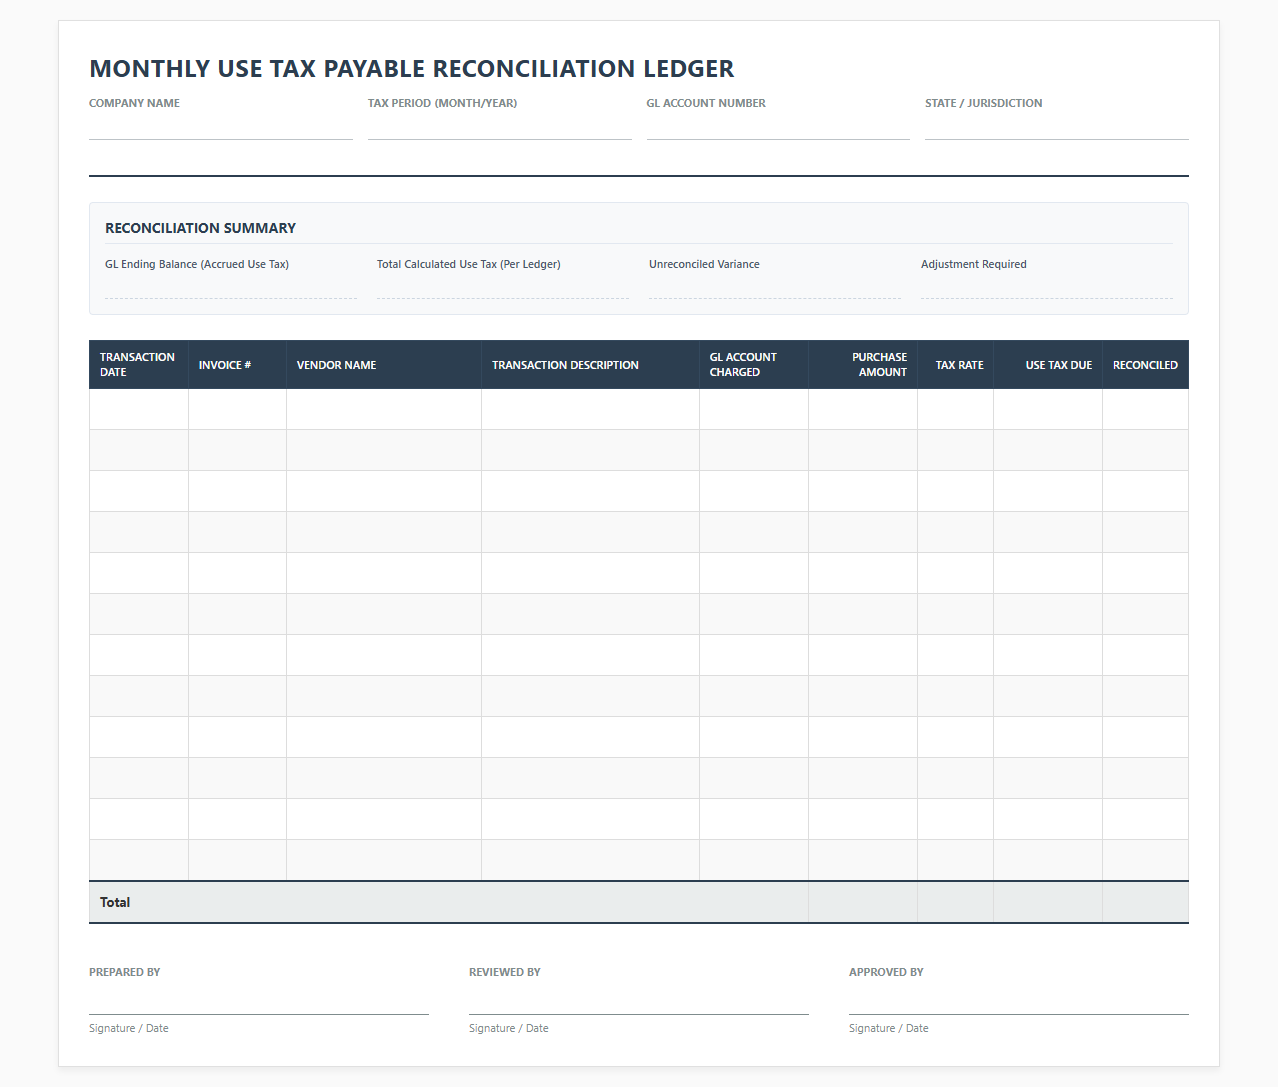 Download: .PDF
Sales and Use Tax Payable General Ledger
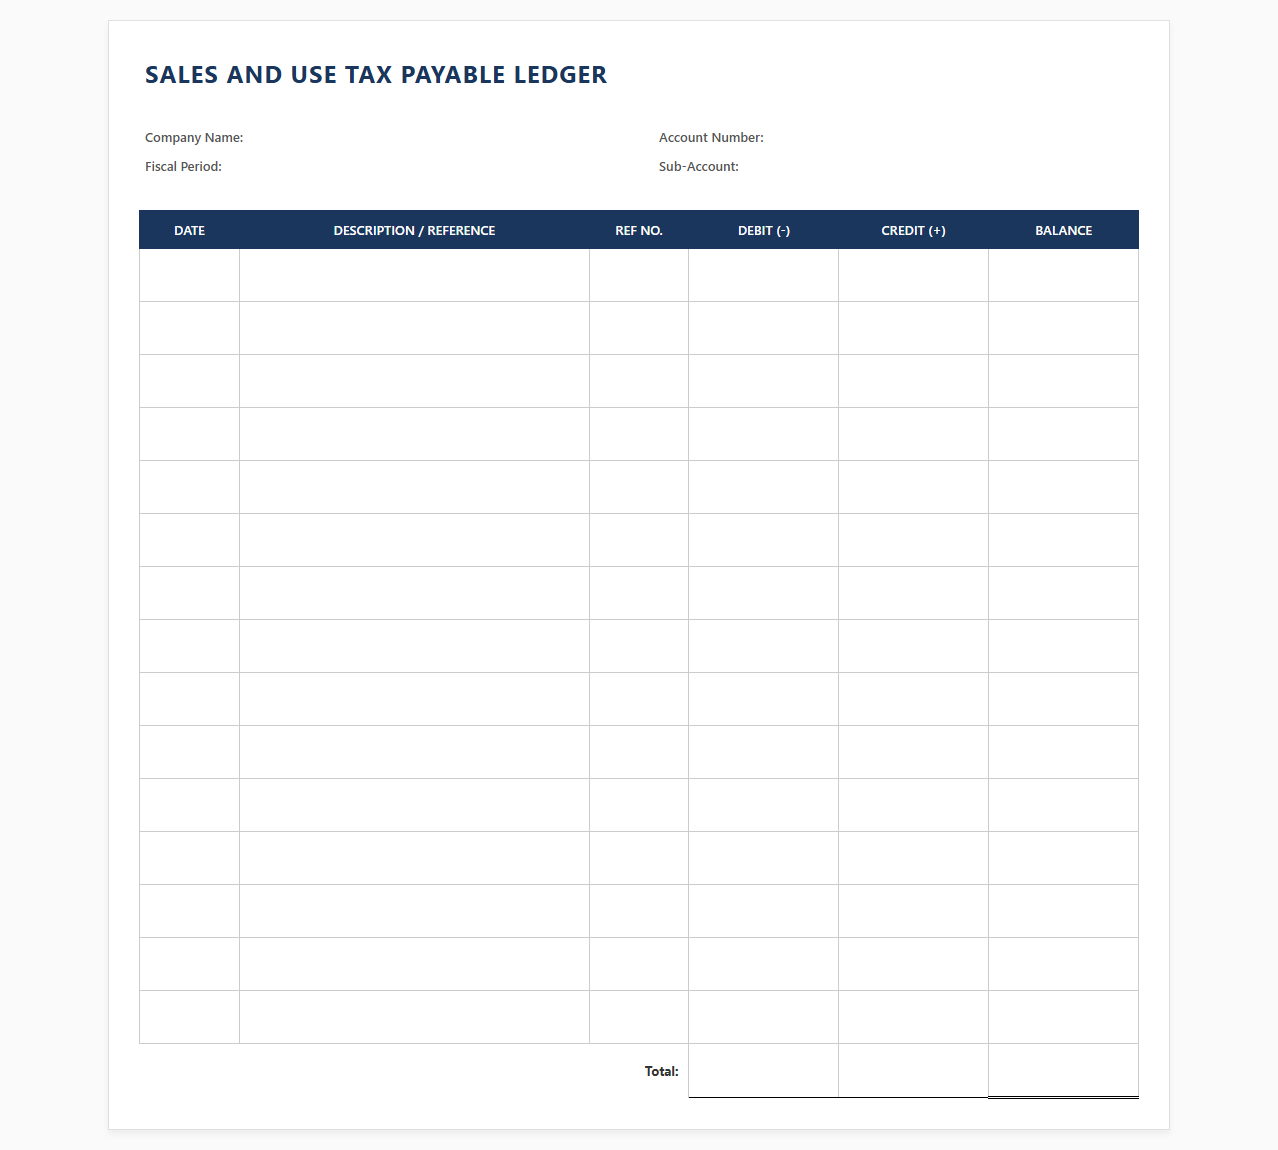 Download: .PDF
Accrued Use Tax Payable Ledger Template
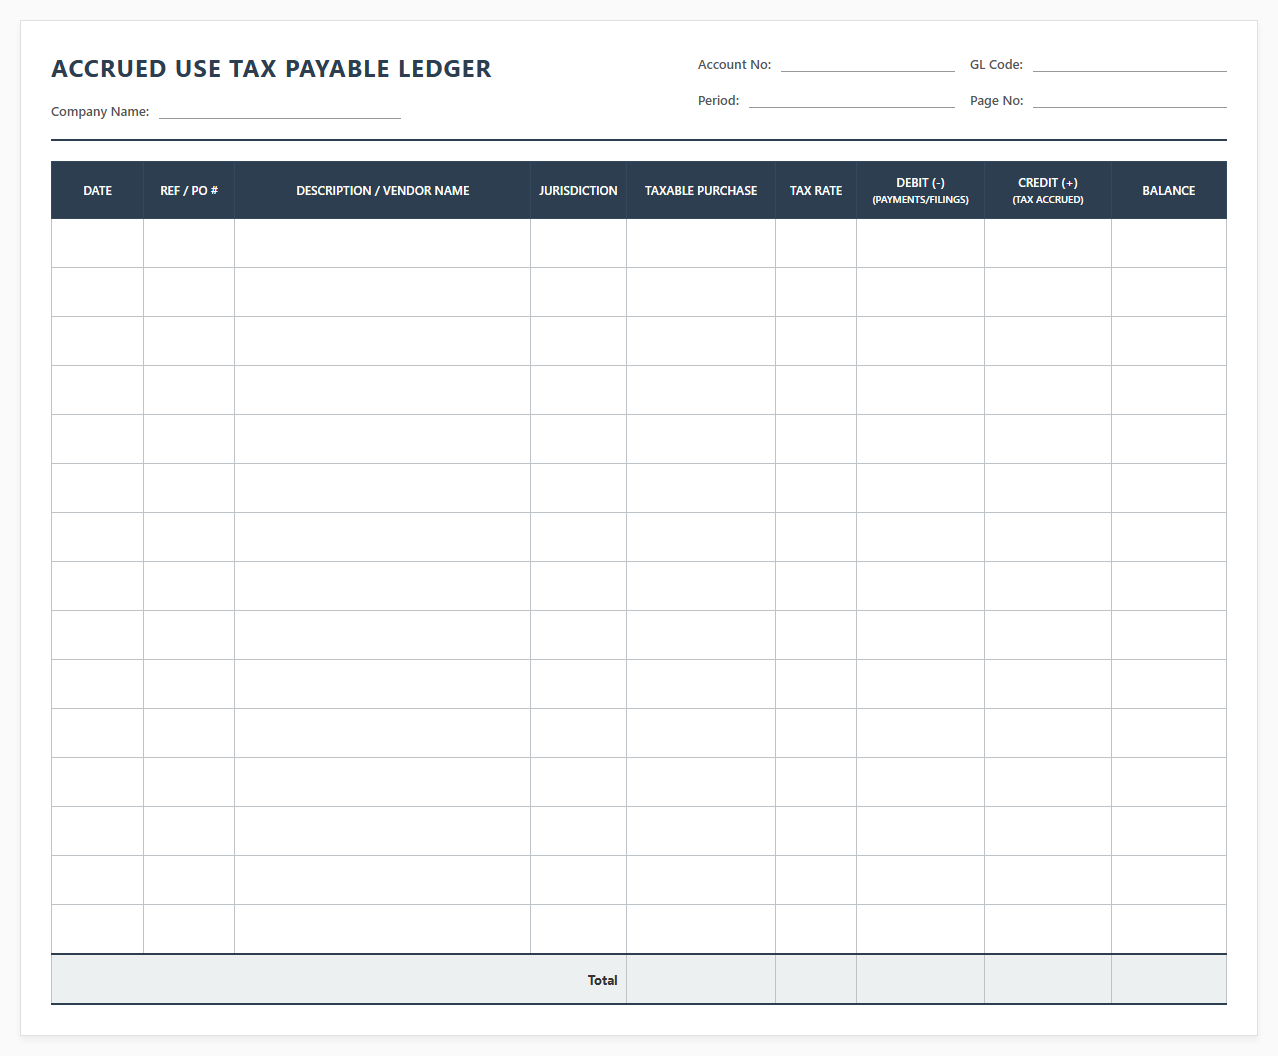 Download: .PDF
Subsidiary Ledger for Use Tax Payable
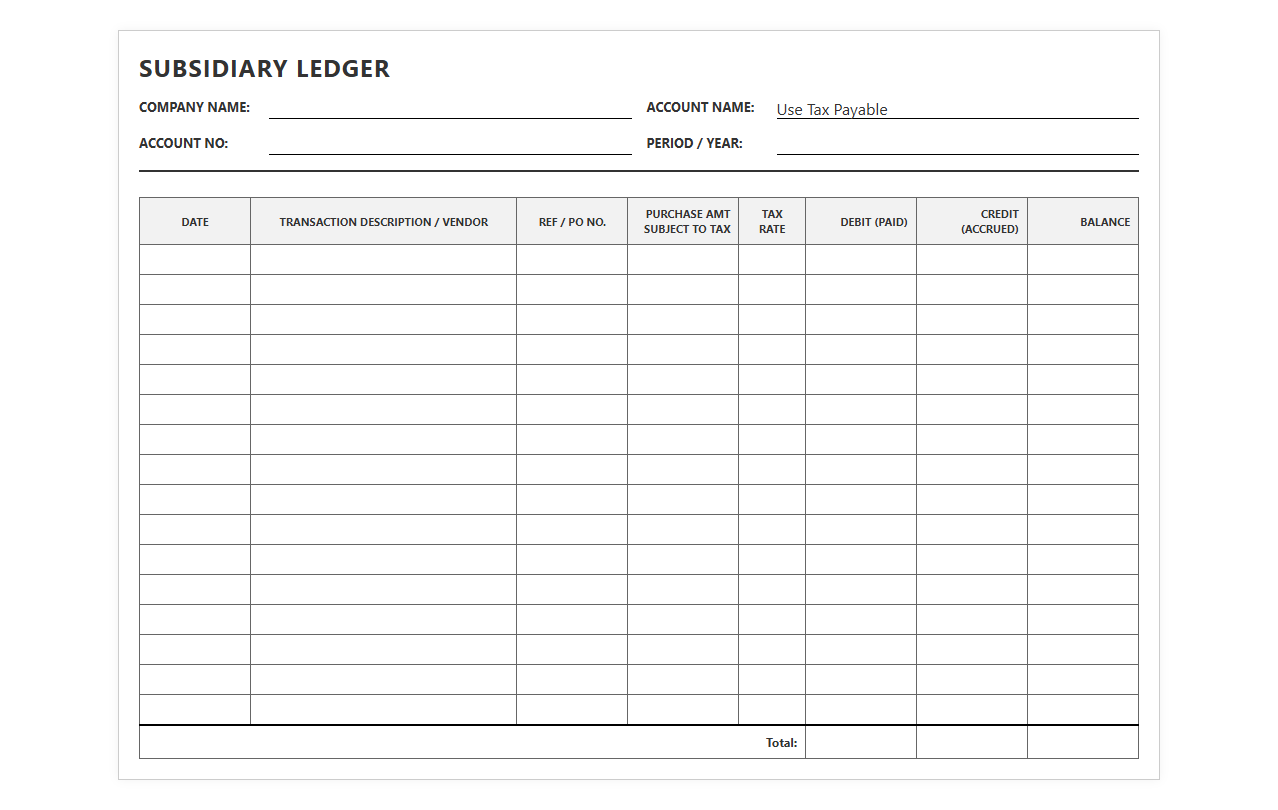 Download: .PDF
Business Use Tax Liability Ledger Sheet
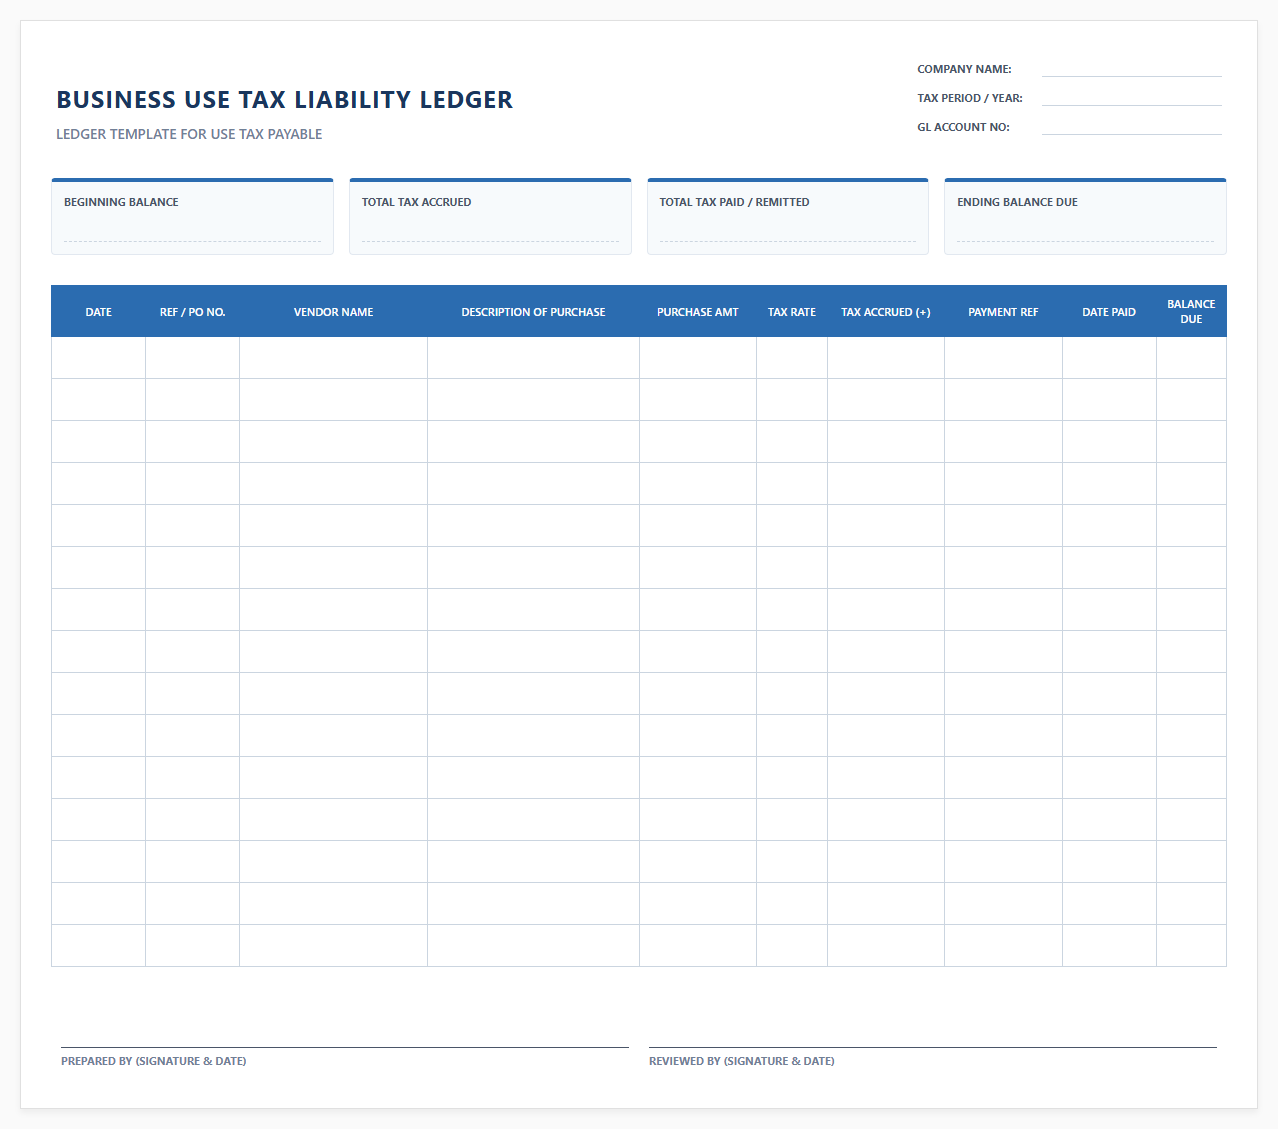 Download: .PDF
Use Tax Payable Account Ledger Worksheet
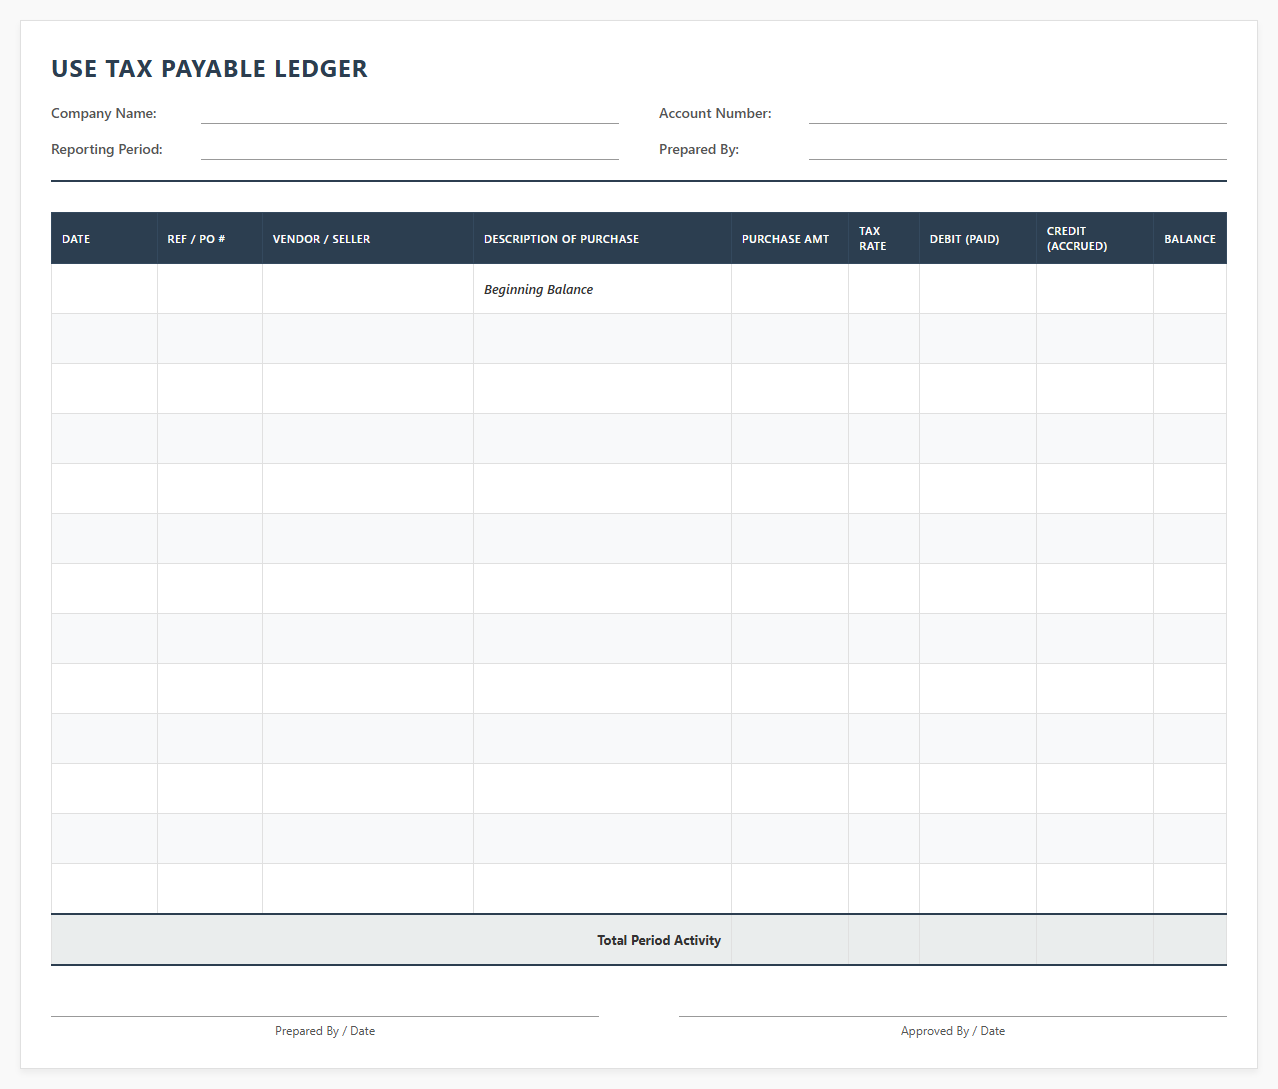 Download: .PDF
Understanding Use Tax Liability and the Need for Standardization
Use tax is a critical but frequently misunderstood component of state taxation. It is typically due on tangible personal property or services purchased for use, storage, or consumption when sales tax was not paid at the time of purchase. For businesses, this creates a significant liability risk because transactions without sales tax-such as out-of-state e-commerce purchases-can easily slip through the cracks of manual accounting processes.
Without a proactive approach, these unpaid taxes accumulate, leaving companies vulnerable to massive back-tax assessments, interest, and penalties. Implementing a rigorous process of standardization acts as a protective shield, ensuring that every purchase is evaluated consistently, reducing compliance errors, and safeguarding the company's financial stability.
The Anatomy of a Standardized Use Tax Payable Ledger
A standardized use tax payable ledger is a dedicated financial document structured to track, calculate, and record untaxed purchases that incur use tax liability. By creating a systematic repository for these transactions, businesses can move away from fragmented spreadsheets and ad-hoc calculations that often lead to costly human errors.
This ledger functions as a single source of truth. When accounting entries are organized under uniform rules, the likelihood of overlooking untaxed transactions decreases dramatically. Consistency in ledger design ensures that tax liabilities are recognized in the correct accounting period, preserving the integrity of the general ledger and financial statements.
Essential Fields to Include in Your Ledger Template
To ensure no critical tax data is missed, a robust use tax ledger template must capture comprehensive details for every transaction. Organizing these details within a structured data framework simplifies reporting and verification.
- Transaction Date
- The date the purchase was completed, which determines the tax period in which the liability must be reported.
- Purchase Price
- The total amount paid for the taxable good or service, serving as the base calculation for the tax due.
- Tax Rate
- The specific state and local tax rate applicable at the jurisdiction where the item is used or consumed.
- Tax Due
- The calculated use tax liability, derived by multiplying the purchase price by the applicable tax rate.
- Assessment Reason
- A brief explanation detailing why use tax is owed, such as out-of-state vendor did not charge sales tax.
How Standardization Minimizes Audit Exposure
State auditors look for inconsistencies, missing documentation, and systemic calculation errors. Standardized record-keeping shows tax authorities that your business maintains a disciplined, repeatable process for assessing and paying use tax, which naturally minimizes your risk profiles during an evaluation.
Standardization transforms the audit process from a chaotic scramble into a routine verification of well-organized records. When data is uniform, auditors can quickly verify compliance without digging deeper into unstructured books.- Tax Compliance Institute Journal
Integrating Ledgers with Existing Accounting Systems
Manual ledger entries are inefficient and prone to transcription errors. Integrating your standardized use tax payable template into existing ERP software and automated accounting workflows maximizes efficiency and accuracy.
To achieve seamless integration, consider the following automation strategies:
- Map tax fields to capture use tax data directly from purchase orders and accounts payable modules.
- Configure automated triggers that flag out-of-state invoices with zero sales tax for review.
- Enable real-time synchronization between the specialized ledger and the main general ledger to keep financial statements up to date.
Actionable Steps for Implementation and Staff Training
Successfully launching a standardized use tax ledger requires clear execution and thorough team alignment. Follow these steps to ensure a smooth transition across your finance departments:
- Define and document standard operating procedures for identifying use tax liabilities.
- Distribute the standardized ledger template and integrate it into daily accounting workflows.
- Conduct comprehensive training sessions focusing on tax determination rules and jurisdiction-specific rates.
- Establish a monthly review process to audit ledger entries for accuracy before tax filing deadlines.
Safeguarding Financial Health Through Proactive Compliance
Maintaining a standardized use tax payable ledger is more than a regulatory chore; it is a vital pillar of sustainable business growth. By proactively tracking liabilities, organizations eliminate the threat of unbudgeted audit penalties and maintain absolute clarity over their cash flow.
Leave a comment