Navigating the complexities of partnership tax reporting often leaves accounting professionals grappling with disproportionate allocations and tedious capital account reconciliations. Before practitioners can accurately report these figures on Schedule K-1, they must first bridge the gap between the partnership agreement's economic arrangements and the stringent requirements of IRS Section 704(b).
Mastering this alignment grants firms unparalleled reporting accuracy and minimizes costly compliance risks. However, it is important to stipulate that while standardized templates streamline this process, they must be carefully calibrated to account for varying partner debt-sharing ratios and substantial economic effect rules. For example, utilizing targeted templates for Section 704(c) built-in gain allocations or qualified income offsets ensures that complex transactions are accurately reflected.
Below, we examine the essential return templates required for distributive share reporting, break down key allocation mechanics, and outline best practices for flawless filing execution.
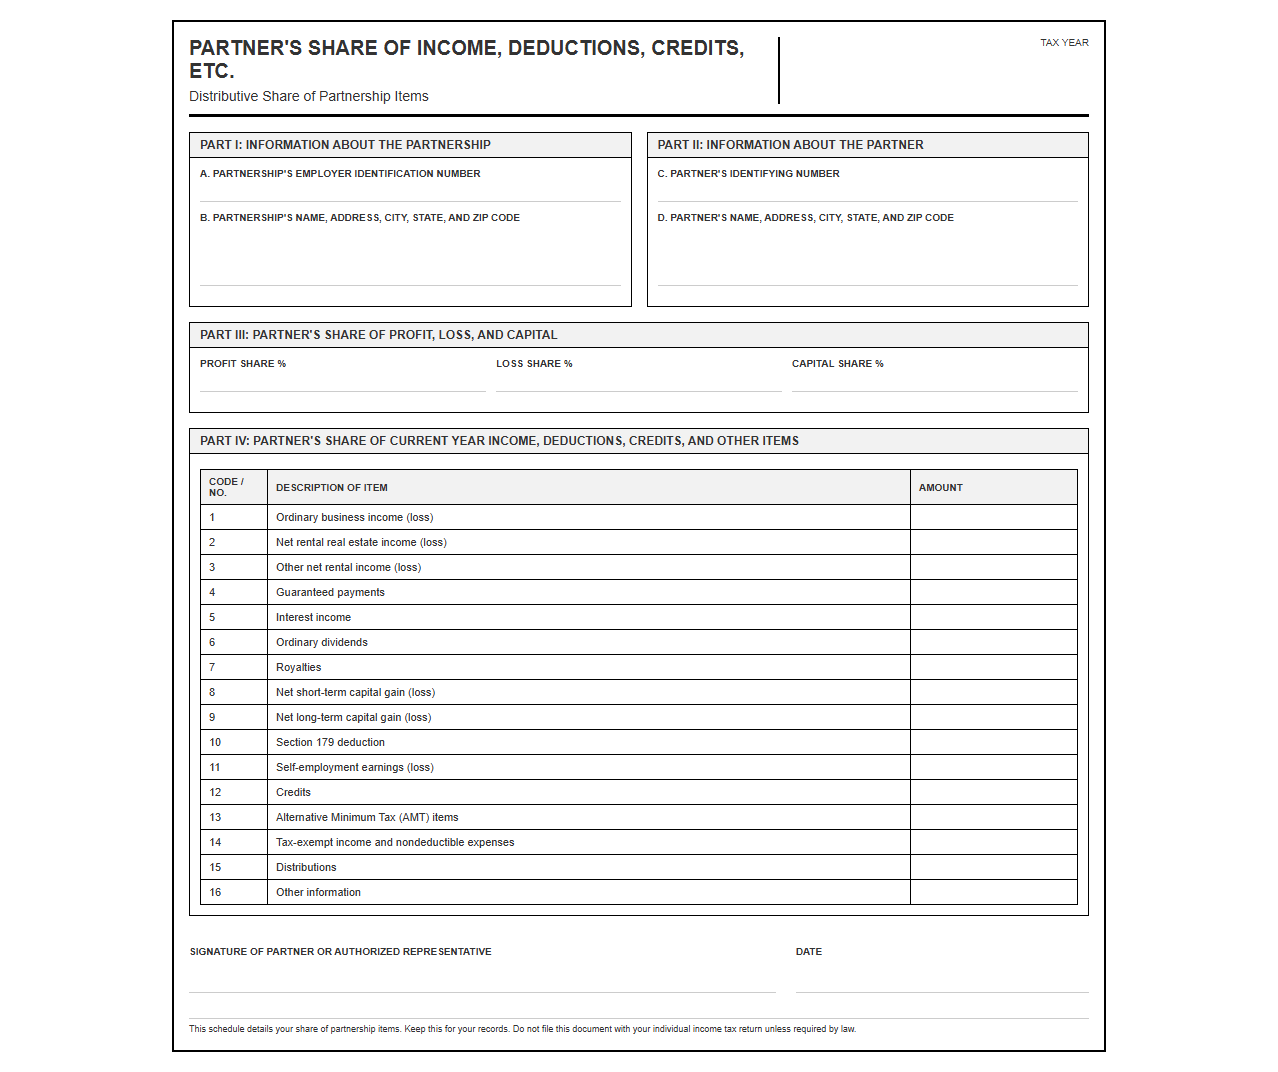
Partnership Distributive Share Return Template
 Download: .PDF
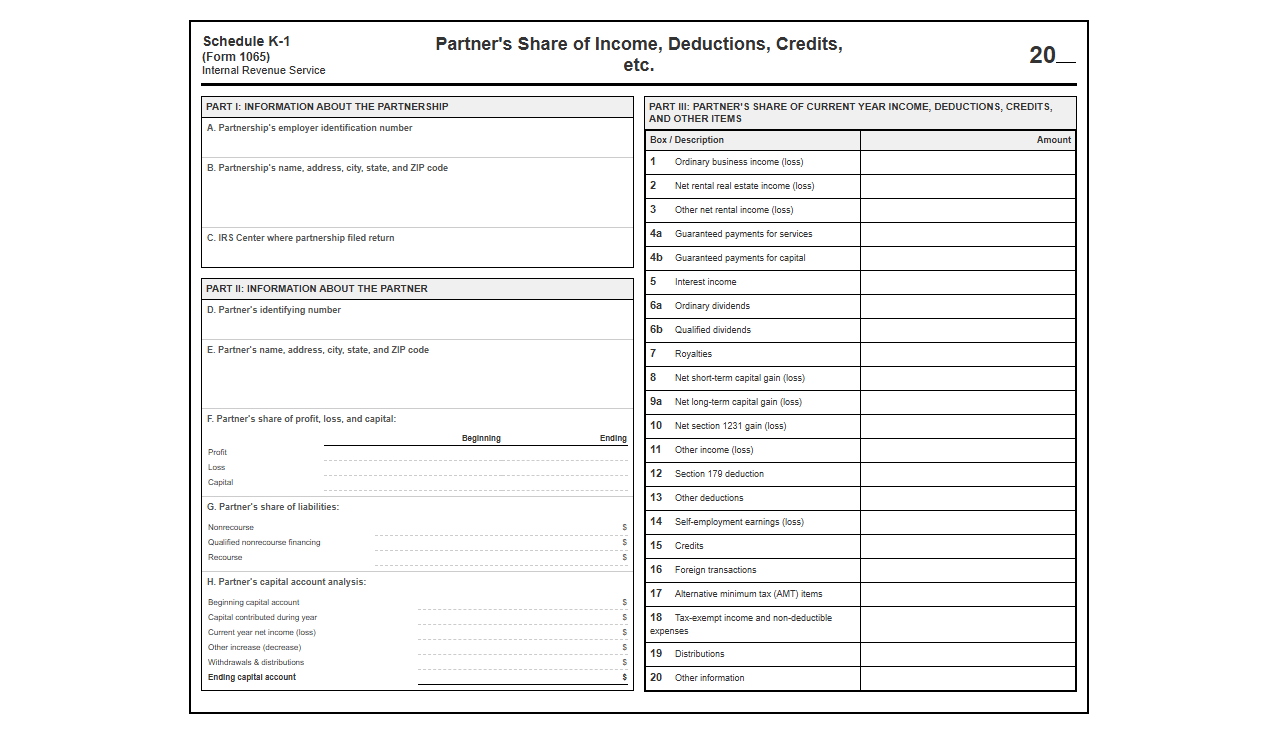
Schedule K-1 Distributive Share Reporting Template
 Download: .PDF
Partnership Income and Distributive Share Return Form
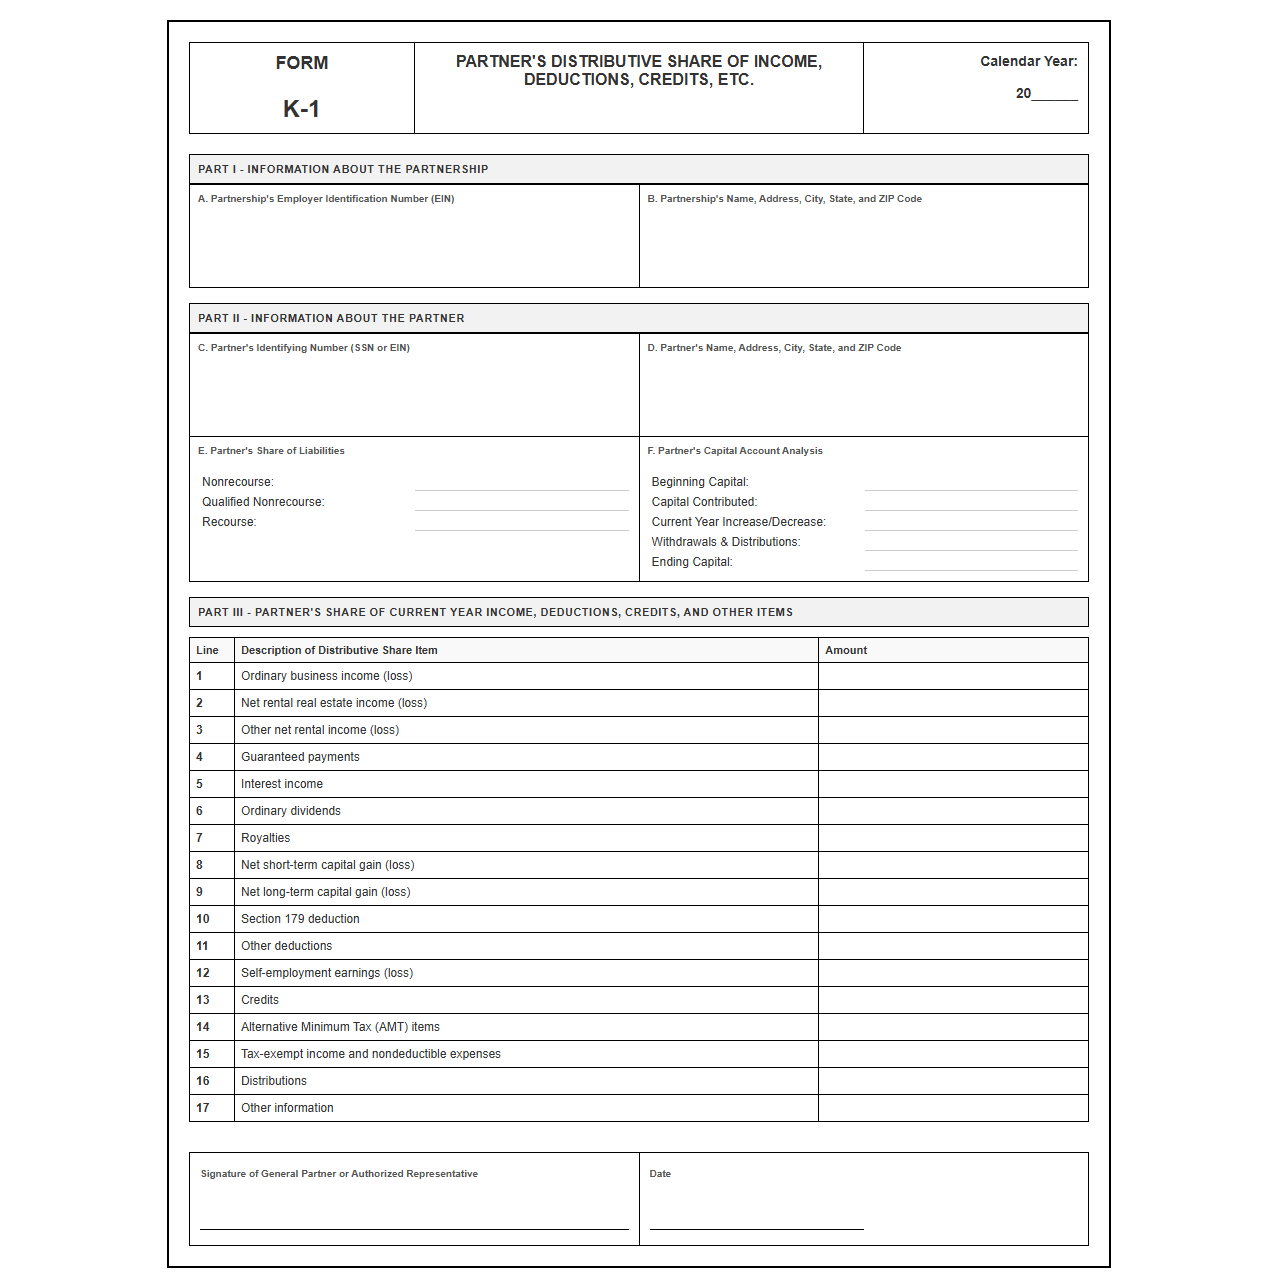 Download: .PDF
Distributive Share of Partnership Income Declaration Template
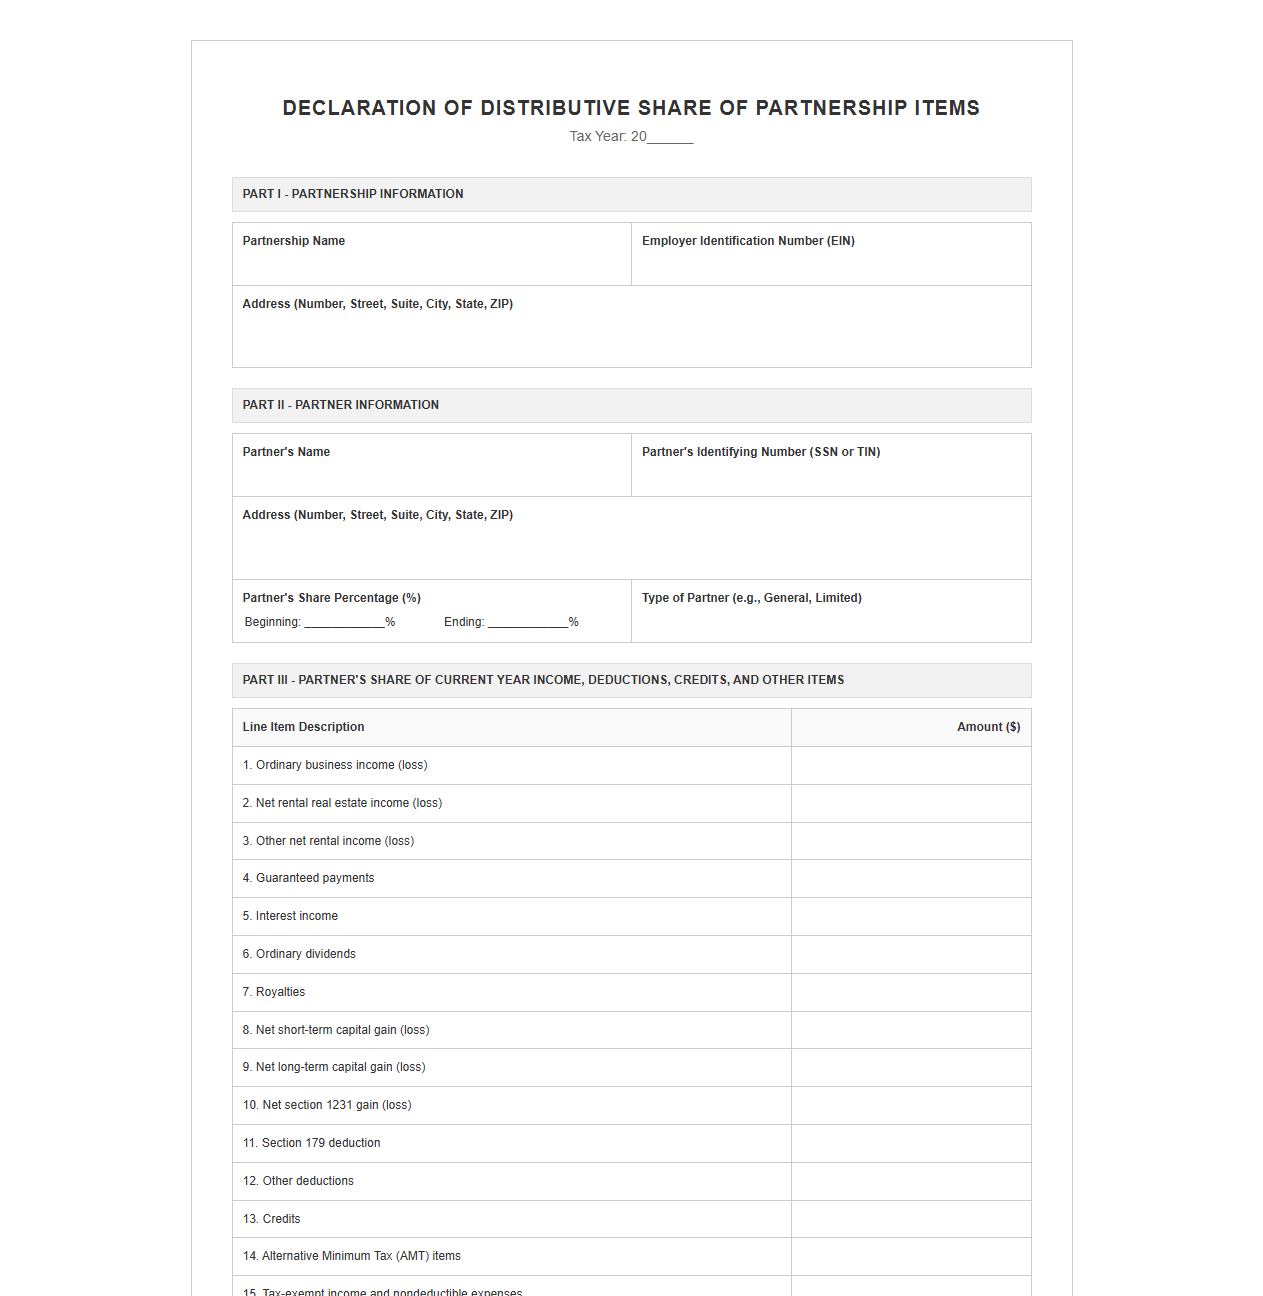 Download: .PDF
Partner Distributive Share Allocation Return Worksheet
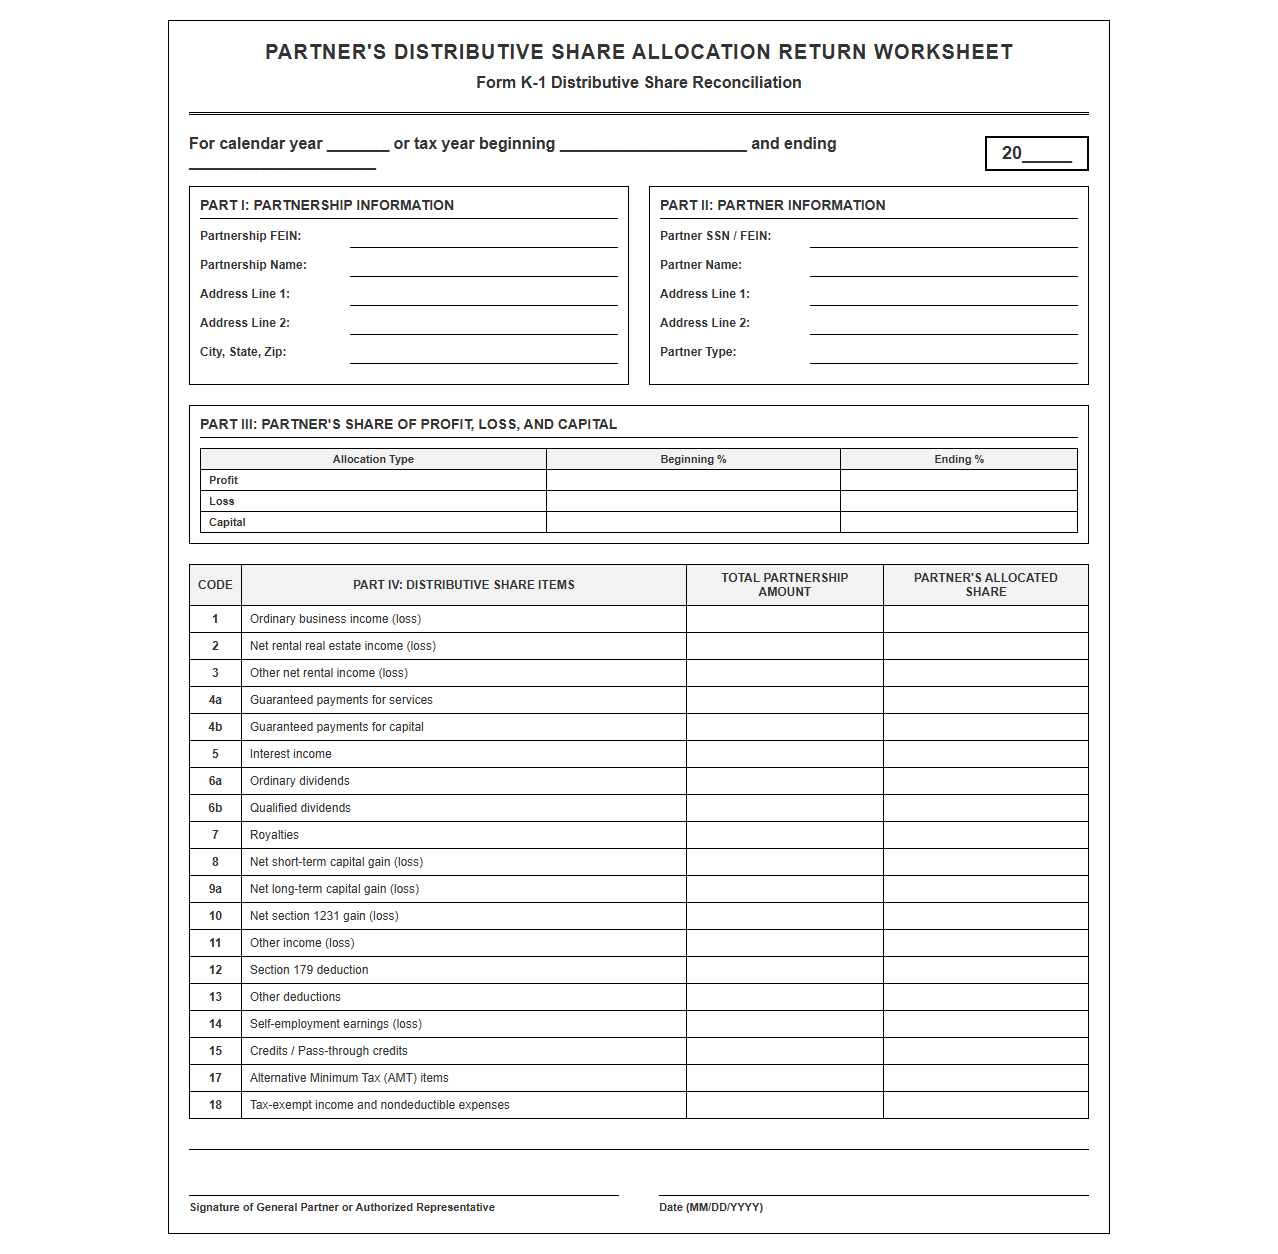 Download: .PDF
Partnership Tax Return Distributive Share Template
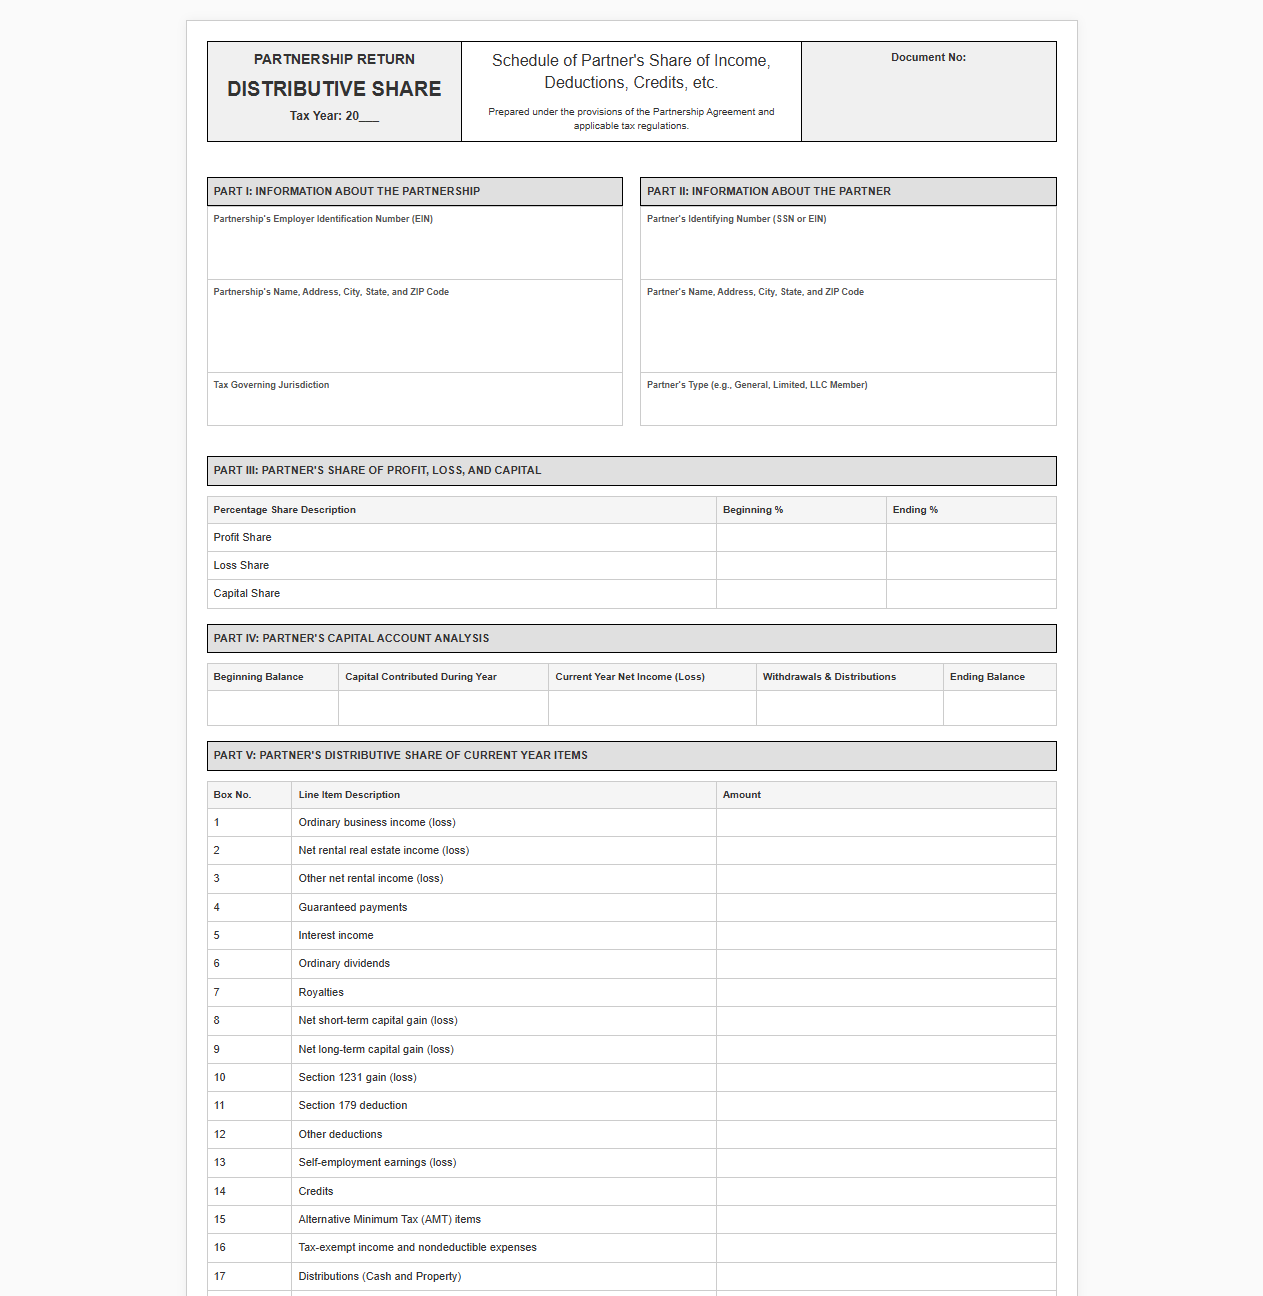 Download: .PDF
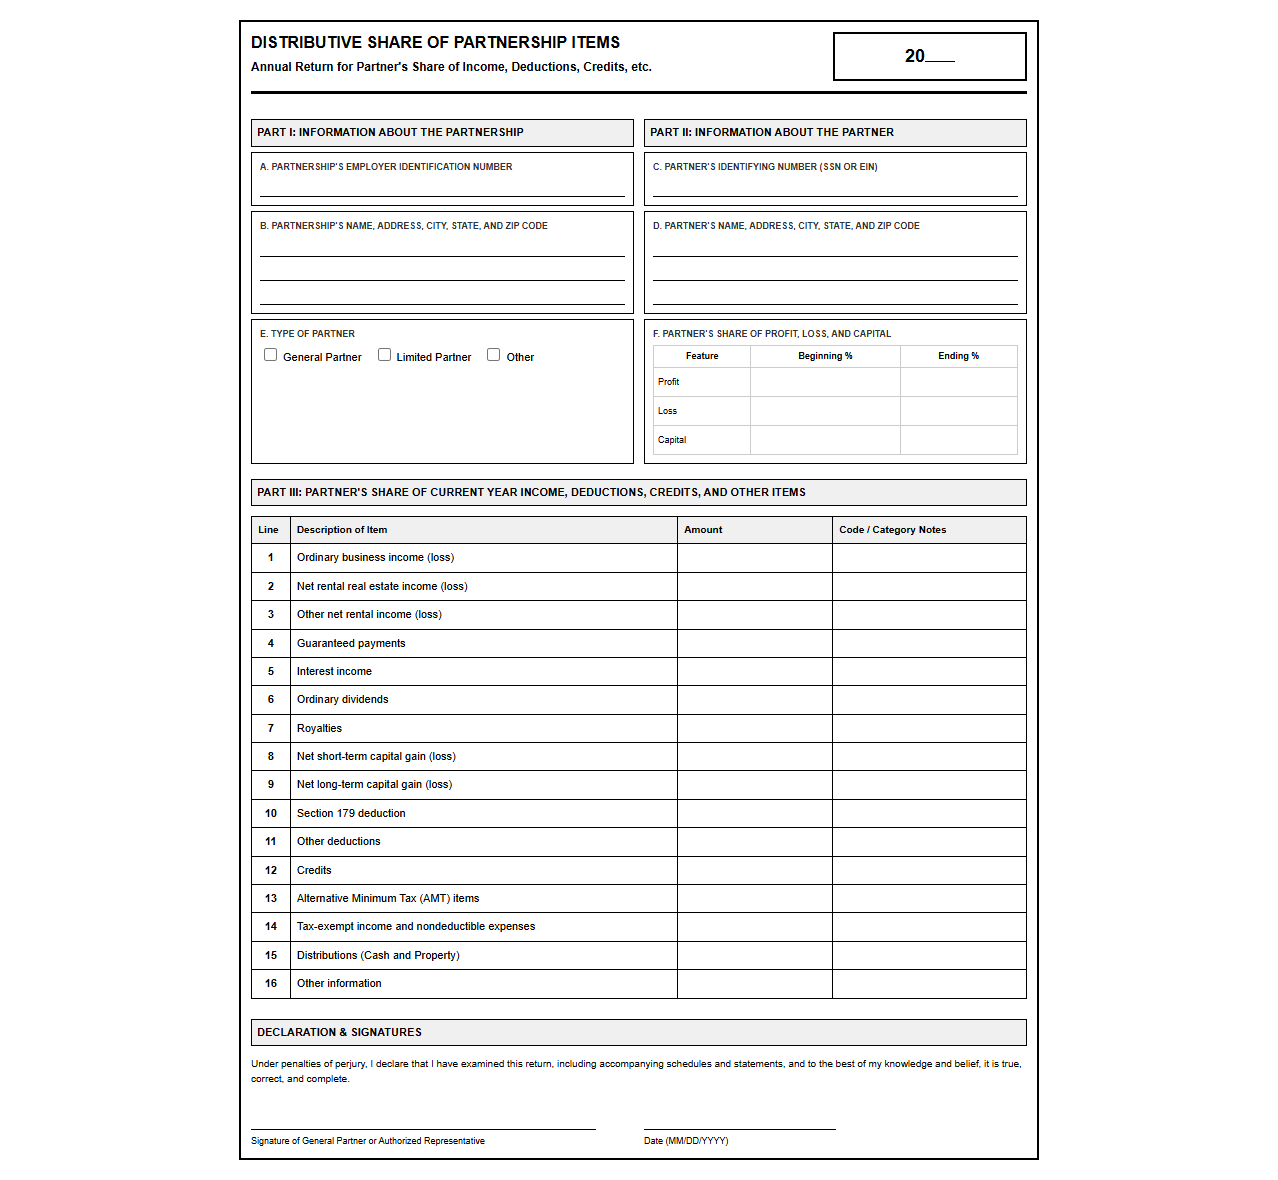
Annual Distributive Share of Partnership Items Return
 Download: .PDF
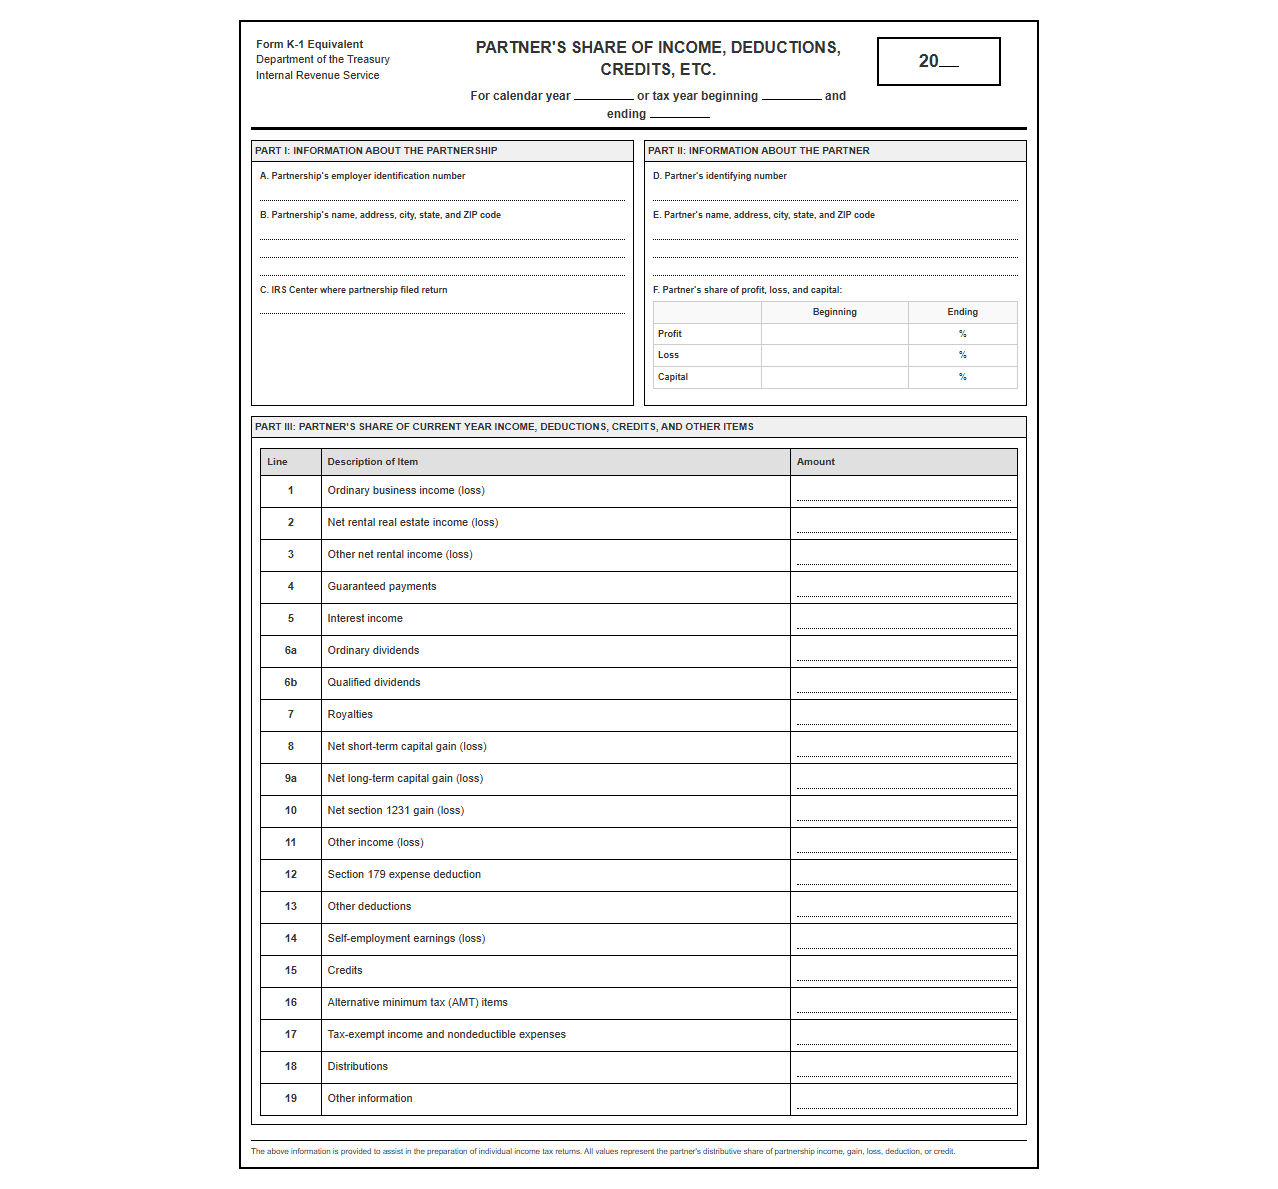
Partner Share of Partnership Income Return Template
 Download: .PDF
Demystifying Partnership Allocations and Distributive Shares
Partnerships offer immense flexibility, but with that flexibility comes complexity. A partnership's distributive share refers to each partner's share of income, gain, loss, deduction, or credit, as outlined in the partnership agreement. Ensuring correct allocation is not just a matter of internal accounting; it is a critical component of federal tax compliance. Incorrect reporting can quickly trigger IRS audits and lead to costly penalties. To mitigate these risks, tax professionals rely on structured templates that simplify the reporting process, automate calculations, and maintain consistency across tax filings.
Navigating Section 704(b): The Substantial Economic Effect Standard
To ensure tax allocations reflect actual financial arrangements, IRS Section 704(b) requires allocations to have "substantial economic effect." If an allocation fails this test, the IRS will reallocate the tax items based on the partner's interest in the partnership (PIP). To maintain compliance, the partnership must carefully manage partner capital accounts under specific rules:
- Capital accounts must be increased by the partner's cash contributions and the fair market value of any contributed property.
- Capital accounts must be decreased by distributions of cash and the fair market value of distributed property.
- Allocations must align with the economic benefits or burdens received by the partners, typically tracked using
capital accountsand simulated liquidations.
Essential Data Points for Schedule K-1 Distributive Share Reporting
Schedule K-1 (Form 1065) is the primary instrument used to report each partner's share of income, credits, and deductions. Accurate data entry in specific boxes is vital for matching partner-level tax returns with the partnership's master return. Key reporting fields include:
- Ordinary Business Income (Loss) (Box 1): This reflects the operational profits or losses of the partnership's core business activities.
- Net Rental Real Estate Income (Loss) (Box 2): Used to report passive income or losses generated from rental real estate holdings.
- Guaranteed Payments (Box 4): These are payments made to partners for services rendered or capital provided, determined without regard to partnership income.
Managing Basis Adjustments: Section 754 Elections and Section 743(b) / 734(b)
When a partner purchases an interest from an existing partner or receives a distribution of property, mismatch errors between inside and outside basis can arise. A Section 754 election allows partnerships to resolve this mismatch by adjusting the inside basis of partnership assets. These adjustments prevent double taxation and ensure that new partners do not inherit prior appreciation or depreciation.
Under Section 743(b), the partnership adjusts the basis of partnership property solely for the benefit of the transferee partner, matching their outside cost basis. Under Section 734(b), basis adjustments are made to the remaining partnership property following certain distributions of cash or property to a partner.
Template 1: Standard Pro-Rata Distributive Share Allocation Model
The pro-rata model is the most straightforward method of allocating profits and losses. Allocations are based directly on the fixed ownership percentages defined in the partnership agreement.
| Partner Name | Ownership % | Total Income ($) | Allocated Income ($) |
|---|---|---|---|
| Partner A | 60% | $100,000 | $60,000 |
| Partner B | 40% | $100,000 | $40,000 |
Template 2: Targeted Capital Account Allocation Model
Unlike pro-rata models, the targeted allocation method determines taxable income or loss allocations based on what the partners would receive upon a hypothetical cash liquidation at the end of the year.
| Partner Name | Targeted Capital Balance ($) | Beginning Capital ($) | Allocated Income/Loss ($) |
|---|---|---|---|
| Partner A | $150,000 | $100,000 | $50,000 |
| Partner B | $75,000 | $50,000 | $25,000 |
Best Practices and Compliance Checklist for Distributive Share Reporting
To maintain compliance and survive IRS scrutiny, tax preparers must adopt systematic workflows. Adhering to a robust checklist ensures all allocations reflect both tax law and the economic realities of the partnership agreement.
- Review the partnership agreement annually for any amendments to profit, loss, or distribution clauses.
- Verify that capital accounts are maintained in strict accordance with the Section 704(b) regulations.
- Reconcile Schedule M-2 (Analysis of Partners' Capital Accounts) with individual K-1 ending balances.
- Confirm that any Section 754 adjustments are accurately calculated and reported on relevant schedules.
Leave a comment