Reconciling liability accounts often feels like chasing moving targets, leaving accounting teams buried under unexplained balance discrepancies during critical month-end closes. Before addressing these errors, organizations must recognize how decentralized reporting structures and manual tracking compound reconciliation delays. Implementing standardized statement templates grants teams immediate operational clarity, reducing investigation times from days to minutes.
However, as a crucial stipulation, these templates are not self-correcting mechanisms; they rely entirely on the accuracy of baseline ledger entries. For instance, resolving recurring mismatches in accrued payroll liabilities or complex loan amortization schedules requires structured, uniform inputs to be effective. In this guide, we will examine the root causes of liability discrepancies, introduce robust template frameworks, and outline a step-by-step methodology to ensure your balance sheet remains audit-ready.
Liability Account Balance Statement Template
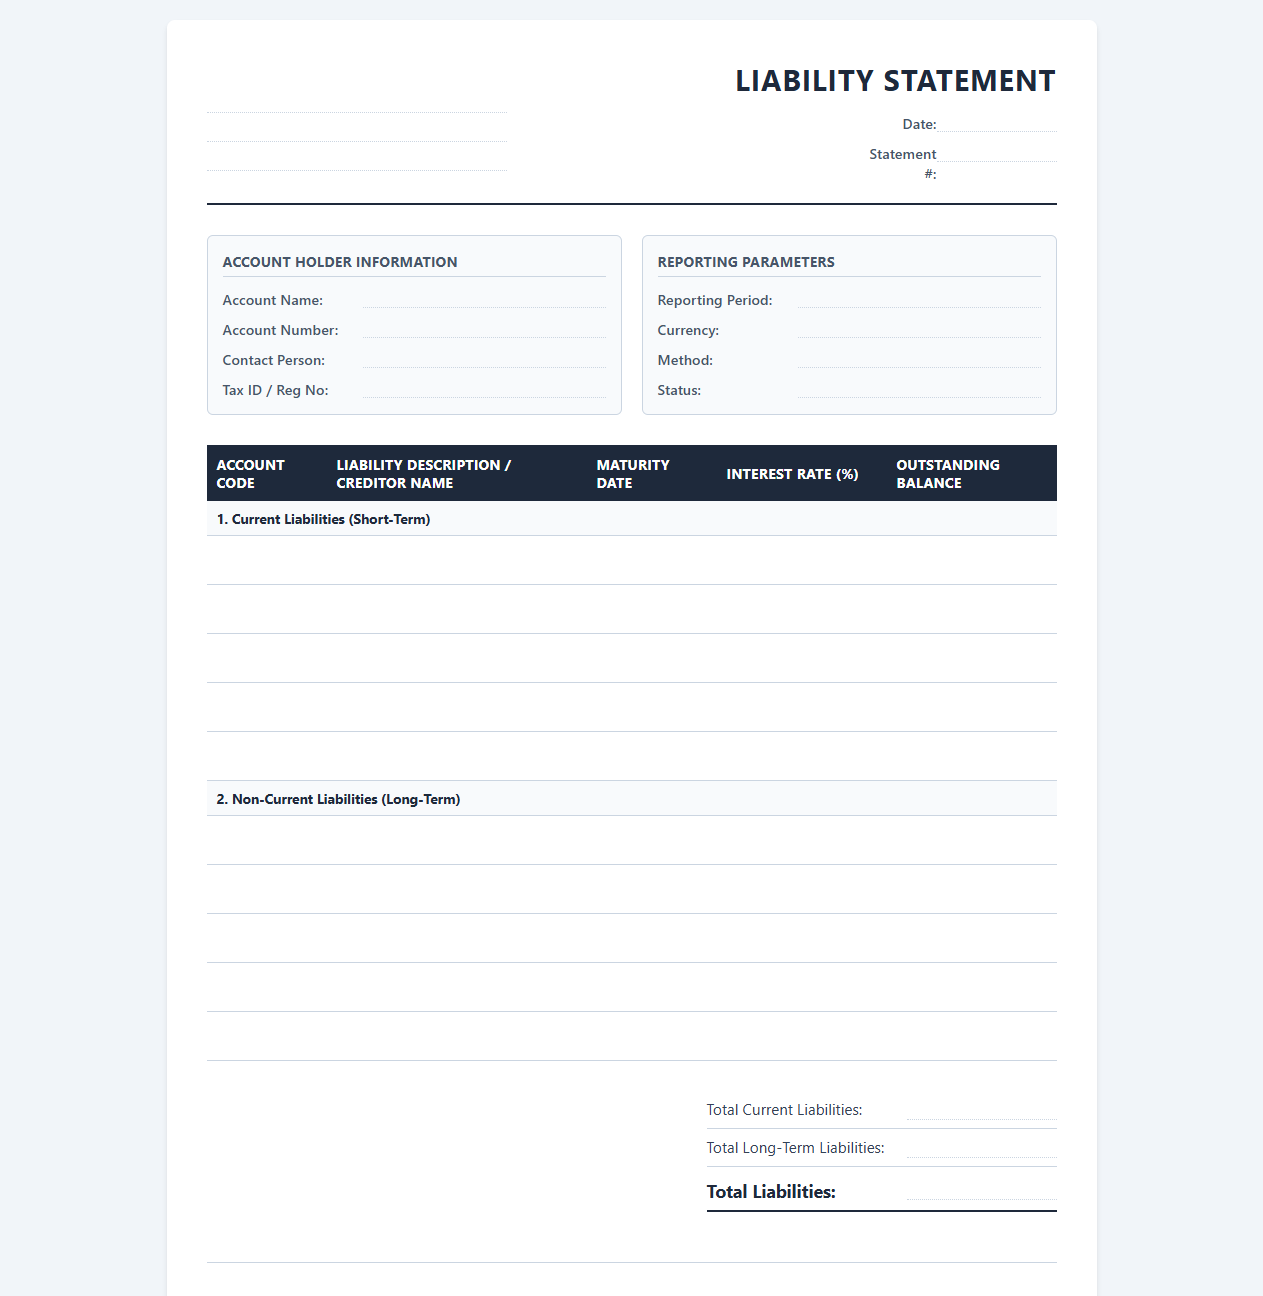 Download: .PDF
Outstanding Debt and Liability Statement Template
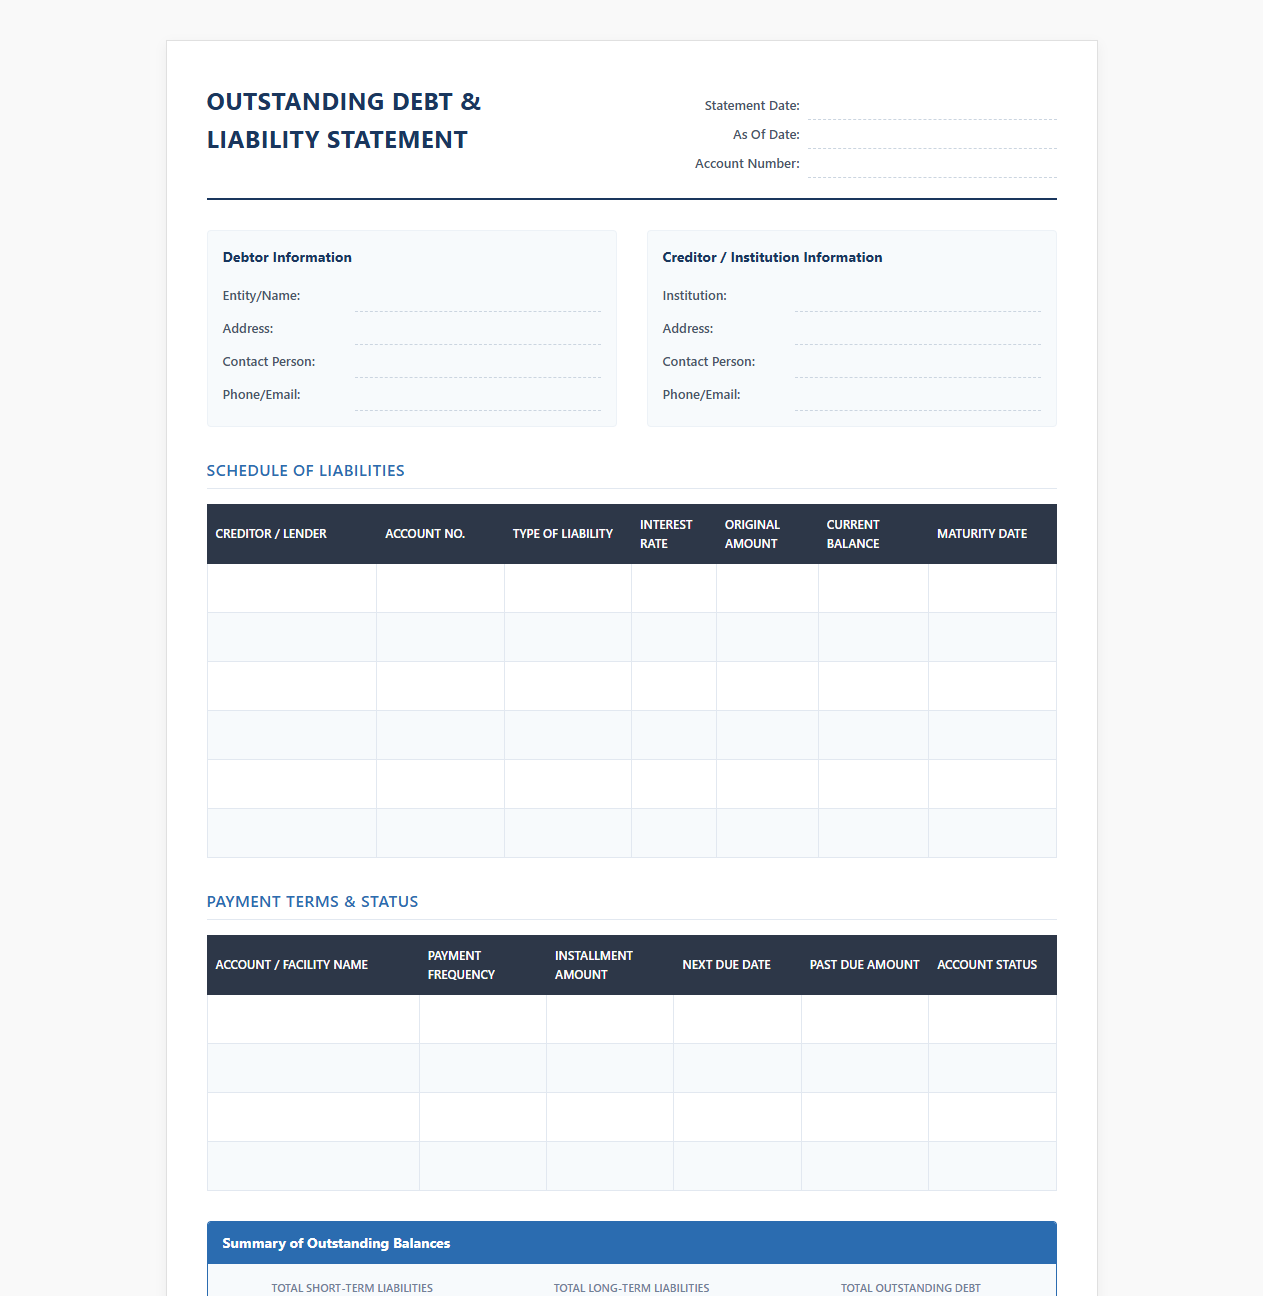 Download: .PDF
Monthly Liability Account Reconciliation Template
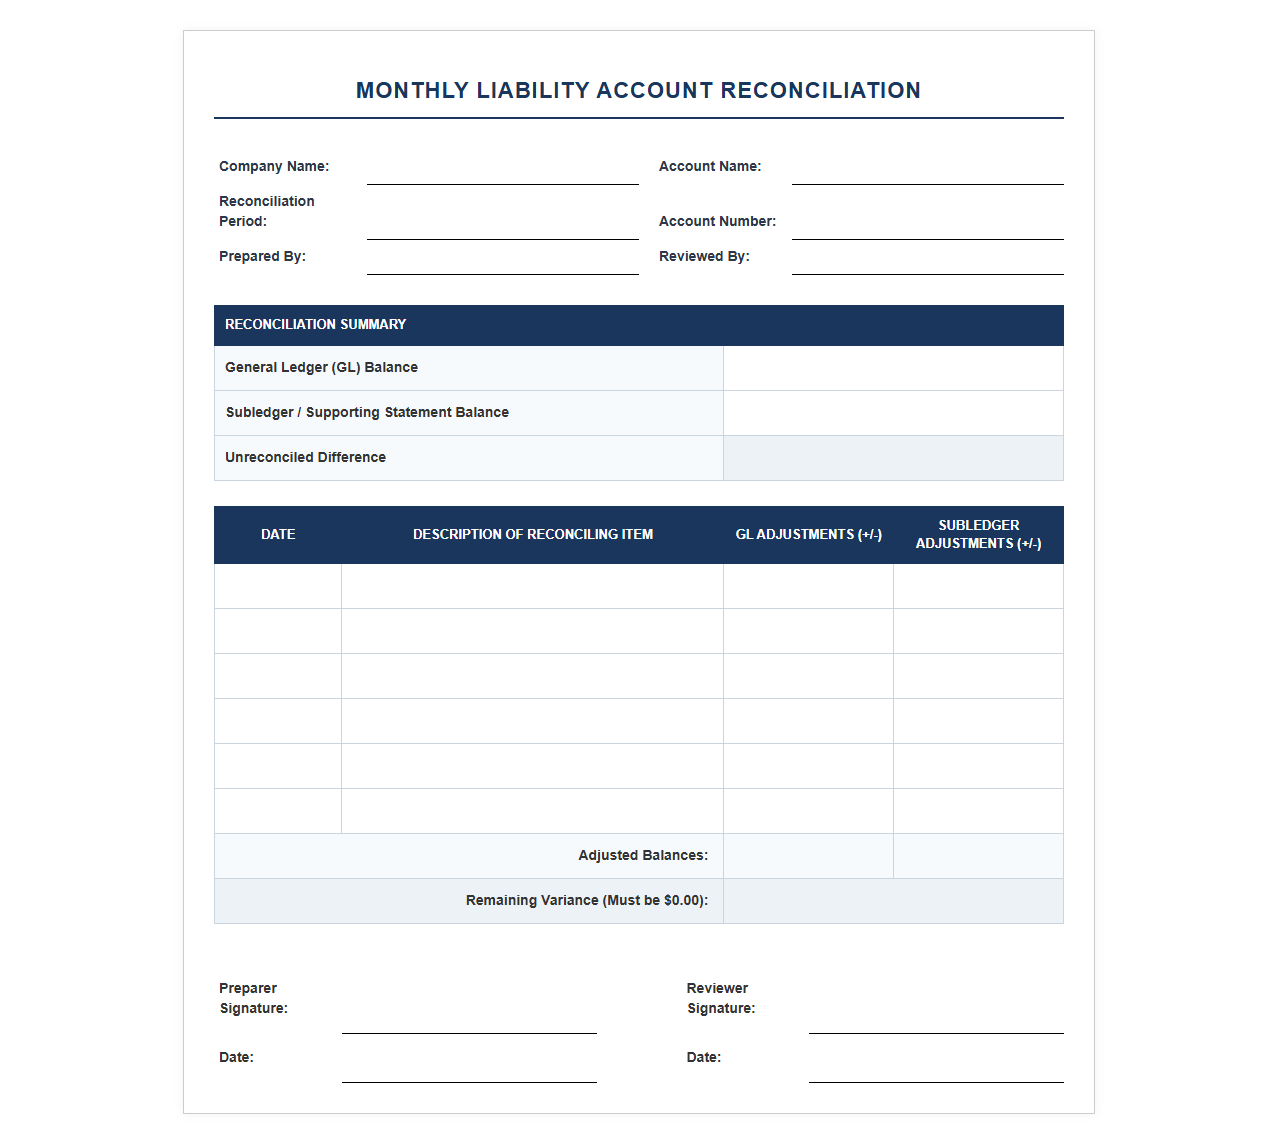 Download: .PDF
Current and Long Term Liabilities Statement Template
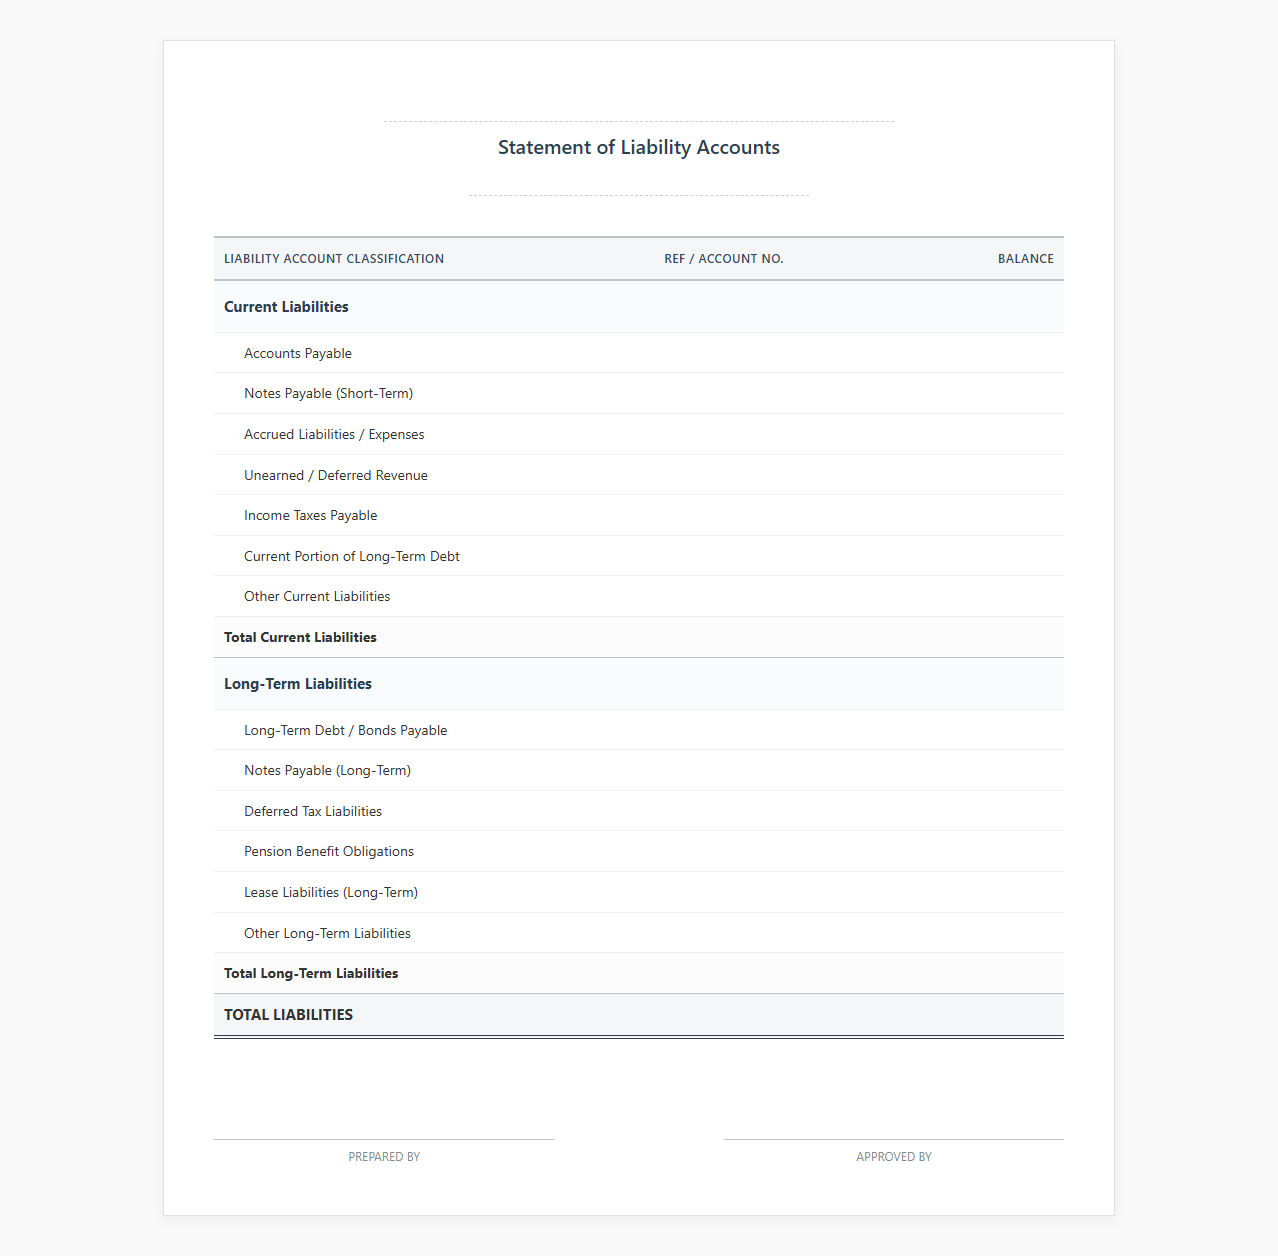 Download: .PDF
Corporate Liability Account Summary Template
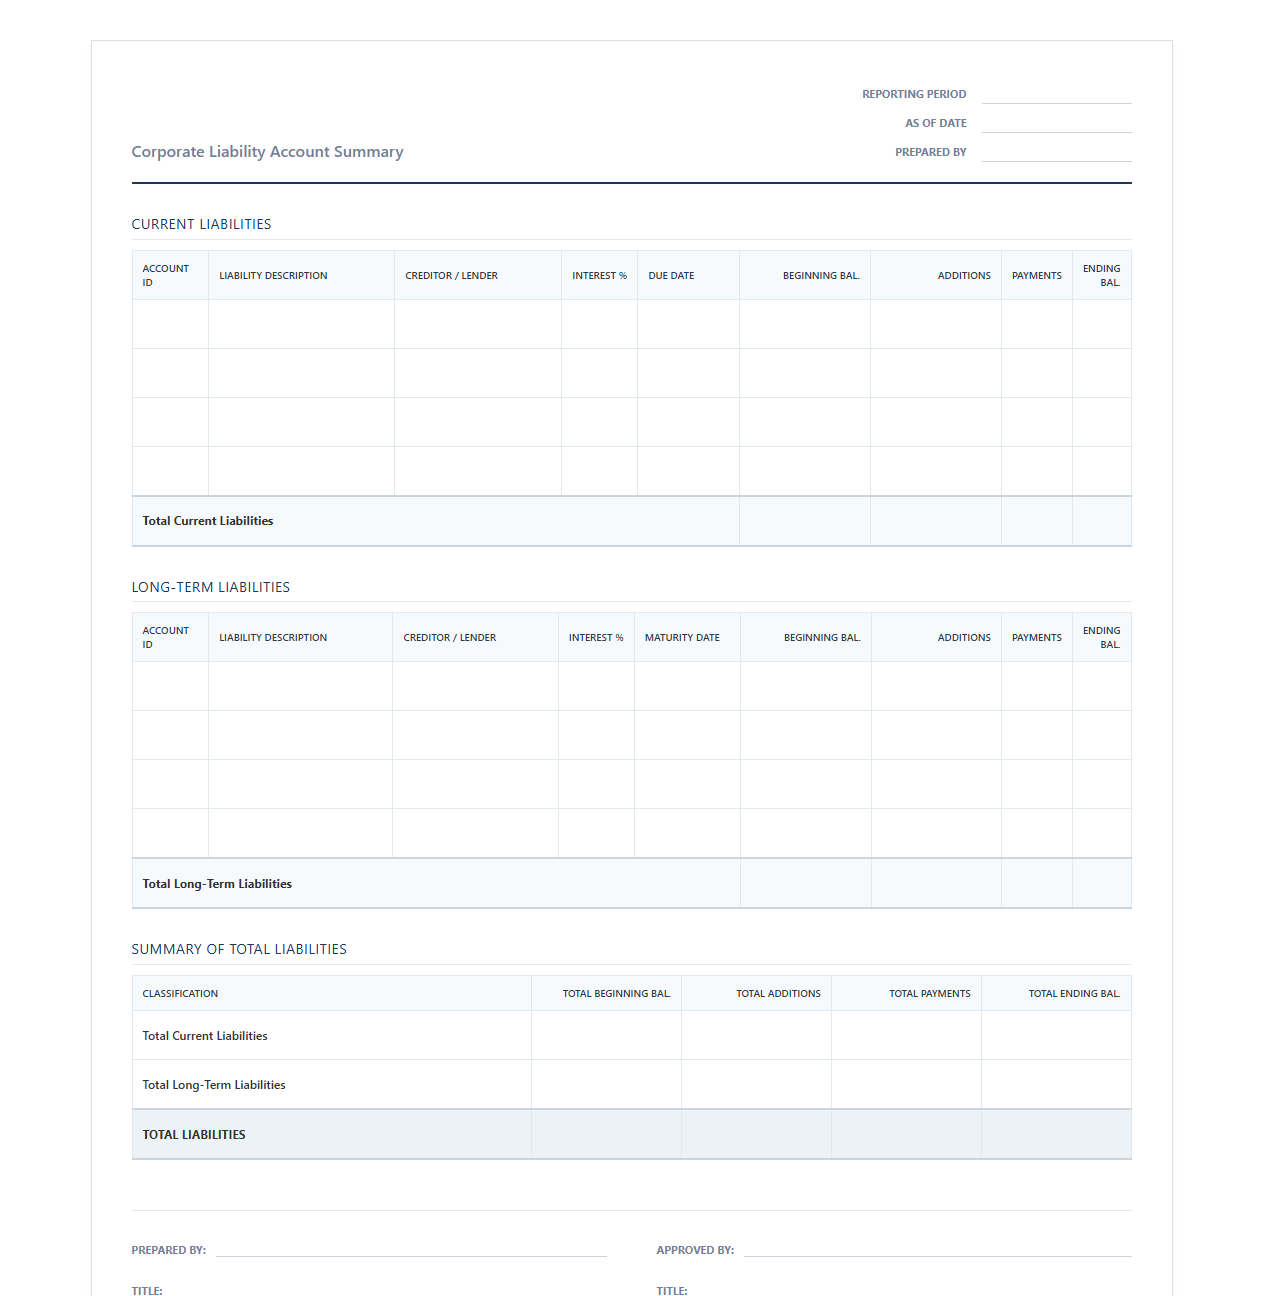 Download: .PDF
Liability Ledger Activity Statement Template
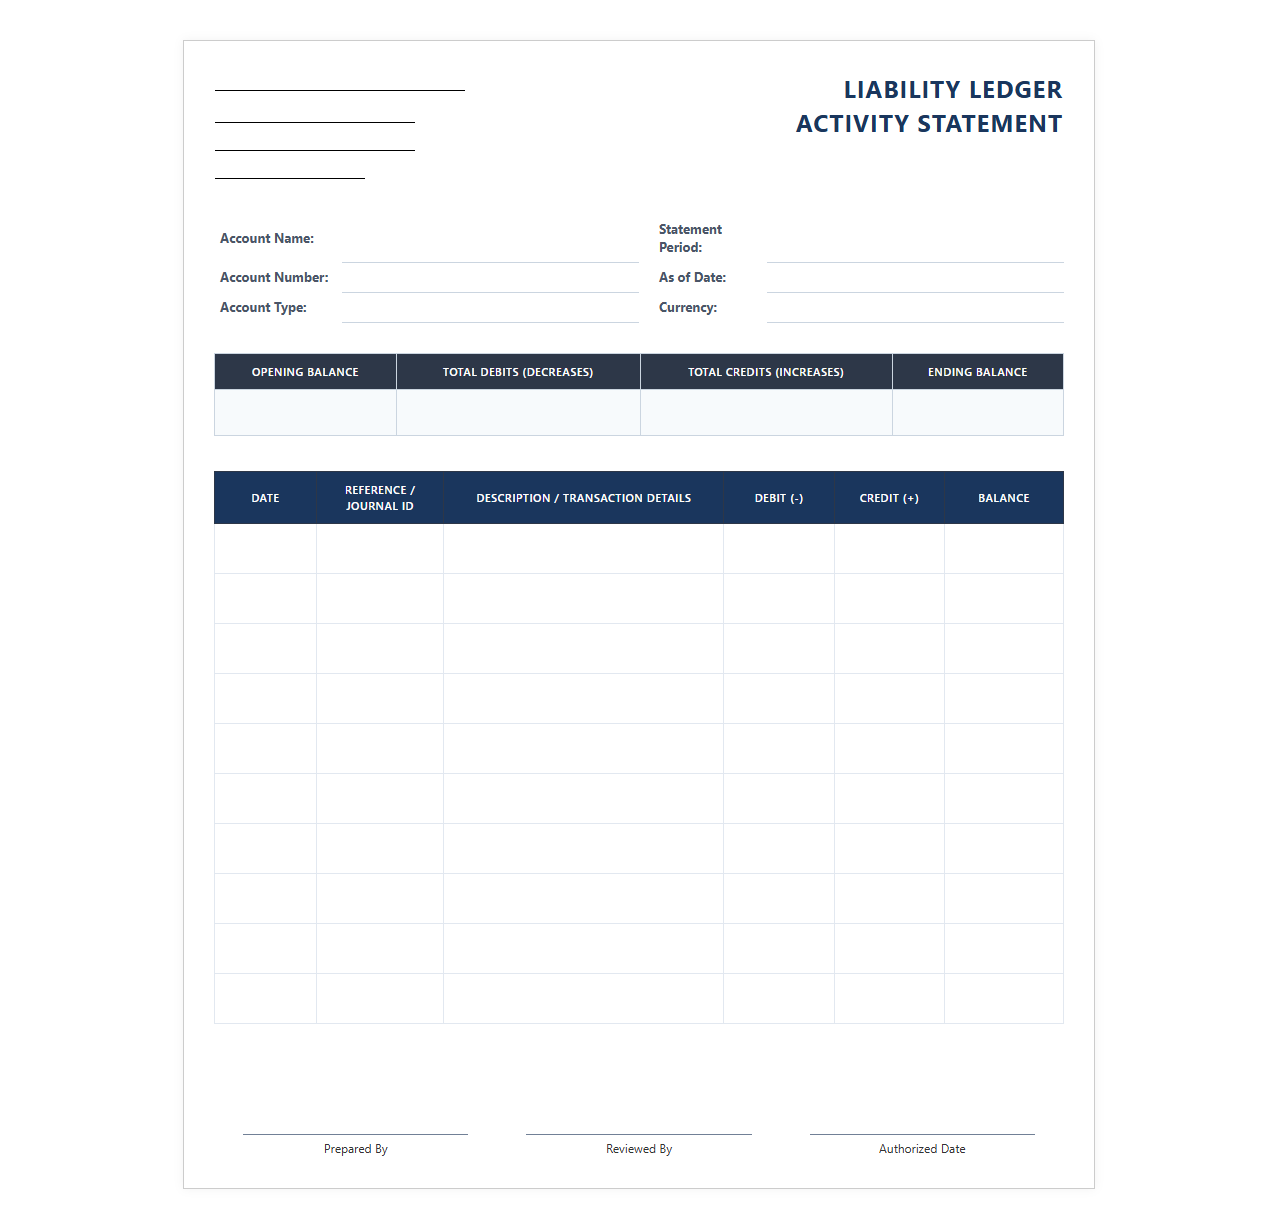 Download: .PDF
Accrued Liability Account Statement Template
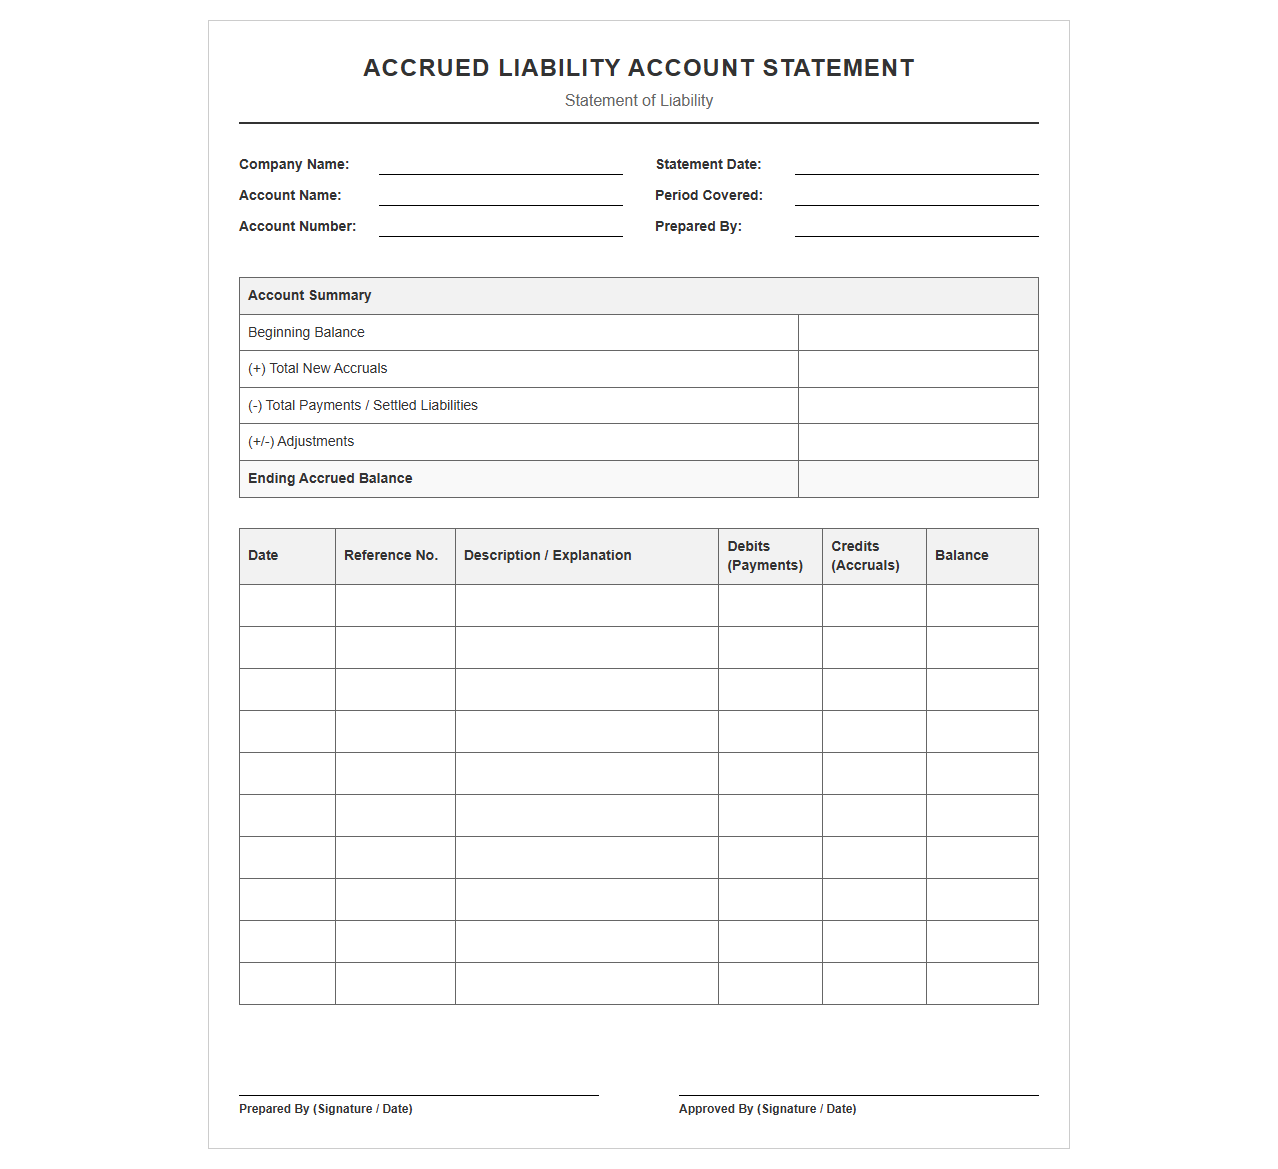 Download: .PDF
Business Liability Disclosure Statement Template
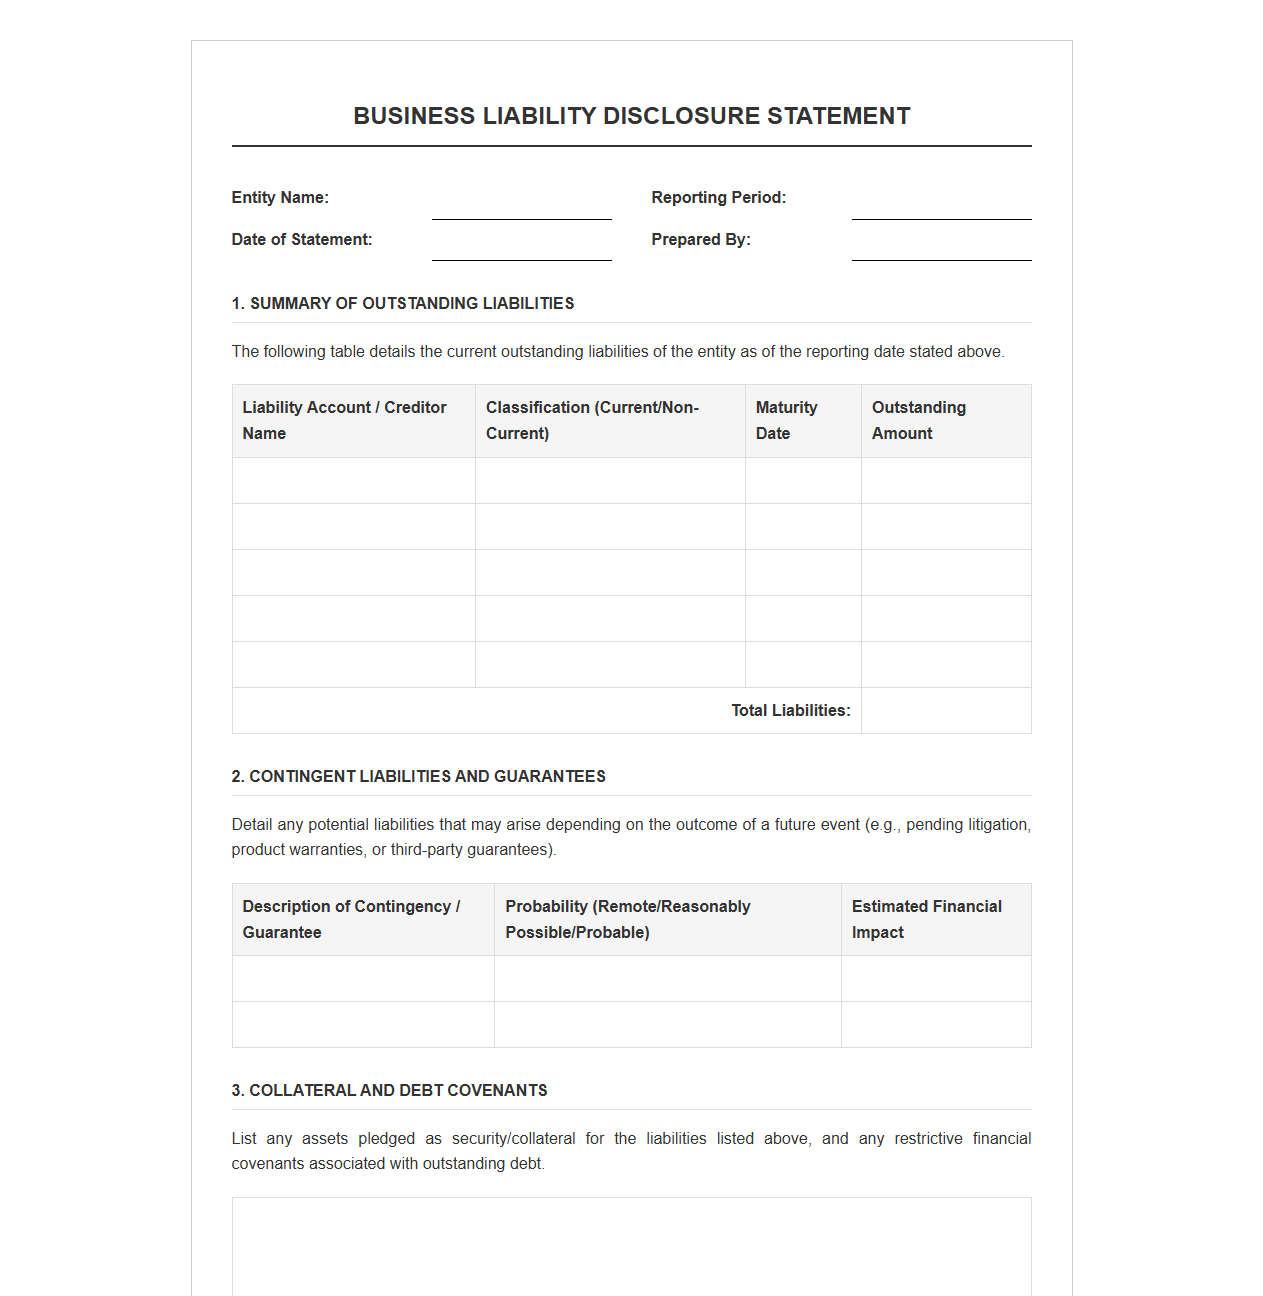 Download: .PDF
The Critical Impact of Liability Account Discrepancies
In corporate finance, liability accounts represent the obligations a company must fulfill to maintain its operational integrity and market standing. When discrepancies arise between general ledgers and supporting records, they introduce severe financial and compliance risks that can compromise the entire organization. Unresolved mismatches can lead to understated debts, overstated earnings, and sudden cash flow strains that catch leadership off guard. Resolving these imbalances promptly is essential to protect the business from regulatory penalties, material weaknesses in financial reporting, and a loss of investor confidence.
The Power of Standardization in Financial Reconciliation
Adopting standardized statement templates is a highly effective way to mitigate these risks. By implementing a uniform structure across all liability categories, accounting teams can significantly accelerate the monthly reconciliation process. Standardization reduces the cognitive load on analysts, minimizes the risk of human error during data entry, and ensures that every account is evaluated using the exact same rigorous methodology. This level of consistency is invaluable for establishing a reliable audit trail and ensuring that any emerging discrepancies are flagged instantly.
Anatomical Breakdown of an Effective Liability Template
To ensure comprehensive oversight, a standardized liability reconciliation template must capture specific, granular data points. A high-quality template should contain the following core elements:
- Opening Balance: The verified carryover balance from the previous accounting period.
- Transaction Logs: A chronological record of all additions, payments, and adjustments during the current cycle.
- Outstanding Obligations: Detailed lists of pending invoices, accrued expenses, or long-term debts not yet settled.
- Closing Balance: The calculated ending balance that must align with the general ledger.
A Step-by-Step Guide to Resolving Balance Mismatches
When a mismatch between the general ledger and sub-ledger is identified, accounting teams should follow a structured, chronological sequence to isolate and rectify the error:
- Verify the Inputs: Confirm that all starting balances in the template perfectly match the finalized closing balances of the prior period.
- Run a Transaction-Level Match: Compare the sub-ledger transaction log against bank statements and general ledger postings to spot omitted or duplicated entries.
- Isolate Timing Differences: Identify payments or accruals recorded in one ledger but pending in the other due to processing delays.
- Post Corrective Adjustments: Document the root cause of the error and post approved journal entries to bring the accounts back into balance.
Categorizing Common Culprits Behind Liability Errors
Understanding the common origins of balance sheet errors allows teams to proactively search for discrepancies. The table below maps frequent issues to their corresponding template indicators:
| Error Category | Primary Cause | Template Indicator |
|---|---|---|
| Timing Differences | Delayed processing of end-of-month payments | Unmatched open items in transaction logs |
| Data Entry Errors | Manual transposition of figures | Discrepancies in closing balances |
| Unrecorded Transactions | Missing accruals or unbilled vendor invoices | Variance between ledger and sub-ledger totals |
Best Practices for Implementing Reconciliation Templates
Successfully integrating new templates into existing workflows requires strategic planning and clear accountability. Teams must embed these tools directly into their monthly close processes rather than treating them as an afterthought.
"Reconciliation is not merely a post-closing checklist item; it is an active control mechanism. Integrating standardized templates into daily or weekly workflows transforms the close process from a stressful race into a routine verification."
Elevating Financial Integrity Through Proactive Reconciliation
Adopting a proactive approach to liability reconciliation safeguards a company's fiscal health and strengthens its operational foundation. Maintaining clean, standardized records ensures constant audit readiness, guarantees accurate financial reporting, and fosters deep trust among lenders, investors, and internal leadership. Organizations that prioritize these practices protect their bottom line and build a reputation for flawless corporate governance. To learn more about modern accounting standards, you can review current guidelines on the Financial Accounting Standards Board (FASB) website.

Leave a comment