Managing reserves and surplus equity reporting is notoriously tedious, often leading to frustrating reconciliation errors and compliance anxiety during year-end audits. While traditional manual spreadsheets have long been the default, the increasing complexity of modern financial reporting standards demands a more structured, systematic approach to equity management.
Implementing standardized statement templates grants finance teams immediate structural clarity, transforming chaotic data points into audit-ready disclosures. It is important to note, however, that these templates are designed to complement-not replace-rigorous internal controls and professional accounting oversight. Specifically, tracking fluctuating movements in share premium accounts or documenting adjustments in revaluation reserves becomes a streamlined, verifiable process rather than a manual headache.
This article will dissect the essential components of a robust equity statement, explore key template structures for reserves and surplus management, and offer practical integration strategies to elevate your financial reporting workflow.
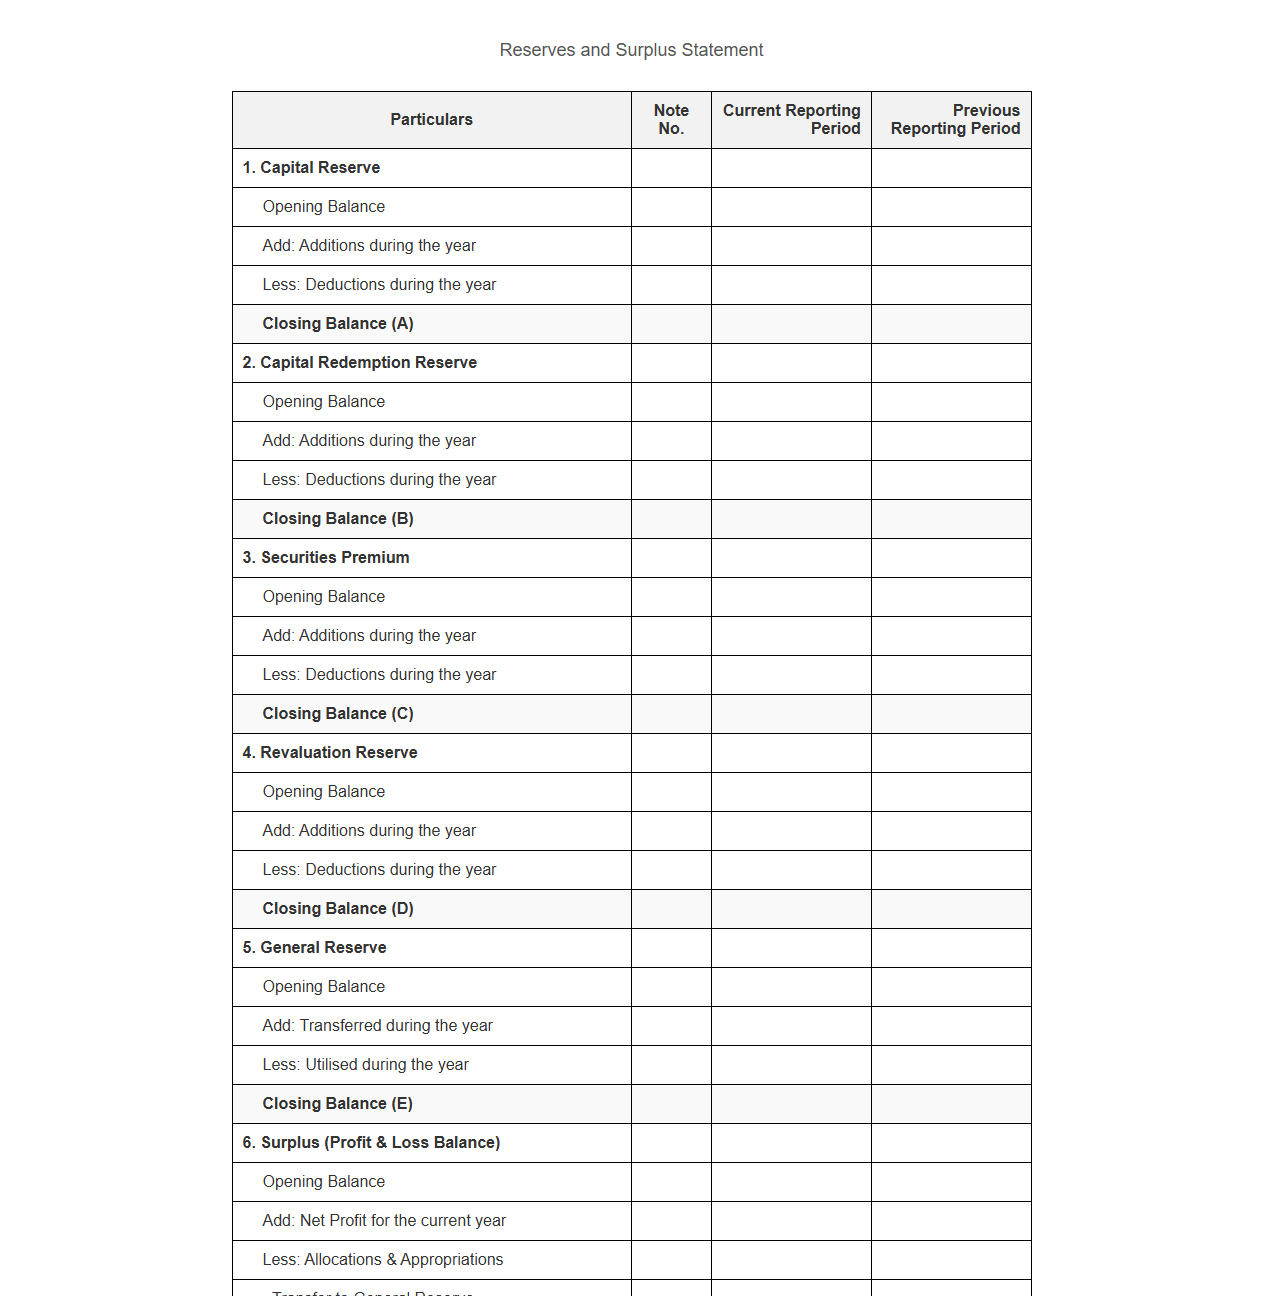
Reserves and Surplus Balance Sheet Statement Template
 Download: .PDF
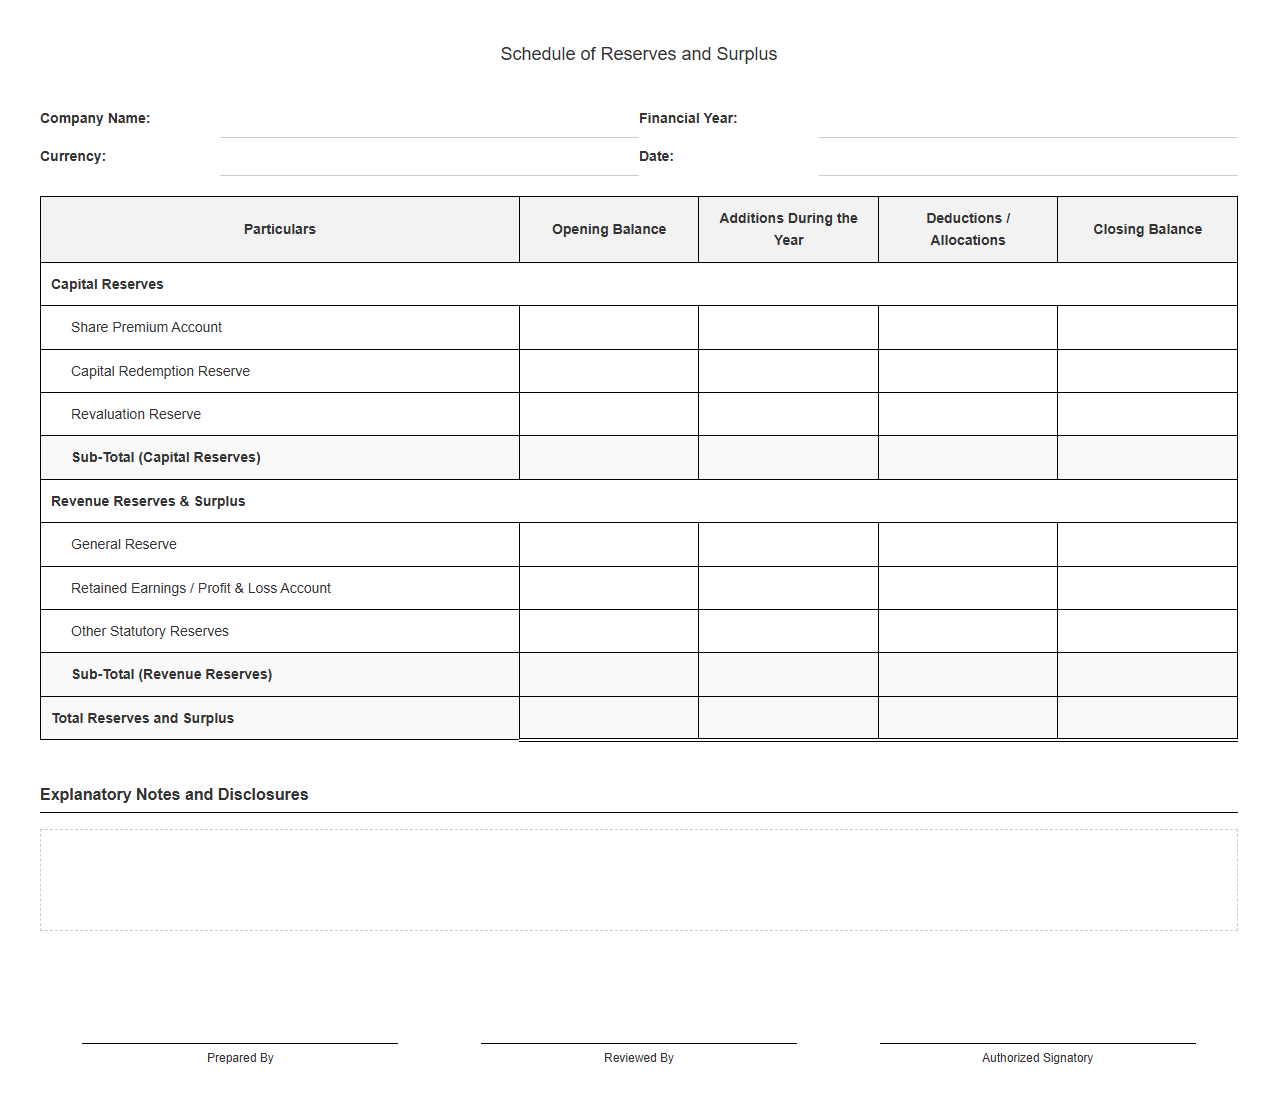
Schedule of Reserves and Surplus Disclosure Statement
 Download: .PDF
Statement of Changes in Reserves and Surplus
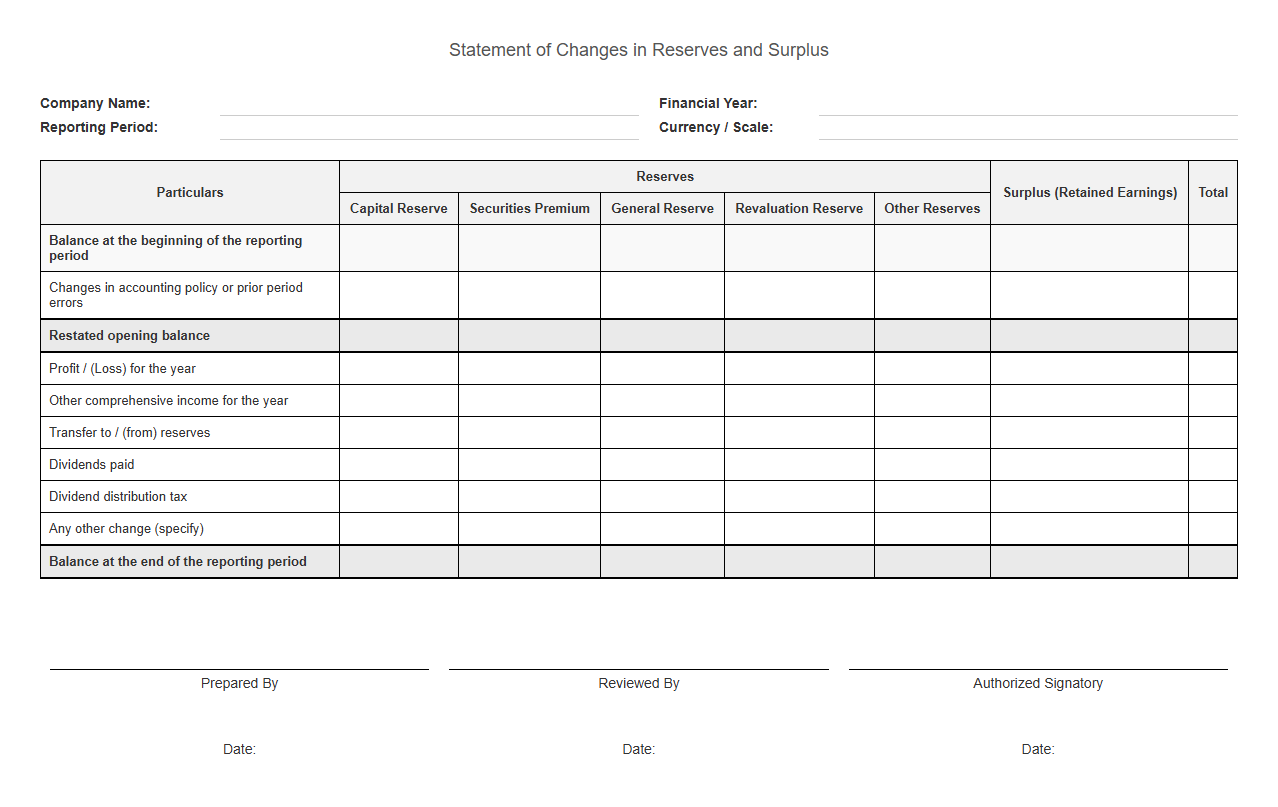 Download: .PDF
Annual Reserves and Retained Earnings Surplus Statement
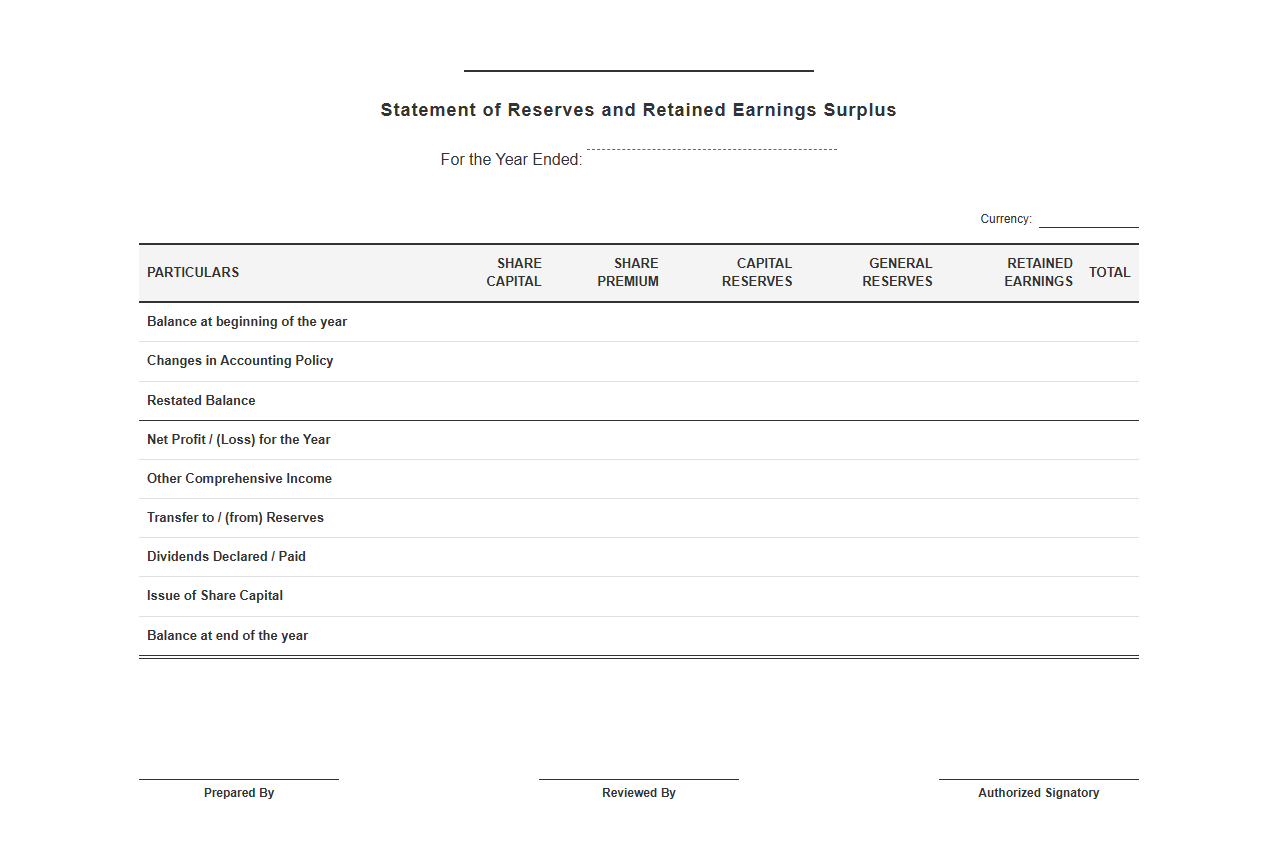 Download: .PDF
Corporate Reserves and Surplus Reconciliation Template
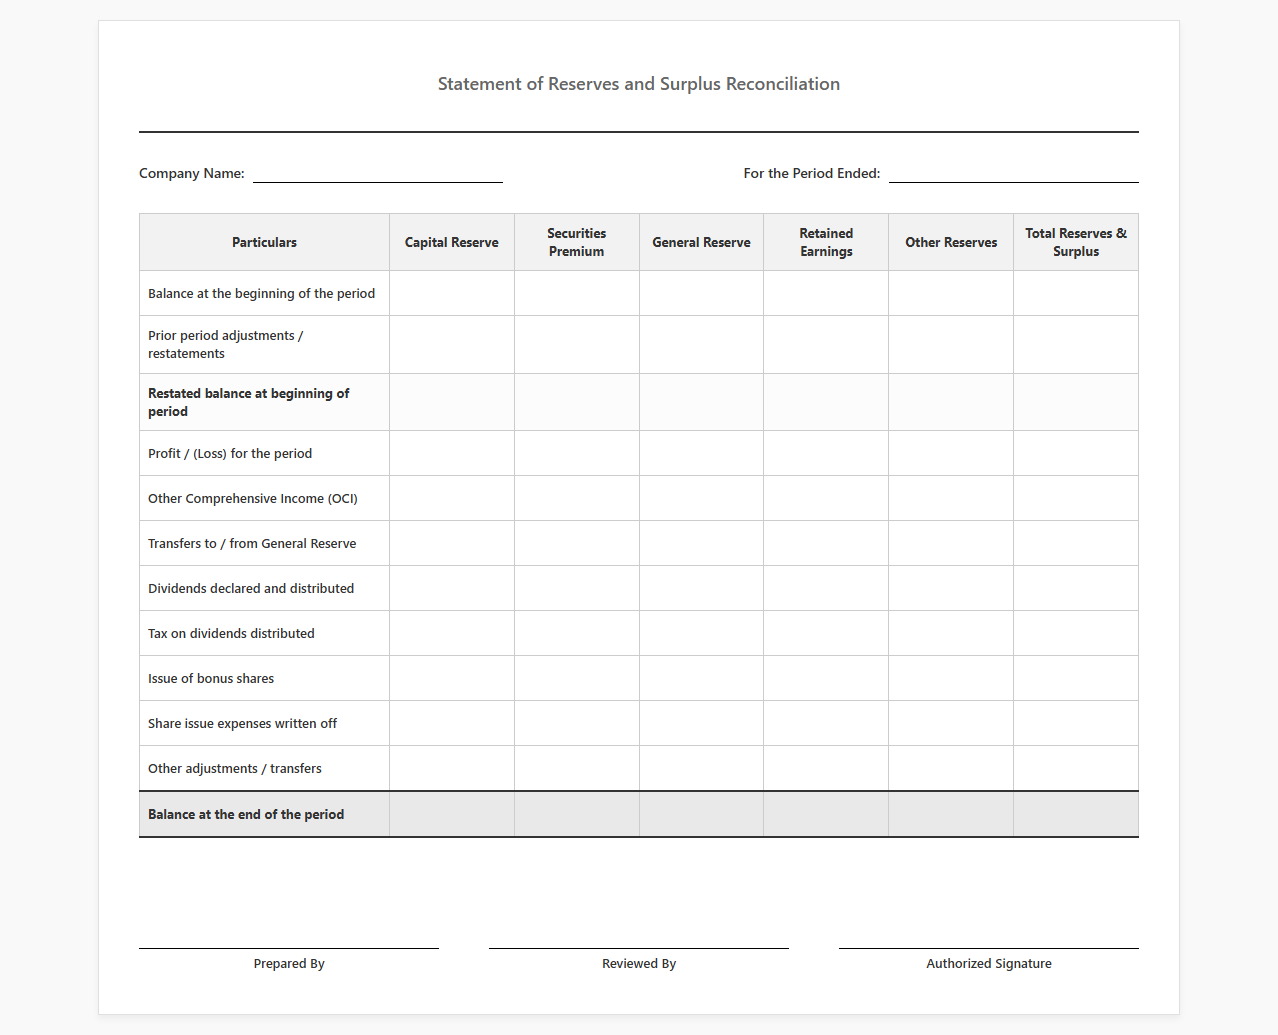 Download: .PDF
Financial Statement Template for Reserves and Surplus
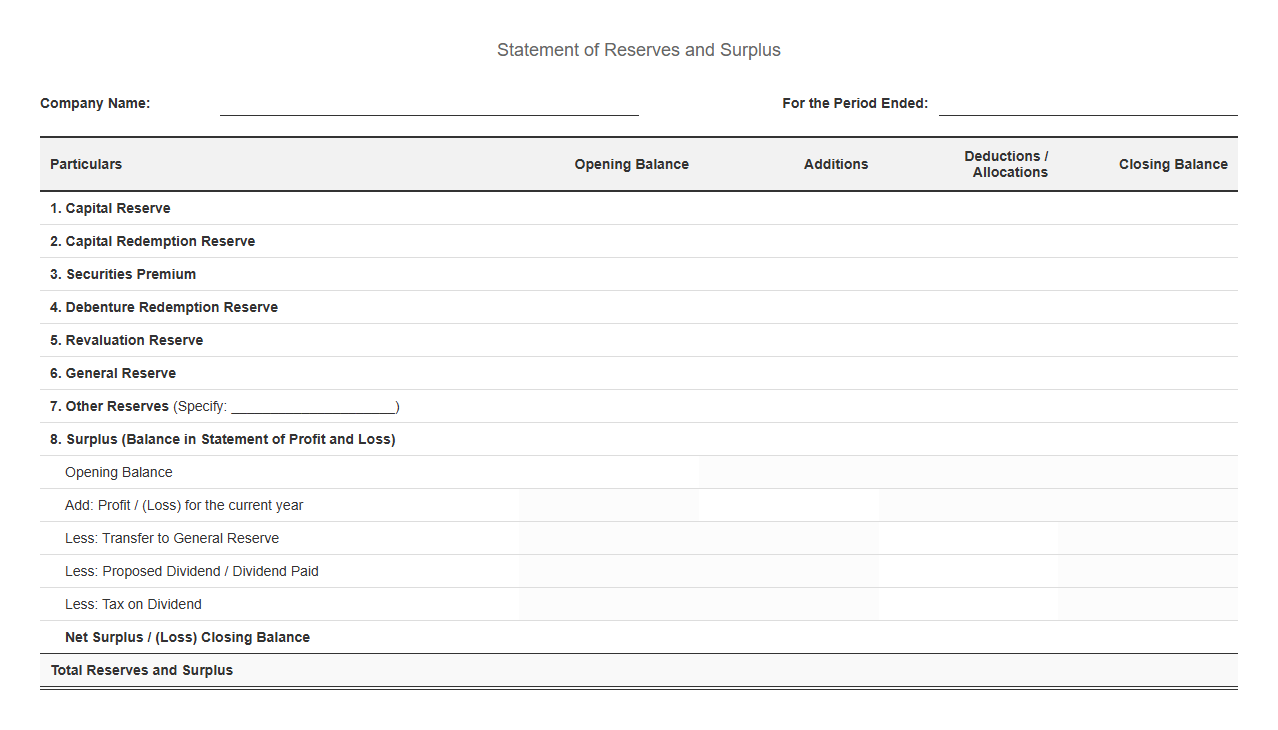 Download: .PDF
Capital Reserves and Revenue Surplus Reporting Statement
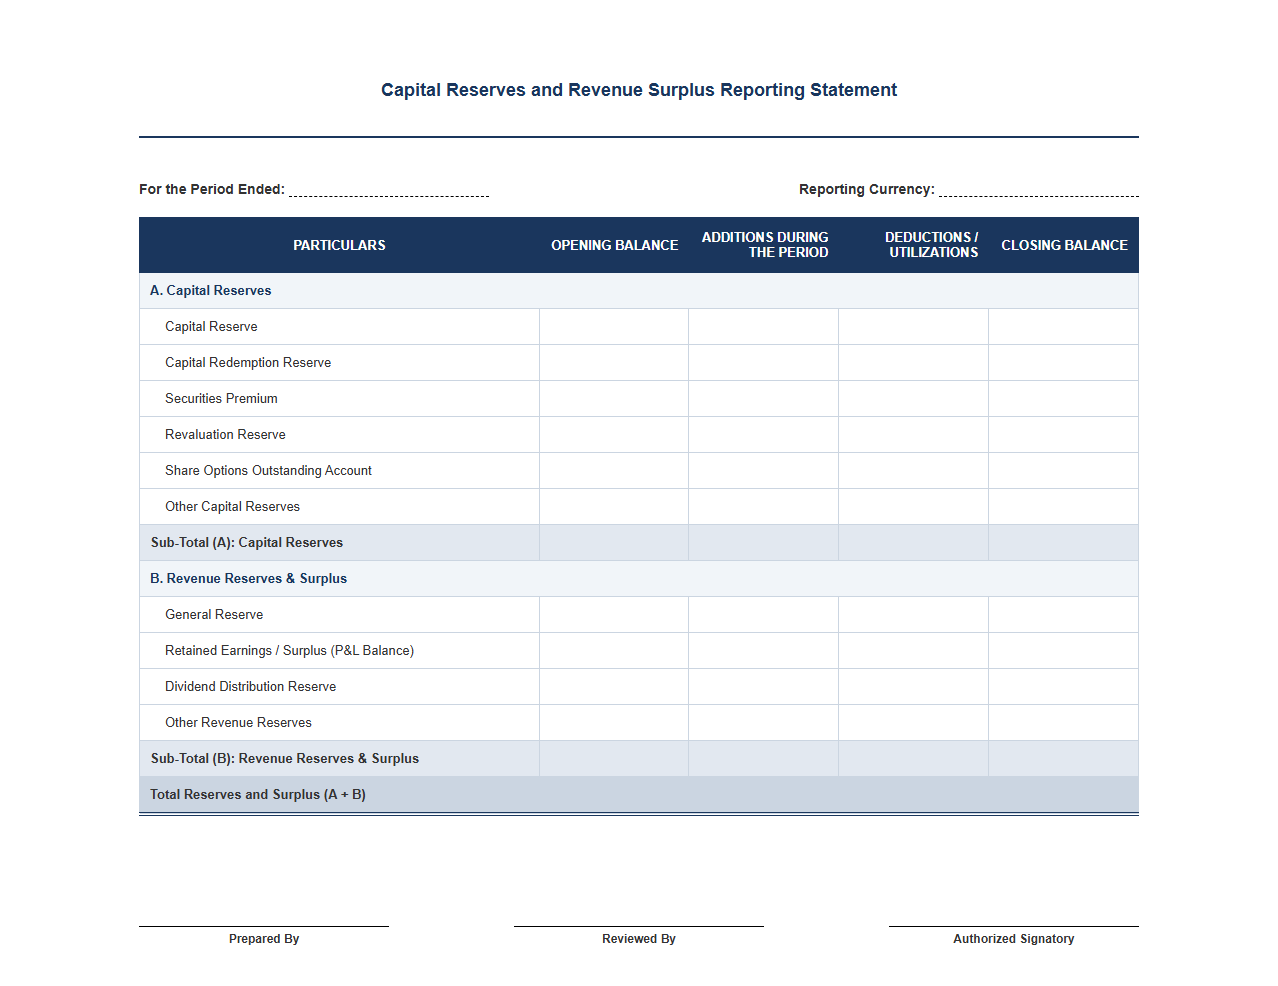 Download: .PDF
Quarterly Statement of Reserves and Surplus Allocation
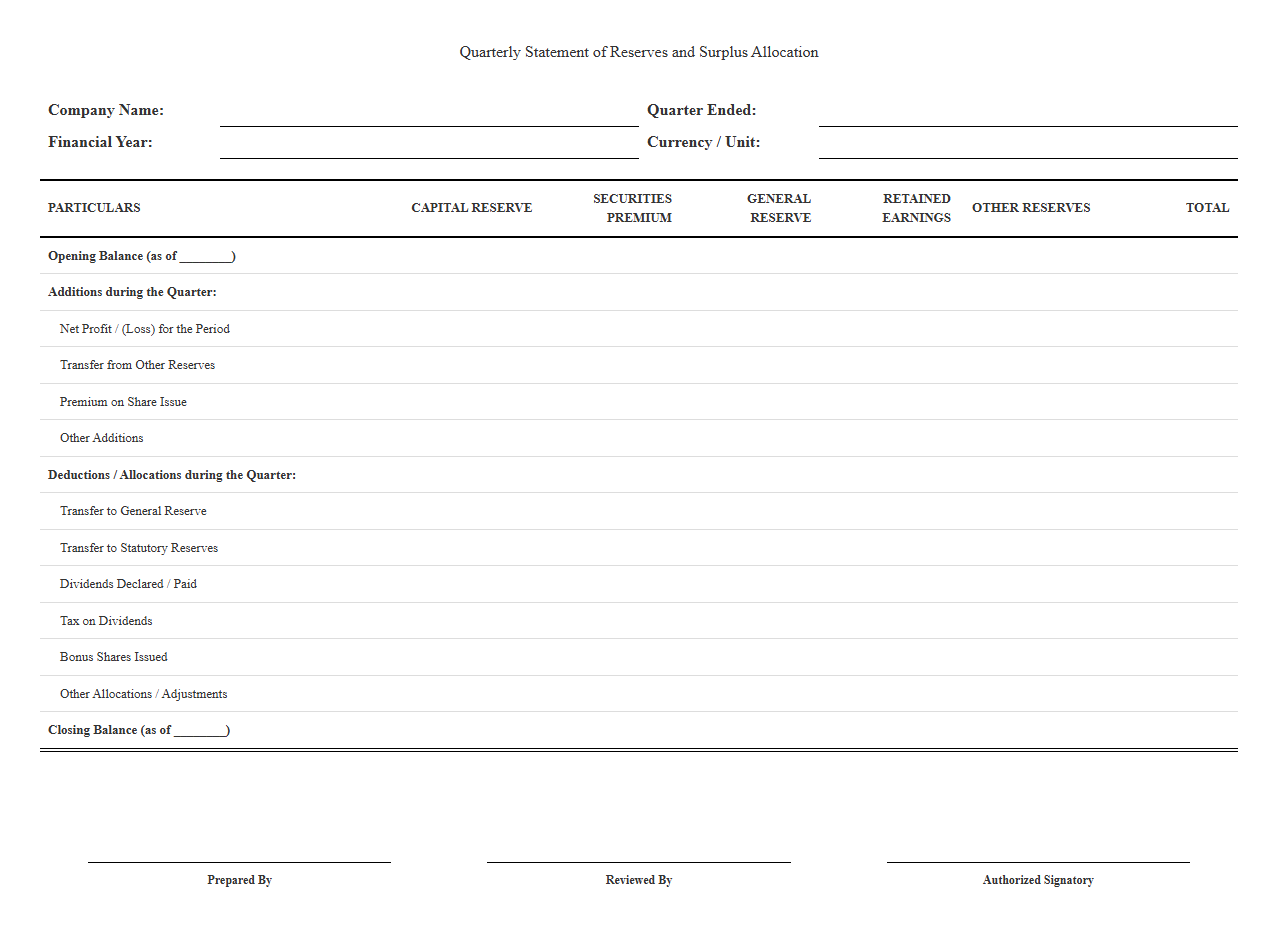 Download: .PDF
Introduction to Equity Reporting and Reserves
Equity reporting serves as a cornerstone of corporate financial transparency, offering stakeholders a clear view of an organization's net worth. At the heart of this reporting lies the management of reserves and surplus, which represents the accumulated earnings and capital built up over time. Managing these balances effectively is not just a regulatory obligation; it is a strategic necessity that demonstrates a company's fiscal health, solvency, and capacity for future growth.
By maintaining clear records of how profits are retained, reinvested, or distributed, organizations build trust with investors, creditors, and regulatory bodies. Transparent equity reporting ensures that all parties can accurately assess the company's financial resilience and long-term viability in a highly competitive market.
Key Components of Reserves and Surplus
- Capital Reserves
- Funds set aside from non-operational profits, such as the sale of fixed assets, share premiums, or revaluation of assets. These reserves are generally not available for distribution as dividends.
- Revenue Reserves
- Retained earnings created out of the core operating profits of the business. These reserves are kept aside to meet future contingencies, strengthen the financial position, or distribute dividends to shareholders.
- Retained Earnings
- The cumulative percentage of net earnings that is not paid out as dividends but is retained by the company to be reinvested in its core business or to pay down debt.
Streamlining Reports with Standardized Statement Templates
Utilizing pre-designed statement templates dramatically simplifies the complex process of equity reporting. These structured frameworks ensure that financial teams do not have to recreate reports from scratch every reporting cycle, which significantly saves time and allows analysts to focus on deeper strategic insights. By establishing a uniform layout, templates reduce compliance errors by ensuring all mandatory disclosures and calculations are systematically included. Standardized formats make it easier to maintain internal consistency across different fiscal years, providing a reliable foundation for auditing and stakeholder reviews.
Essential Fields in a Reserves and Surplus Template
| Reserve Category | Opening Balance | Additions (Current Year) | Deductions / Utilizations | Closing Balance |
|---|---|---|---|---|
| General Reserve | $500,000 | $50,000 | $0 | $550,000 |
| Capital Reserve | $200,000 | $15,000 | $5,000 | $210,000 |
| Retained Earnings | $1,200,000 | $300,000 | $100,000 | $1,400,000 |
Common Pitfalls in Equity and Surplus Management
- Misclassification of funds between capital reserves and revenue reserves, leading to incorrect dividend availability assessments.
- Delayed ledger updates that result in discrepancies between current operational realities and reported equity figures.
- Inadequate tracking of equity transactions, such as stock buybacks or capital injections, causing misalignment in balance sheets.
- Neglecting to document the specific business purposes of restricted reserves, which risks regulatory scrutiny during audits.
Best Practices for Compliance and Accuracy
- Conduct regular reconciliations of equity ledger accounts to align with actual bank transactions and board resolutions, complying with Generally Accepted Accounting Principles (GAAP).
- Maintain clear, timestamped audit trails for every addition or deduction made within the reserves, ensuring adherence to International Financial Reporting Standards (IFRS).
- Train financial staff continuously on evolving regulatory guidelines to prevent reporting inaccuracies and avoid penalties under local statutory frameworks.
Embracing Digital Tools for Modern Equity Reporting
Transitioning from static spreadsheets to modern financial software elevates equity reporting from a repetitive administrative burden to a high-value strategic asset. Automation minimizes human error, ensures real-time updates to balances, and allows stakeholders to gain immediate insights into corporate equity structures. By integrating sophisticated digital templates into daily workflows, finance teams can confidently drive business growth, secure investor trust, and simplify compliance management.
Explore our collection of customizable resources and optimize your workflows today by accessing professional equity and surplus templates.
Leave a comment