Consolidating corporate equity is notoriously complex, often leaving finance teams struggling with manual reconciliation errors that distort a company's true financial health. Before addressing automated solutions, however, it is critical to recognize that robust, transparent reporting remains the absolute bedrock of corporate governance and stakeholder trust.
Utilizing professional retained earnings statement templates grants corporate treasurers absolute precision and hours of reclaimed time, transforming a tedious compliance burden into a streamlined workflow. While these structured frameworks simplify tracking key variables-such as net income adjustments and cash dividend distributions-they are designed to complement, rather than replace, rigorous CPA oversight.
In this guide, we will examine the core components of an accurate equity statement, evaluate industry-standard template designs, and outline best practices to ensure your corporate financial reporting is flawless and audit-ready.
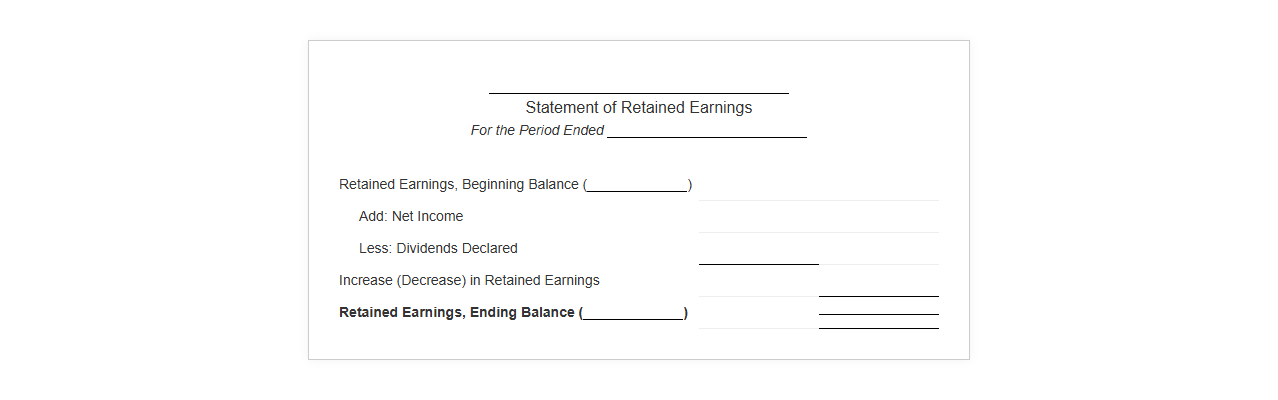
Statement of Retained Earnings Template
 Download: .PDF
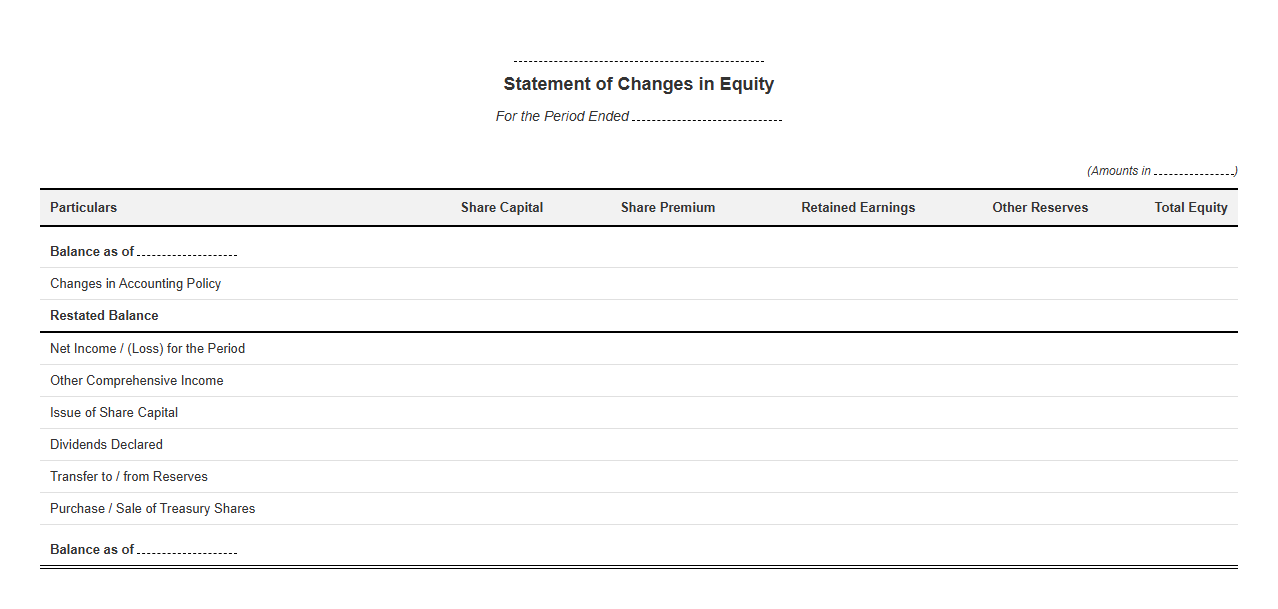
Statement of Changes in Equity Template
 Download: .PDF
Accumulated Earnings Statement Template
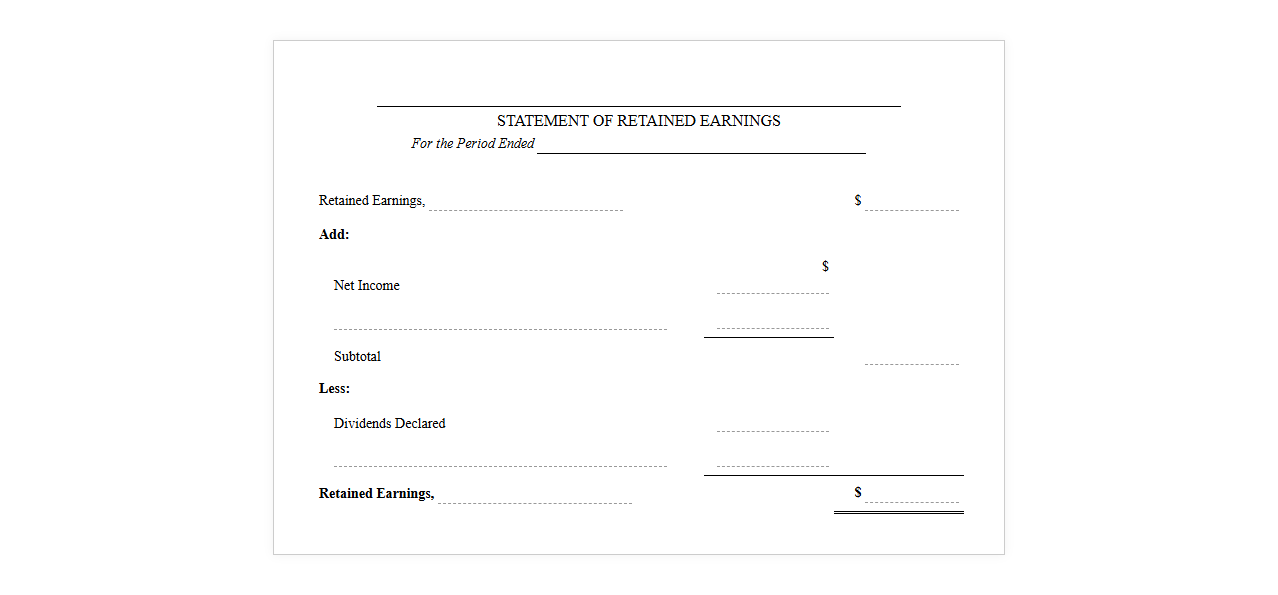 Download: .PDF
Statement of Owners Equity Template
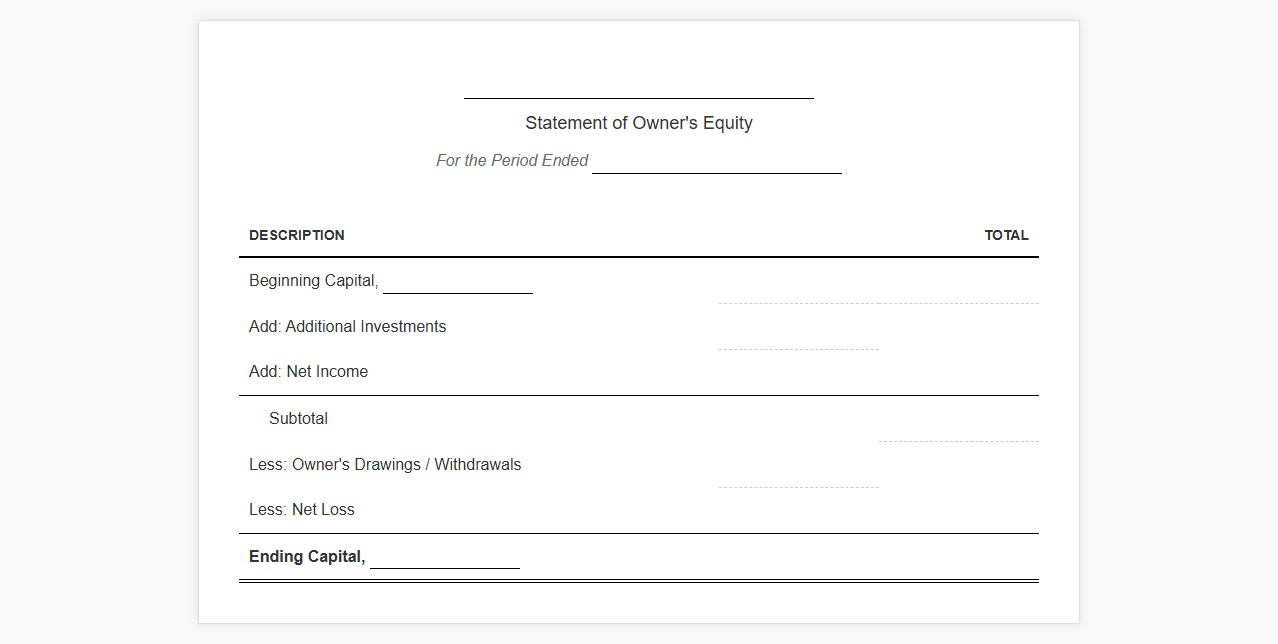 Download: .PDF
Retained Earnings Report Template
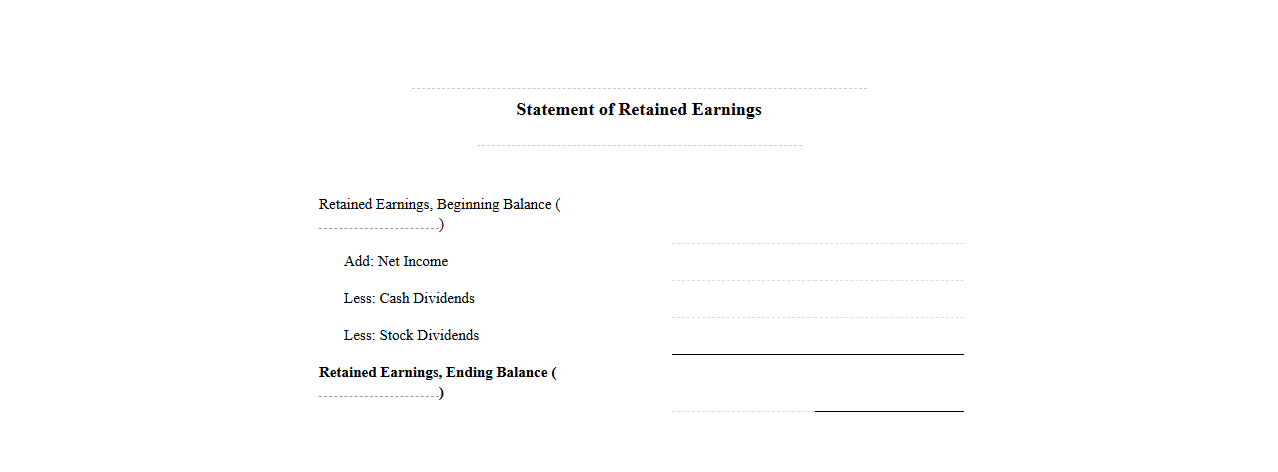 Download: .PDF
Annual Retained Earnings Statement Spreadsheet
 Download: .PDF
Monthly Retained Earnings Calculation Template
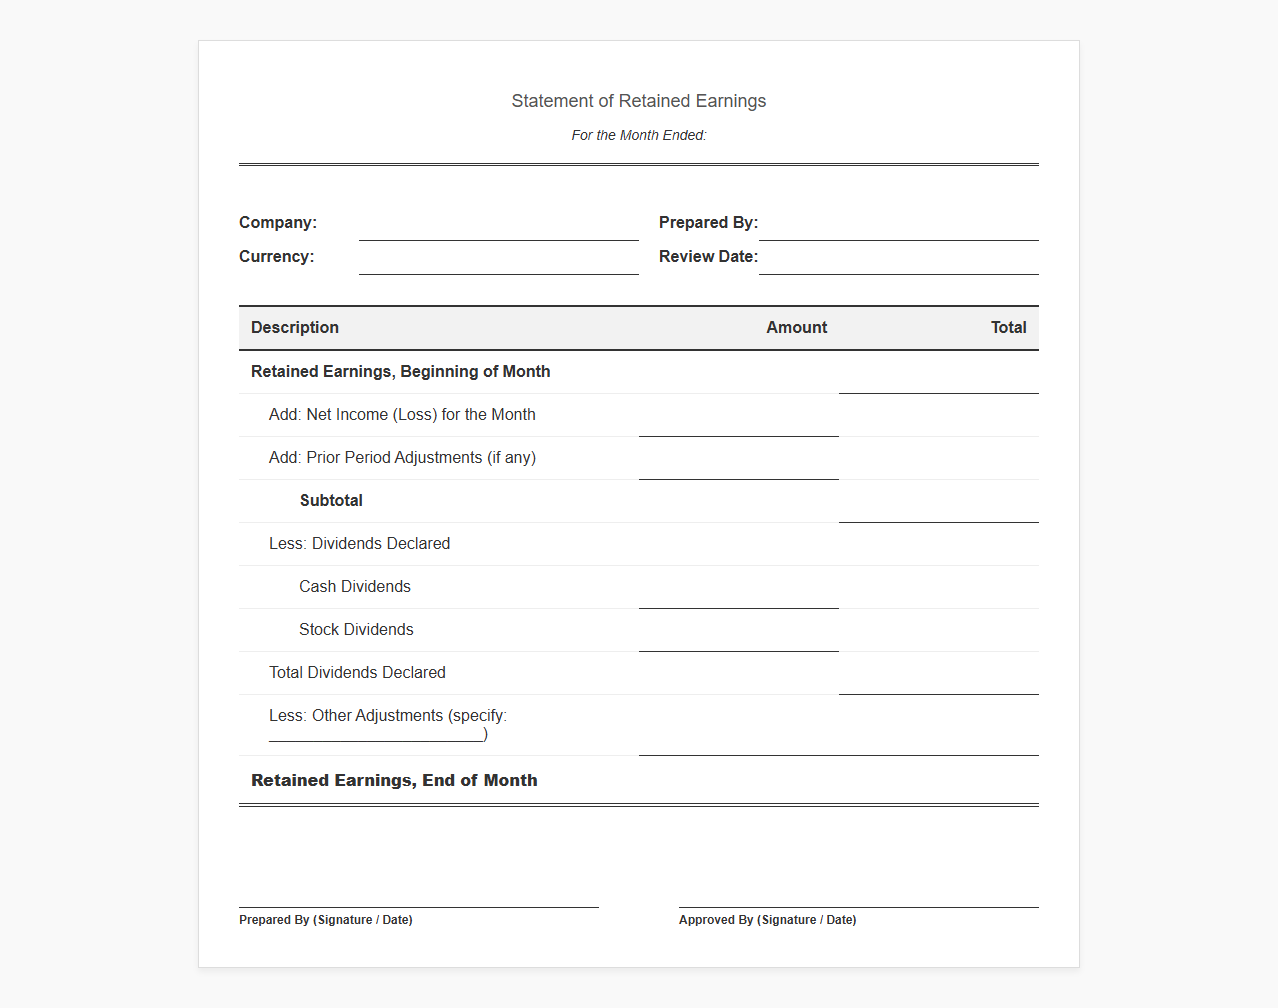 Download: .PDF
Corporate Retained Earnings Statement Template
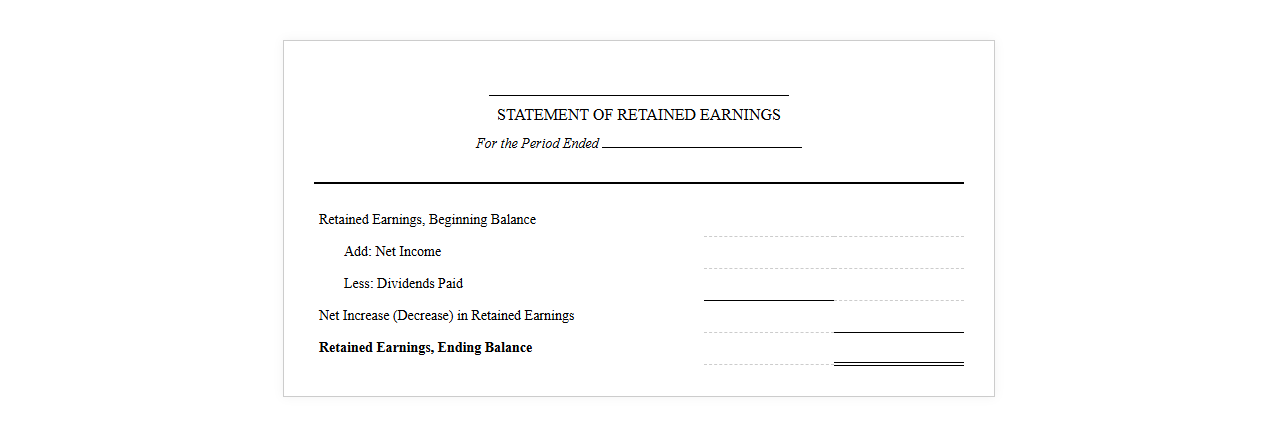 Download: .PDF
Understanding the Role of Retained Earnings in Corporate Equity
Retained earnings represent the cumulative net income of a corporation that remains after distributing dividends to shareholders. Rather than being distributed, these funds are reinvested back into the business to fuel growth, pay down debt, or fund research and development. In corporate equity, they serve as a critical metric because they reflect the true value generated by the business over time. A healthy balance of retained earnings indicates a profitable company that has historical stability, making it highly attractive to investors and creditors who seek long-term financial viability.
Why Your Business Needs a Dedicated Retained Earnings Statement
A dedicated statement of retained earnings serves a unique purpose in corporate accounting. It acts as the financial connective tissue within your reporting, ensuring that net income from the income statement flows seamlessly into the equity section of the balance sheet. Without this distinct ledger, stakeholders would struggle to trace how profits are distributed or reinvested year-over-year.
For external stakeholders, this statement provides deep insights into management's capital allocation strategy. A business that consistently retains its earnings is often prioritizing expansion and internal funding, whereas a company distributing most of its earnings as dividends focuses on immediate investor returns. Tracking this transition is vital for maintaining transparency and accurate financial storytelling.
Essential Components of a Professional Retained Earnings Template
To prepare an accurate statement, a business must utilize a structured format. A professional template standardizes this process, ensuring that no critical transaction is overlooked during the closing period.
- Beginning Balance: The starting point, which is the ending balance of retained earnings from the previous accounting period.
- Net Income or Net Loss: The net profit or loss generated during the current period, extracted directly from the income statement.
- Dividends Paid: Any distributions made to shareholders, including both cash dividends and stock dividends, which reduce the total retained balance.
- Ending Balance: The calculated final sum that is carried forward to the balance sheet as the new equity total.
How to Calculate Retained Earnings Accurately
Calculating retained earnings is a straightforward mathematical process, but it requires absolute precision in sourcing the inputs. To find your ending balance, you must apply the foundational accounting formula:
Ending Retained Earnings = Beginning Retained Earnings + Net Income (or - Net Loss) - Dividends Paid
To ensure accuracy during your period-end close, follow these steps:
- Identify the ending retained earnings balance from the previous period's balance sheet and set it as your beginning balance.
- Add the net income or subtract the net loss generated in the current period, which is sourced from your finalized income statement.
- Subtract all cash and stock dividends declared during the current period.
- Calculate the final sum, which becomes the ending retained earnings balance for the current period's balance sheet.
Streamlining Financial Workflows with Standardized Templates
Relying on manual calculation methods increases the likelihood of human error, which can lead to costly compliance issues. Utilizing standardized Excel or PDF templates simplifies equity reporting by establishing a predictable, repeatable workflow for your accounting team.
Standardizing your financial reporting through pre-built templates not only saves valuable operational hours but also ensures strict compliance with GAAP and IFRS guidelines.
These templates serve as a protective barrier against formula errors, ensuring that every addition and subtraction aligns perfectly with the general ledger. By establishing a single source of truth, businesses can confidently present their financial standing to auditors and board members alike.
Frequent Pitfalls in Equity Reporting and How to Avoid Them
Even experienced accountants can run into hurdles when compiling equity statements. Recognizing these common errors beforehand is the best way to safeguard the integrity of your financial reports.
- Misclassifying Stock Dividends: Failing to distinguish between cash dividends and stock dividends can lead to errors in the common stock and paid-in capital accounts.
- Ignoring Prior-Period Adjustments: If an error is discovered from a previous year, it must be adjusted directly in the beginning balance of the current period's retained earnings, rather than being mixed into current net income.
- Overlooking Treasury Stock Transactions: Buying back company shares can impact retained earnings if the shares are retired or sold at a loss, requiring careful adjustments.
Implementing Best Practices for Accurate Corporate Equity Reporting
Establishing an accurate system for tracking corporate equity requires the right tools and a disciplined reporting schedule. By adopting robust, pre-formulated templates, your business can eliminate reporting discrepancies and present a clear picture of financial health to stakeholders. Integrate these practices into your regular financial close cycle to keep your balance sheet balanced and your growth strategy on track.
To get started on improving your financial workflows today, you can download our professional equity reporting templates to ensure error-free calculations for your next annual report.
Leave a comment