Financial reporting teams often struggle with the tedious, error-prone process of tracking and disclosing Accumulated Other Comprehensive Loss (AOCL). Under modern GAAP and IFRS frameworks, these complex figures require meticulous reconciliation from period-to-period OCI before they ever reach the balance sheet.
Deploying standardized statement templates grants finance departments the precise structure needed to slash manual compliance hours and drastically reduce audit risks. However, while templates offer a robust foundation, they must be treated as strategic frameworks rather than rigid solutions; they require careful calibration to your entity's specific regulatory environment.
This calibration is particularly crucial when accounting for highly volatile items such as unrecognized post-retirement pension losses or foreign currency translation adjustments. In this article, we will break down the essential components of AOCL disclosure, present customizable templates designed to streamline your reporting workflow, and outline best practices for seamless quarterly integration.
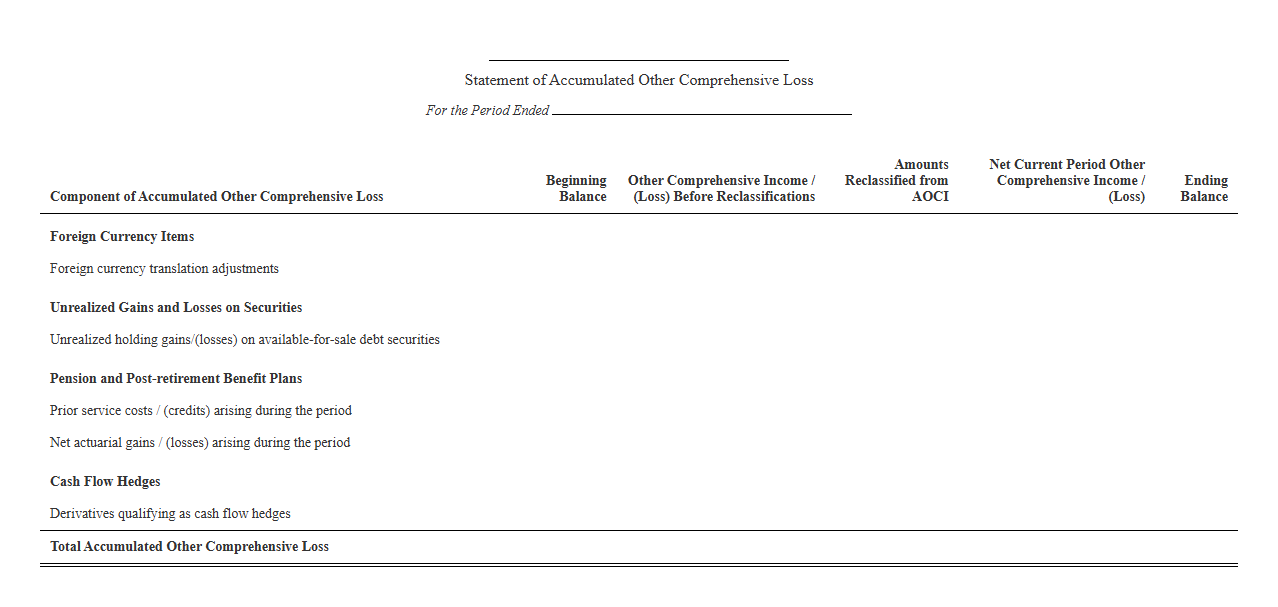
Accumulated Other Comprehensive Loss Statement Template
 Download: .PDF
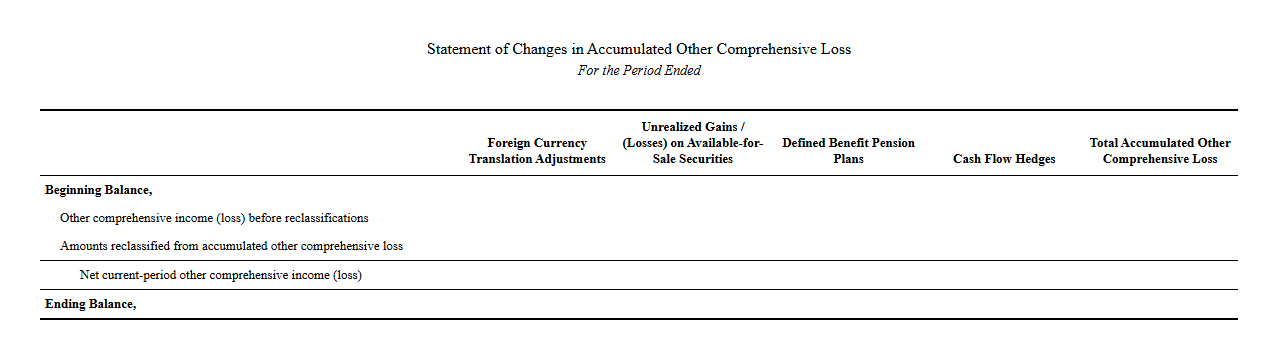
Statement of Changes in Accumulated Other Comprehensive Loss
 Download: .PDF
AOCI Statement and Disclosure Template
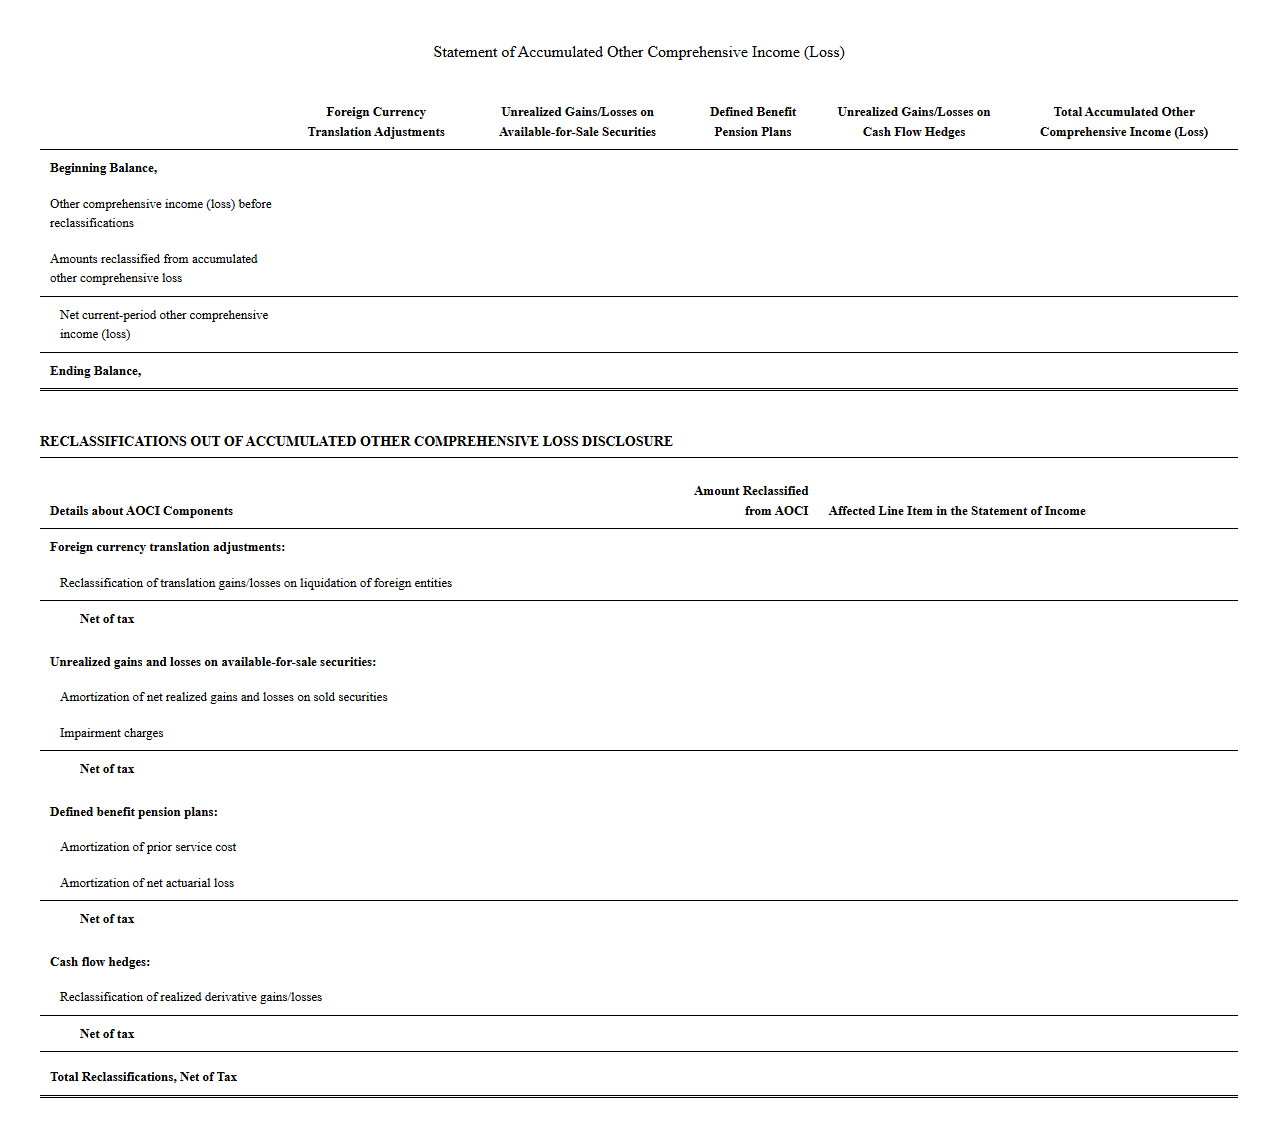 Download: .PDF
Accumulated Other Comprehensive Loss Ledger Template
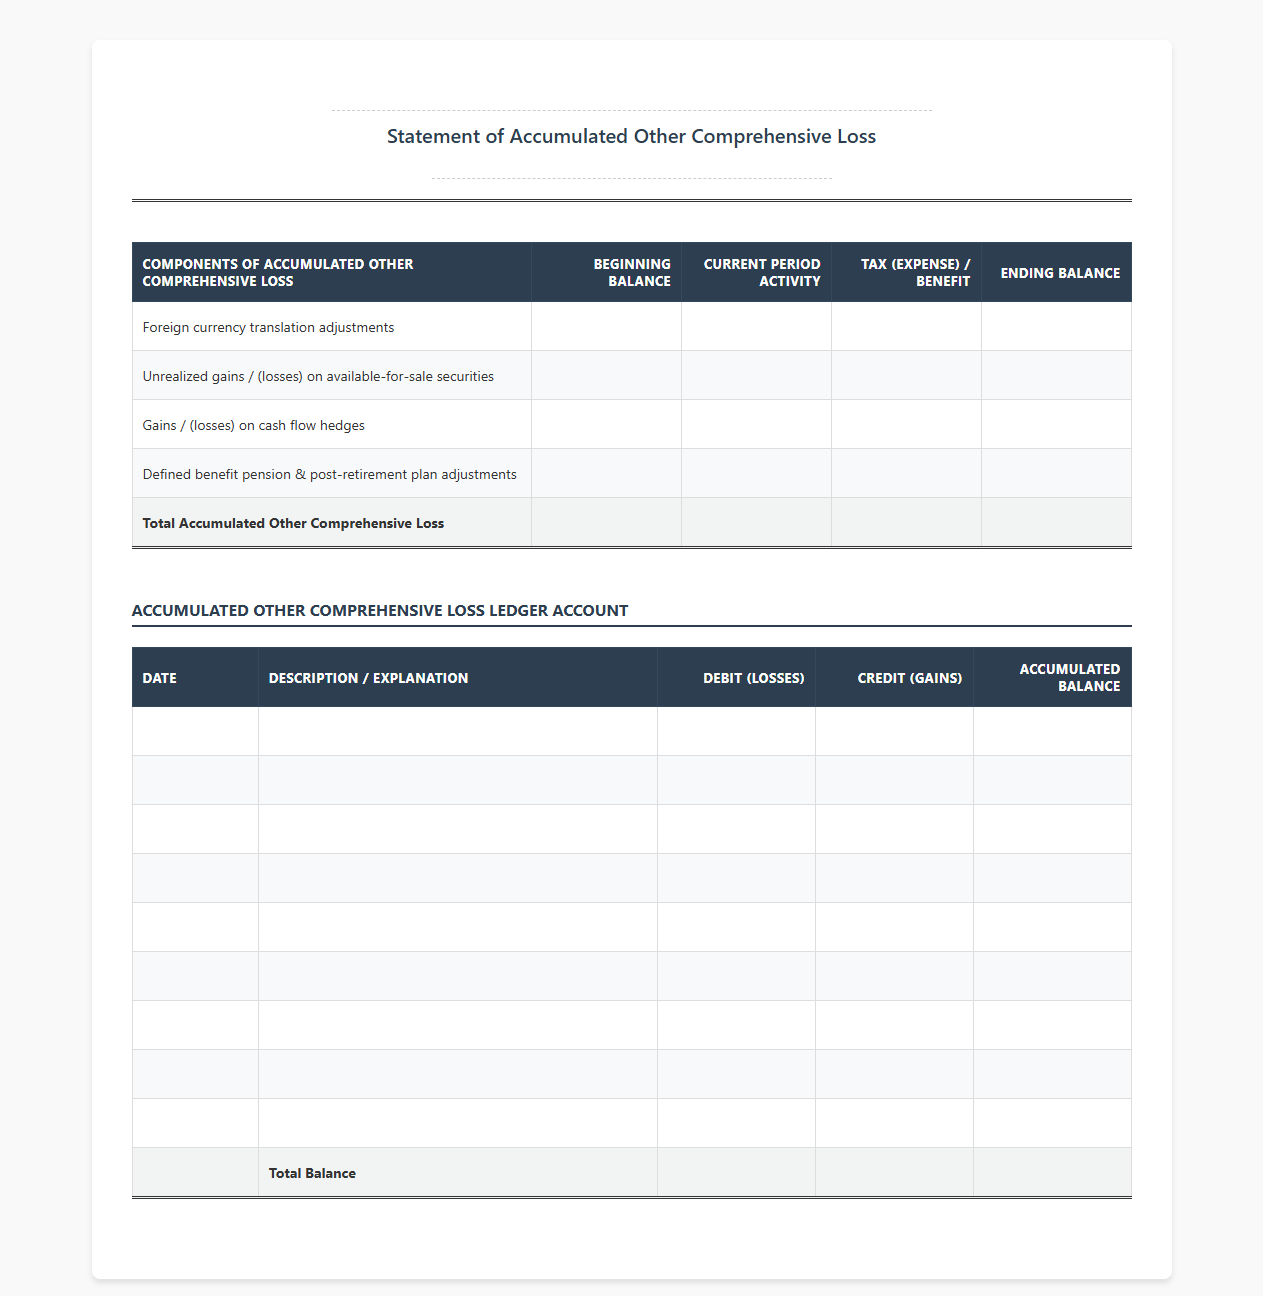 Download: .PDF
Quarterly Accumulated Other Comprehensive Loss Report Template
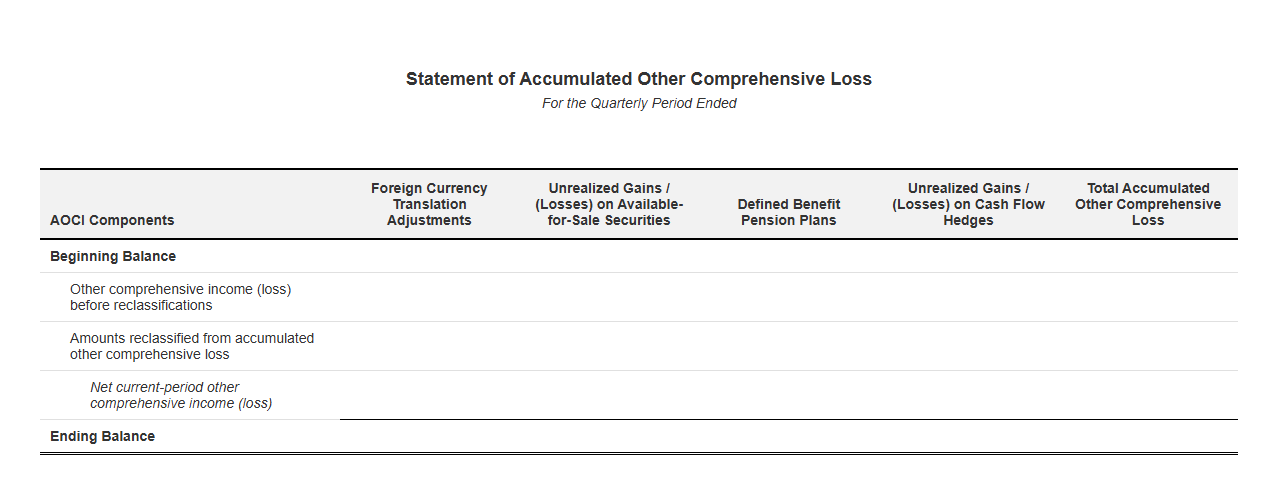 Download: .PDF
Corporate Accumulated Other Comprehensive Loss Reporting Template
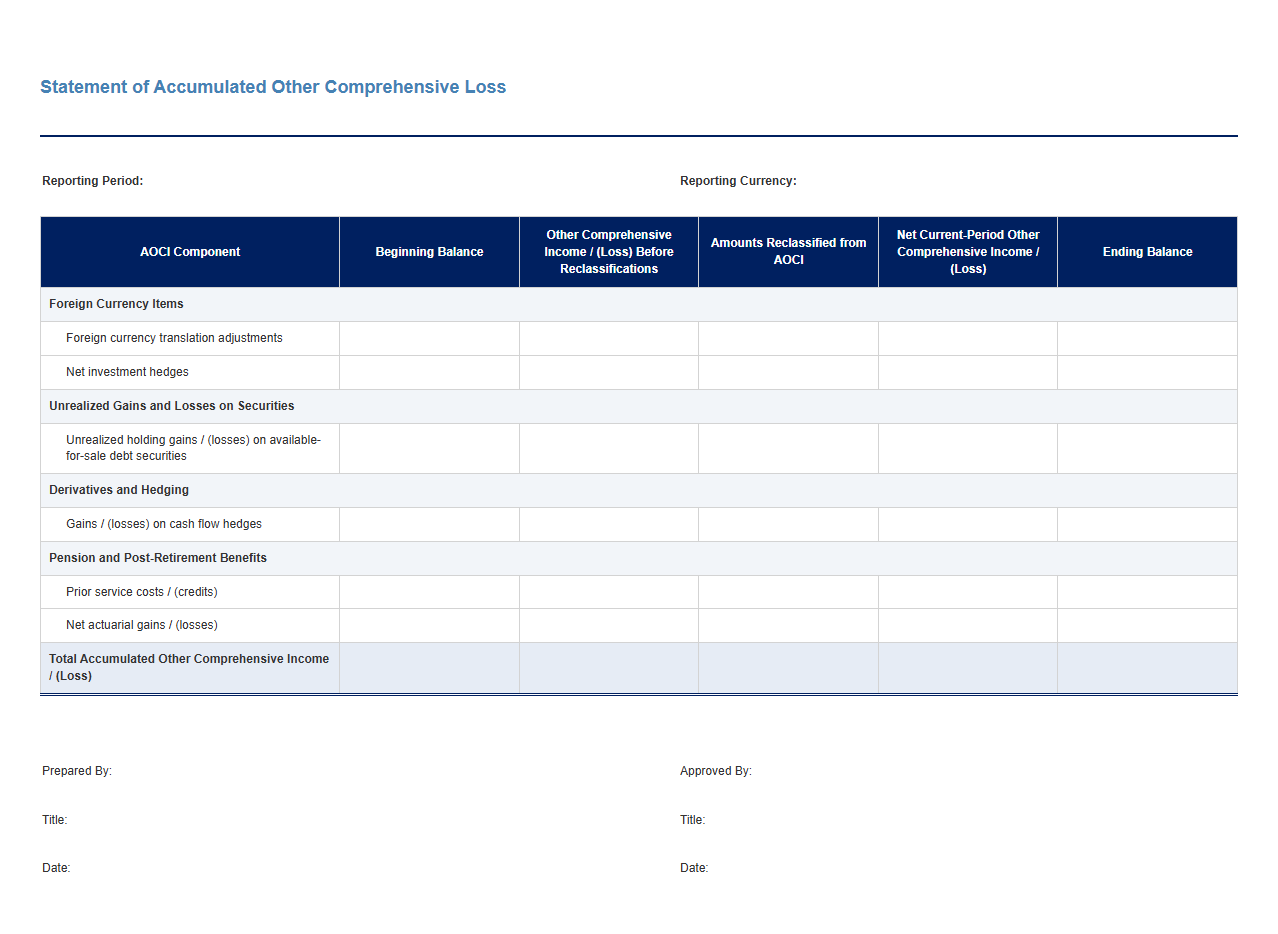 Download: .PDF
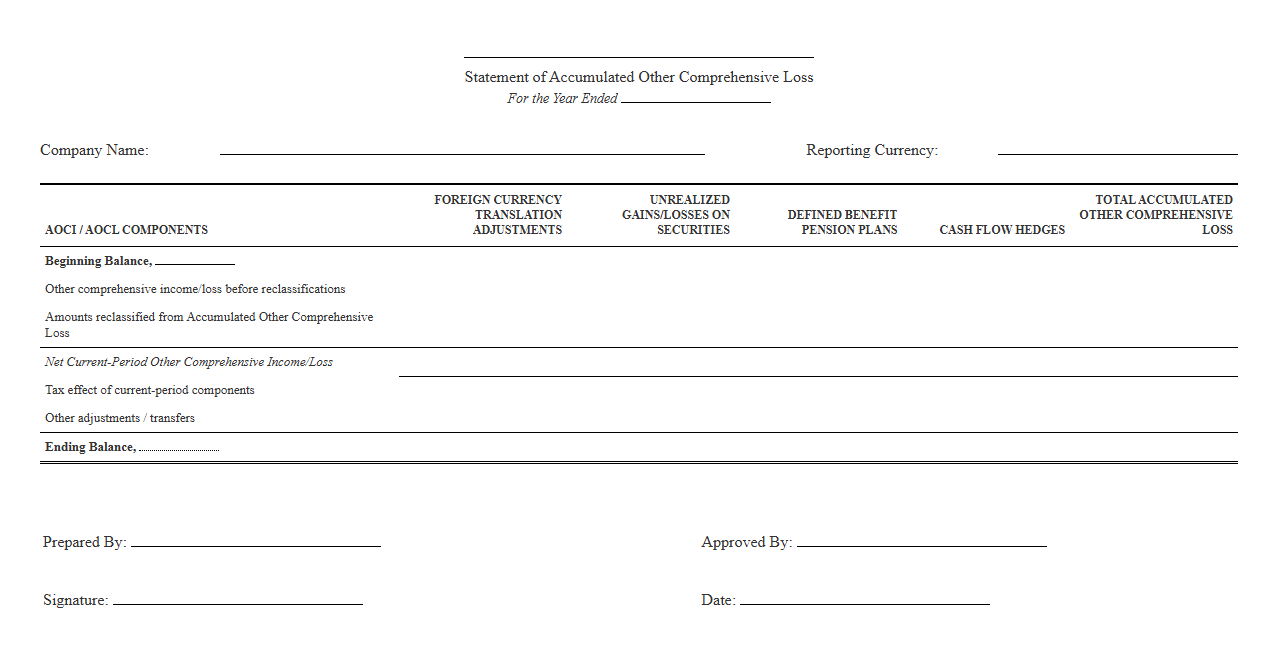
Annual Accumulated Other Comprehensive Loss Statement Form
 Download: .PDF
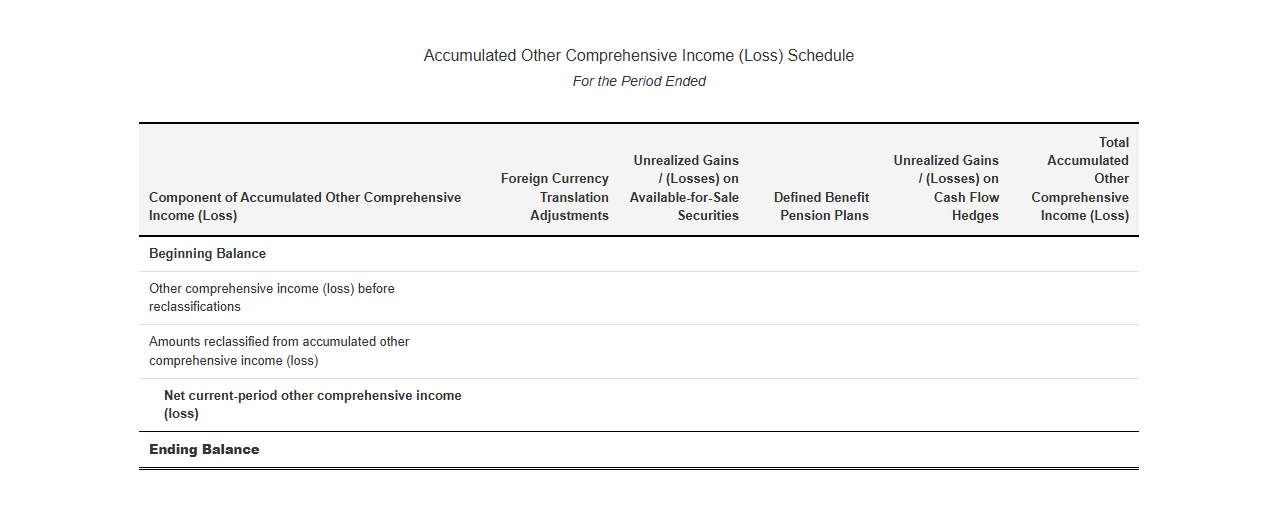
Accumulated Other Comprehensive Income and Loss Schedule
 Download: .PDF
Understanding Accumulated Other Comprehensive Loss in Financial Reporting
Accumulated Other Comprehensive Loss (AOCL) represents the collective balance of unrecognized gains and losses that bypass the traditional net income statement and are instead accumulated within the equity section of the balance sheet. This financial metric is highly significant because it houses transitional economic fluctuations that have not yet been realized through transactions. Streamlining the disclosure of AOCL is crucial for stakeholder clarity, as it prevents these complex, non-operational adjustments from obscuring a company's core operating performance while ensuring investors receive a complete picture of shareholders' equity.
Key Components Comprising Accumulated Other Comprehensive Loss
AOCL aggregates various unrealized economic events that must be tracked separately before they are eventually reclassified into net income. The primary components that constitute this balance include:
- Foreign currency translation adjustments: Gains and losses arising from the translation of foreign subsidiary financial statements into the parent company's reporting currency.
- Unrealized gains or losses on available-for-sale debt securities: Market value fluctuations of debt investments that are not held for active trading or held to maturity.
- Defined benefit pension plan adjustments: Unrecognized prior service costs, transition obligations, and actuarial gains or losses associated with employee retirement plans.
- Gains or losses on derivative instruments: The effective portion of cash flow hedges that are deferred in equity until the forecasted transaction impacts earnings.
Common Obstacles in Traditional AOCL Disclosure Methods
Many organizations struggle to present AOCL clearly due to fragmented data sources spread across multiple global subsidiaries. Gathering historical translation data, monitoring fluctuating debt securities, and reconciling complex actuarial pension reports often lead to manual accounting workarounds. These disjointed processes increase the risk of errors, create reconciliation delays, and frequently result in cluttered, non-standardized reports that confuse external stakeholders.
"The fragmented nature of non-owner equity adjustments often turns what should be a straightforward disclosure into a complex compliance puzzle, obscuring valuable financial insights from analysts."
The Strategic Advantages of Standardized Disclosure Templates
Implementing structured statement templates simplifies the internal reporting process by establishing a unified framework for data collection. This structural standardization significantly reduces compliance risks and improves audit efficiency. Because auditors can easily trace the flow of adjustments from the trial balance directly to the final disclosure, the time spent on validation is drastically minimized, freeing up valuable resources for accounting teams.
For external financial analysts and investors, standardized templates enhance comparability across different periods and peer companies. When complex equity adjustments are presented in a predictable, uniform format, analysts can quickly dissect the underlying drivers of comprehensive income. This transparent presentation builds market trust, reduces information asymmetry, and allows stakeholders to make more accurate valuations.
Design Principles for an Effective AOCL Statement Template
A high-quality AOCL template relies on a logical tabular layout that clearly separates current period activity from historical balances. It should feature explicit column headers for current and prior periods, enabling readers to track the roll-forward of each component from the beginning balance, through current-period other comprehensive income, to the ending balance. Additionally, incorporating explicit cross-referencing to specific footnote disclosures ensures that readers can easily locate the detailed calculations behind each summary figure.
Step-by-Step Integration of Templates into Corporate Financial Workflows
Transitioning to a standardized disclosure format requires a systematic approach to ensure data integrity and team alignment. Accounting teams must establish clear ownership over each data stream to avoid reporting bottlenecks during the close cycle.
Phase 1: ERP Data Mapping. Map individual ledger accounts and subsidiary databases directly to the standardized template fields to automate data ingestion.
Phase 2: Validation of Monthly Adjustments. Implement automated validation checks to verify that monthly currency translations, pension entries, and security valuations align with sub-ledger inputs.
Phase 3: Footnote Reconciliation. Cross-reference the template balances with corresponding footnote schedules to guarantee mathematical consistency.
Phase 4: Final Review and Filing. Conduct a final review cycle with senior management and internal auditors to sign off on the presentation before regulatory filing.
The Future of Comprehensive Income Reporting and Digital Standardization
The landscape of corporate reporting is rapidly evolving toward complete digital standardization. As regulatory bodies place greater emphasis on machine-readable financial statements, the interaction between streamlined disclosure templates and automated reporting systems becomes increasingly vital. Modern reporting software allows organizations to dynamically update their comprehensive income schedules in real time, reducing manual intervention and accelerating the close process.
This transition is heavily supported by the widespread adoption of inline XBRL (iXBRL) tagging. By embedding standardized tags directly into the HTML document, companies enable search engines, analysts, and regulators to instantly extract and compare AOCL data. This technological integration enhances market transparency and ensures that complex equity changes are readily accessible to all market participants.
Leave a comment