Financial analysts and investment committees constantly grapple with formula errors and structural inconsistencies that compromise the integrity of their valuation outputs. Historically, organizations tolerated the inefficiencies of bespoke, analyst-specific models; however, today's fast-paced market demands highly defensible and repeatable valuation frameworks.
Standardizing your Discounted Cash Flow (DCF) templates bridges this operational gap, granting teams immediate scalability and audit-ready precision. Crucially, a template is only as reliable as its baseline data; it serves as a structural safeguard rather than a substitute for rigorous strategic analysis. For instance, key variables-such as the Weighted Average Cost of Capital (WACC) and terminal growth rate assumptions-must still be meticulously calibrated to industry realities.
This article examines how standardized DCF frameworks mitigate manual errors, streamline multi-scenario sensitivity analyses, and ultimately elevate the accuracy of your organization's investment decisions.
Discounted Cash Flow Statement Template
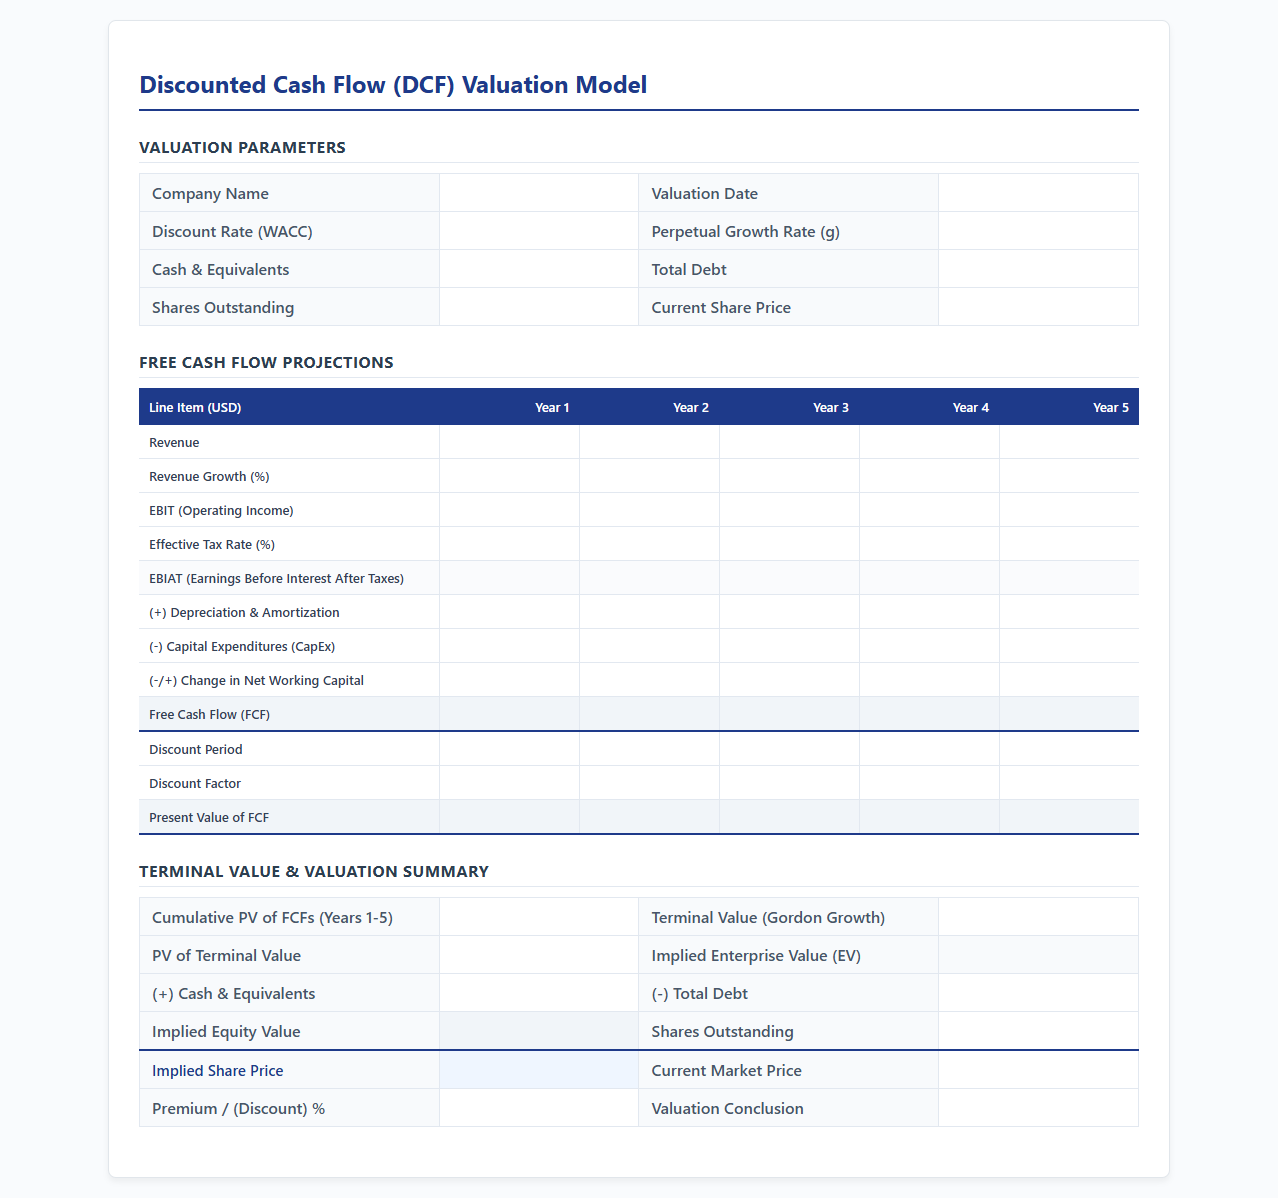 Download: .PDF
DCF Valuation Model Statement Template
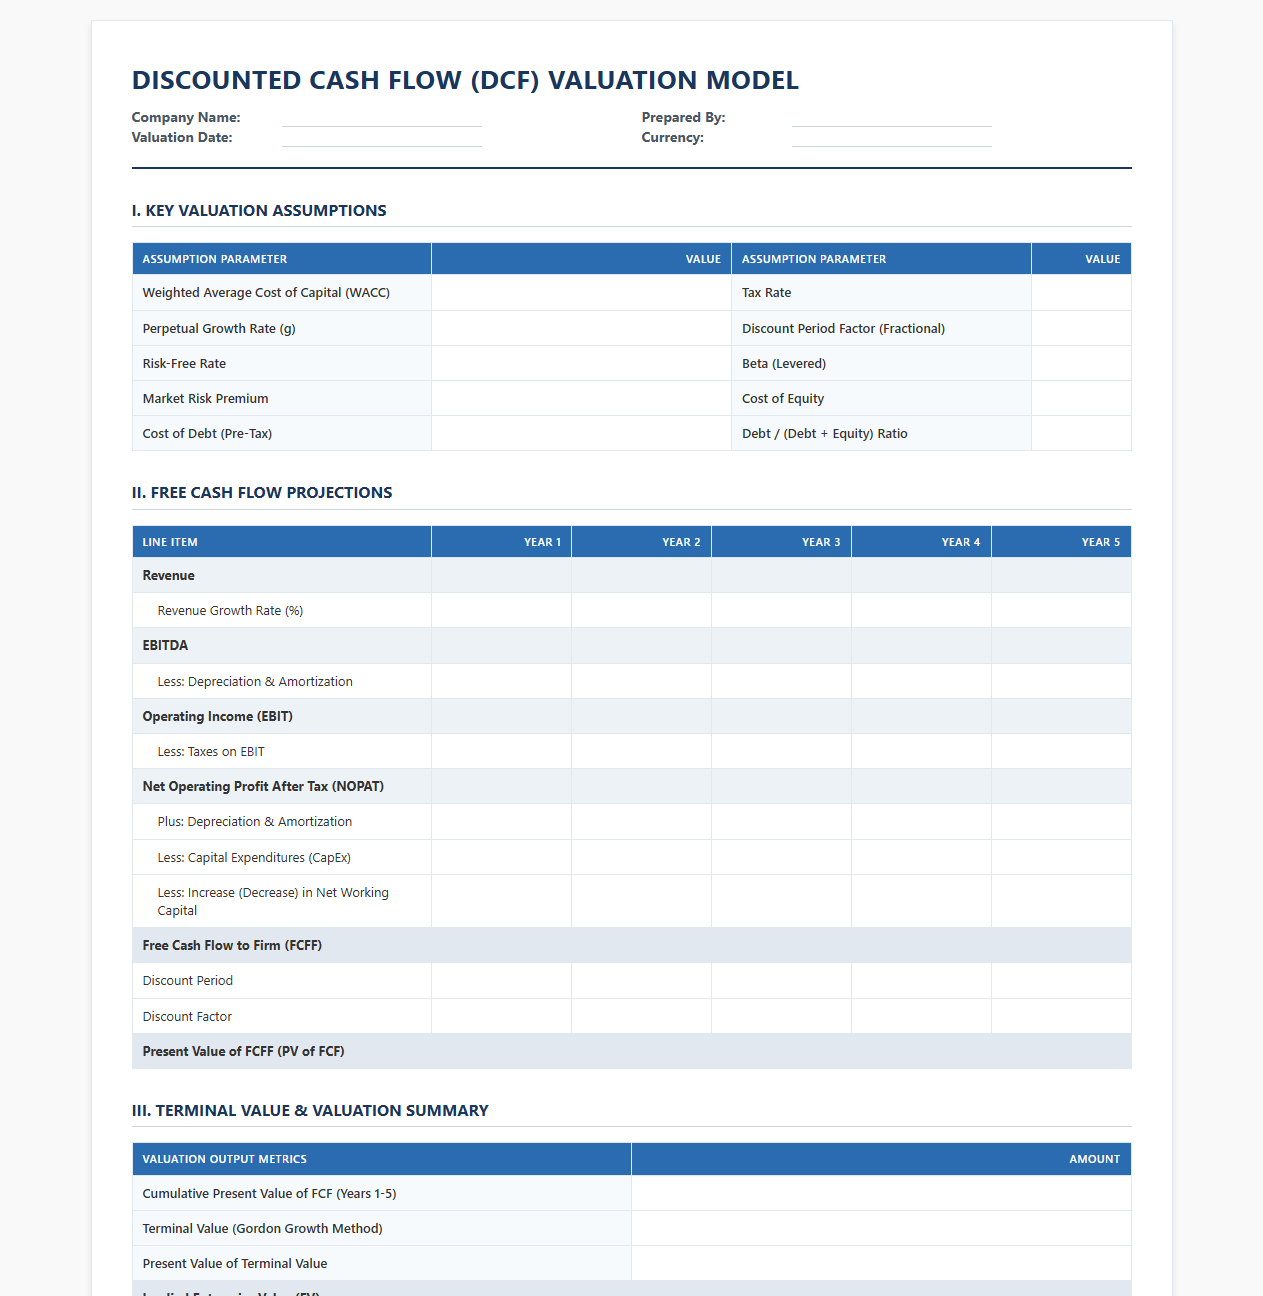 Download: .PDF
Cash Flow Discounting Financial Statement Template
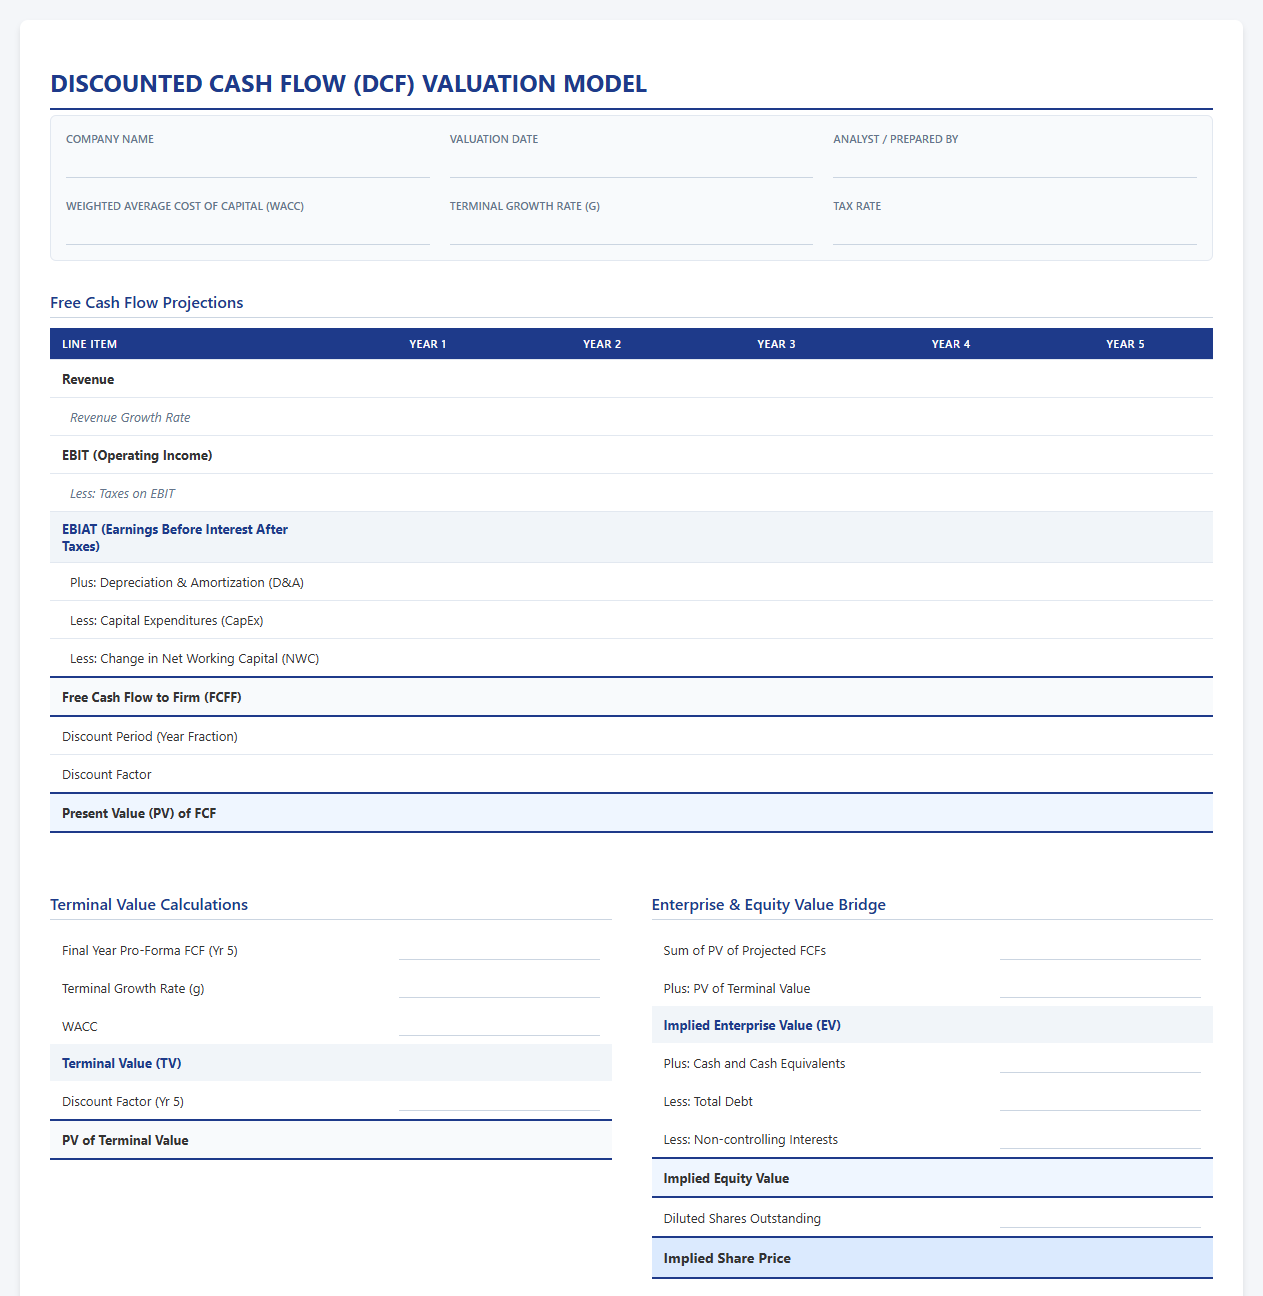 Download: .PDF
Discounted Cash Flow Analysis Statement Template
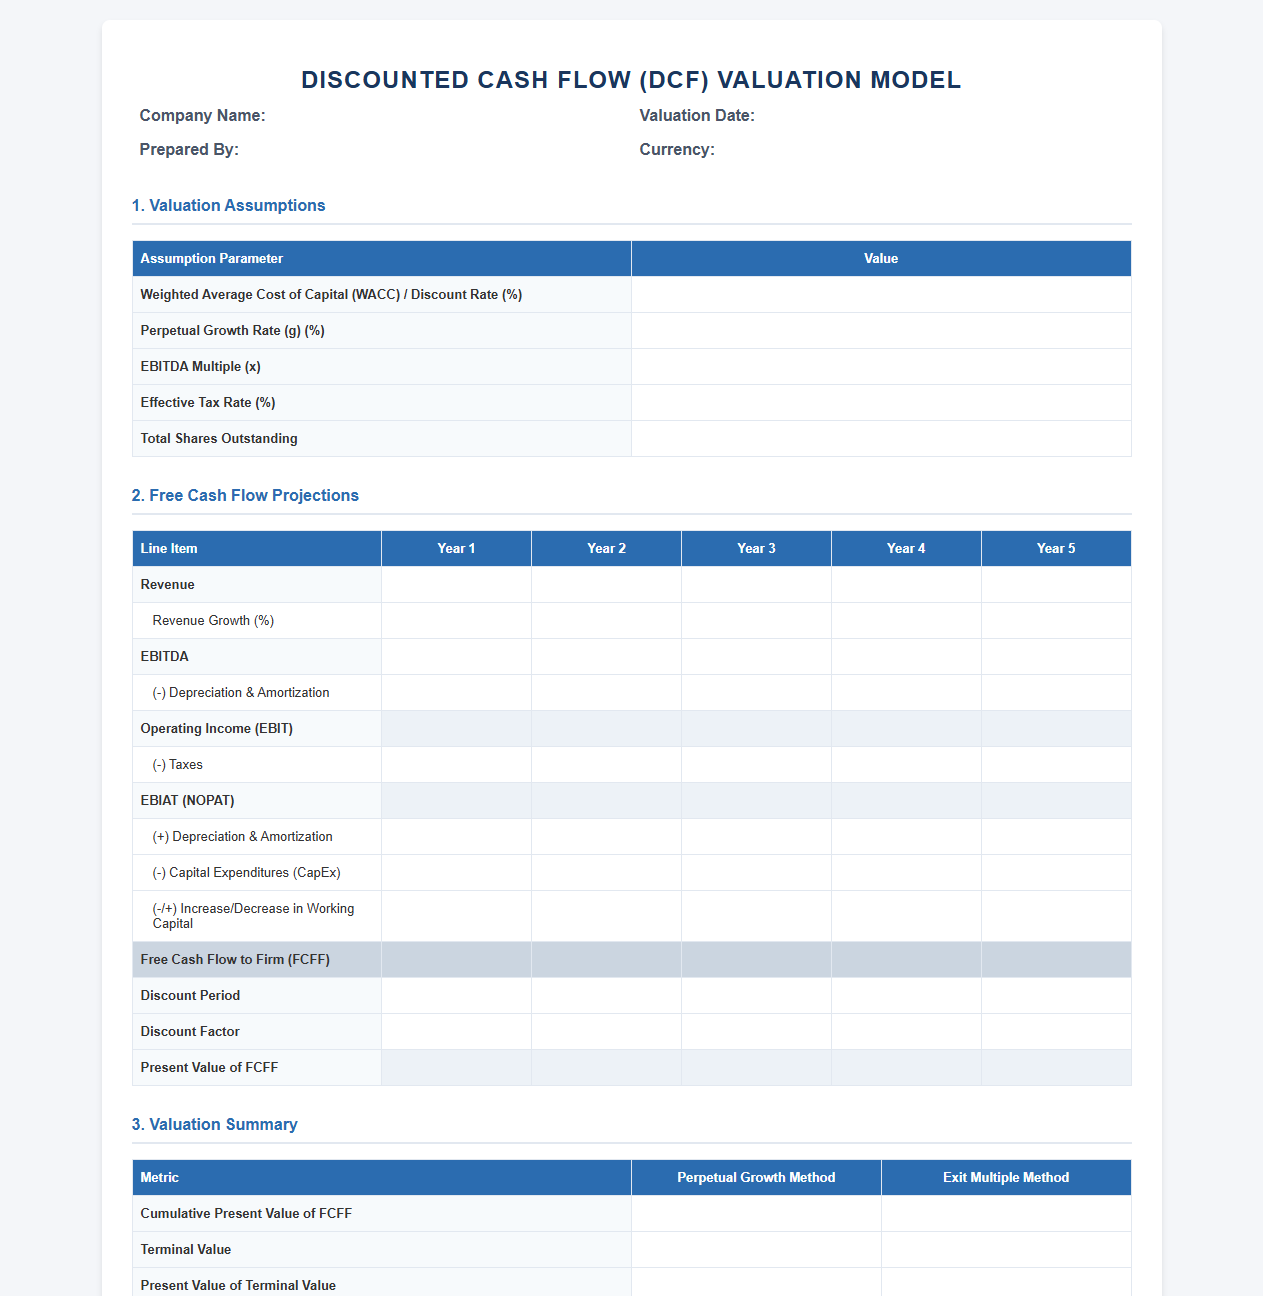 Download: .PDF
DCF Projections Financial Statement Template
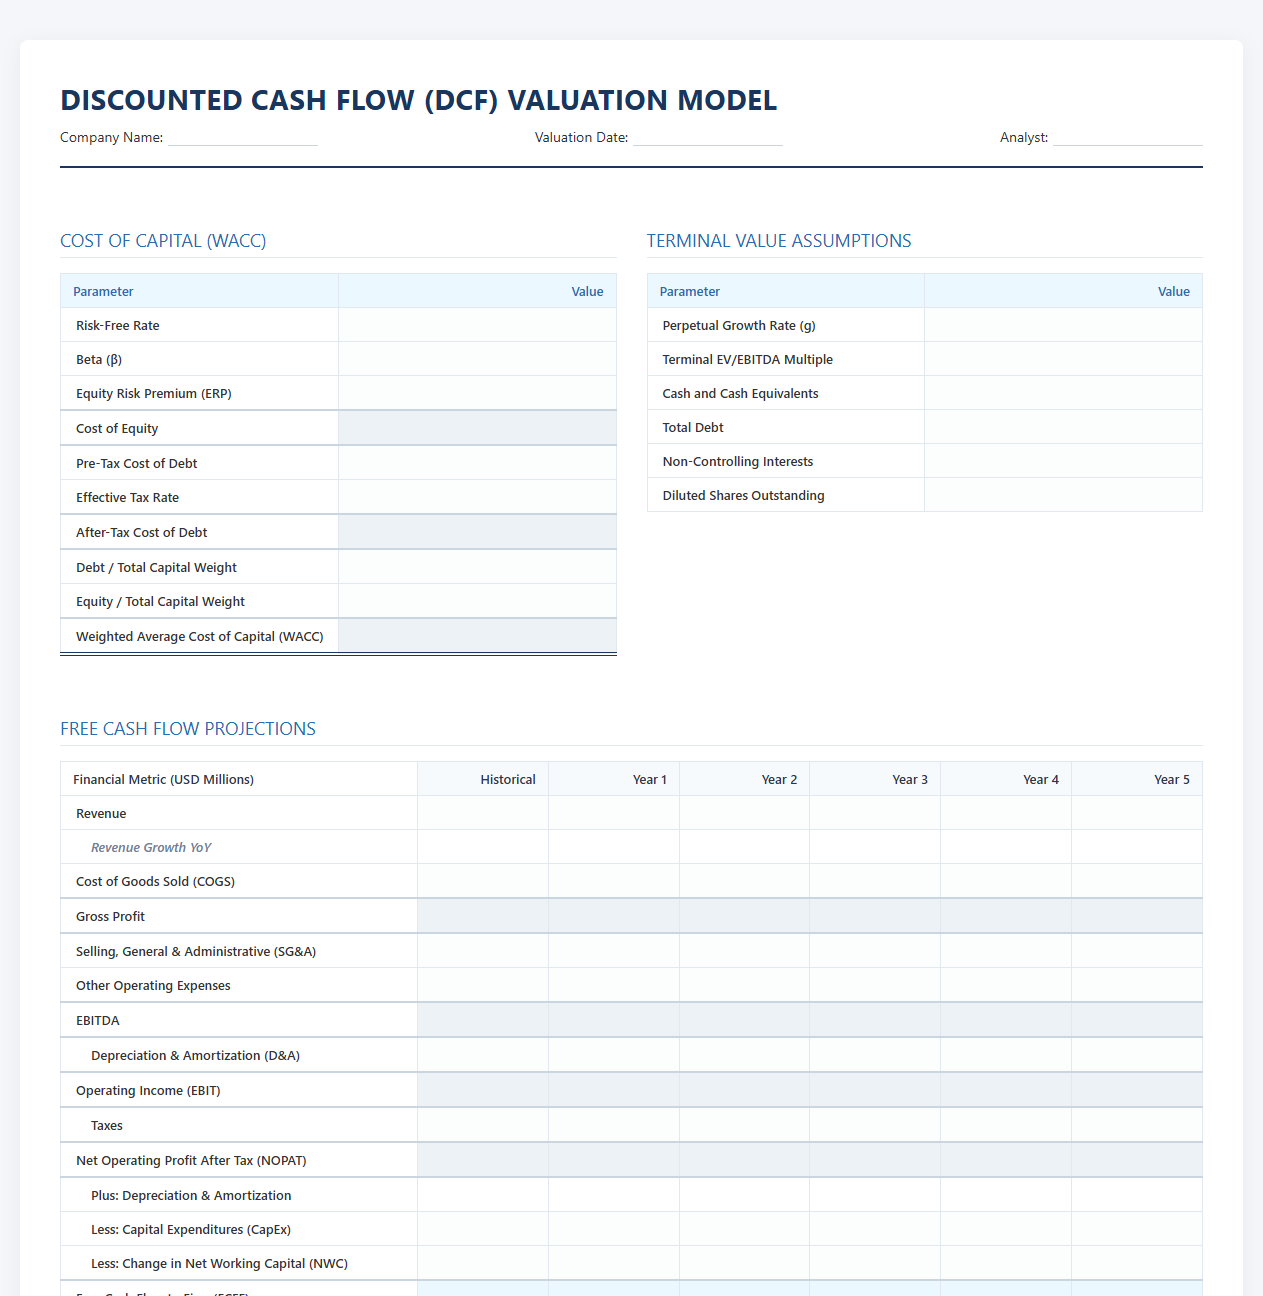 Download: .PDF
Discounted Cash Flow Valuation Spreadsheet Template
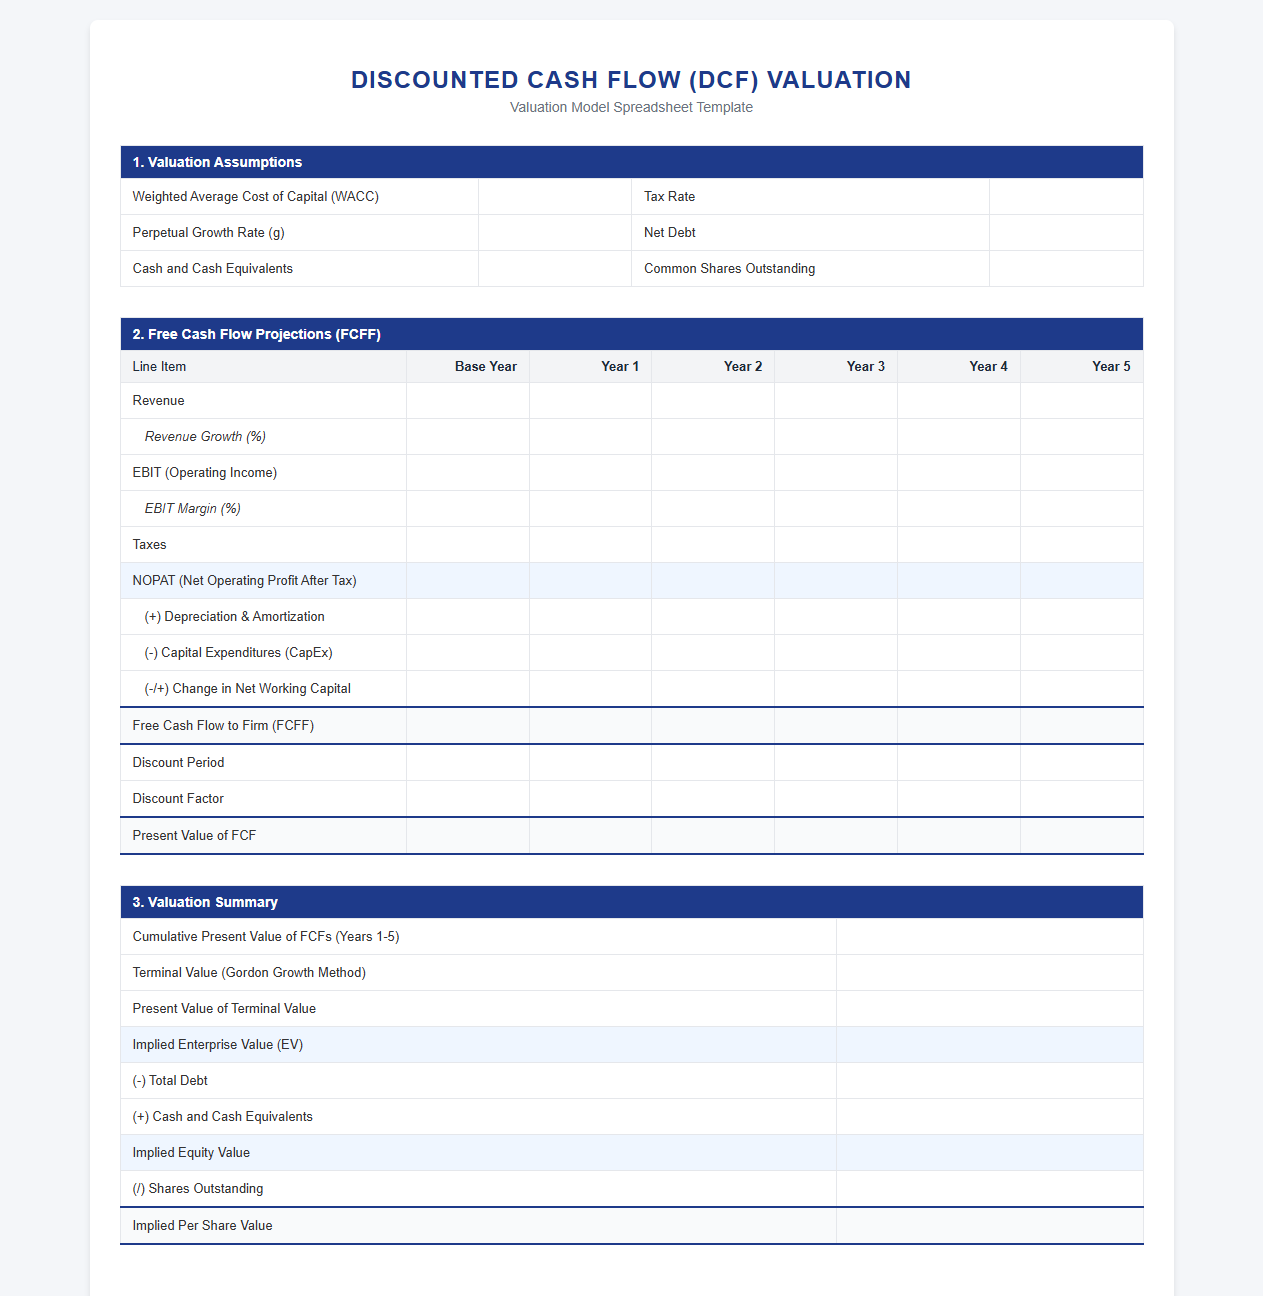 Download: .PDF
Free Cash Flow Discounting Statement Template
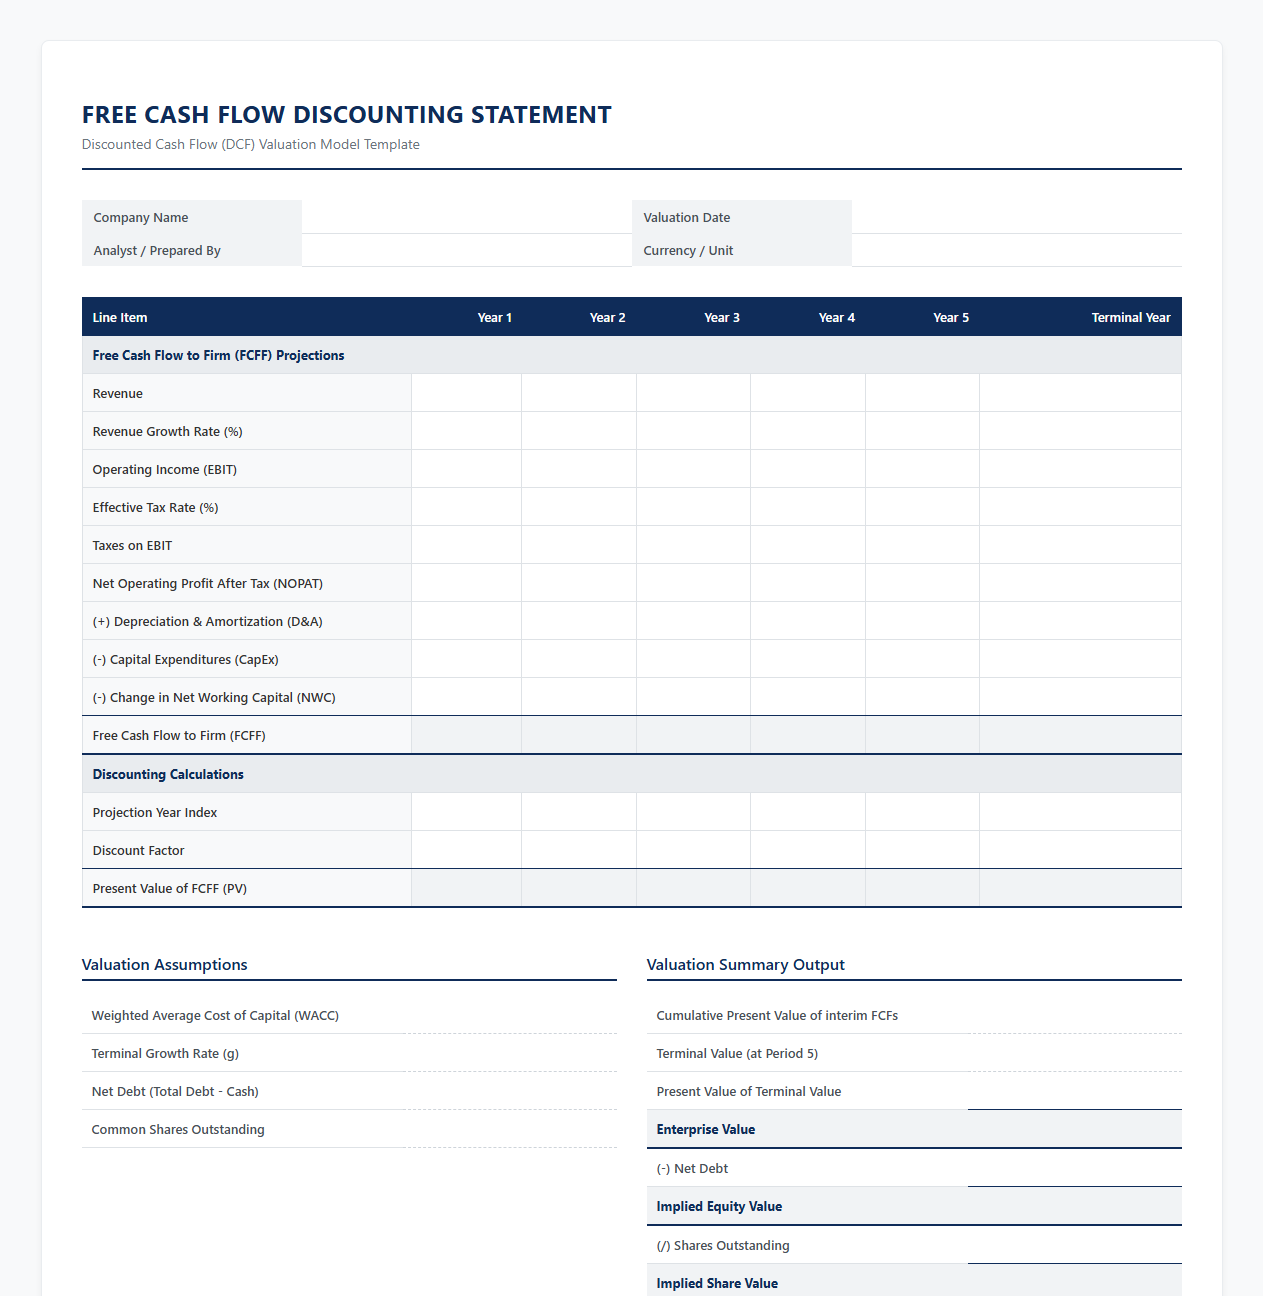 Download: .PDF
Discounted Cash Flow Forecast Statement Template
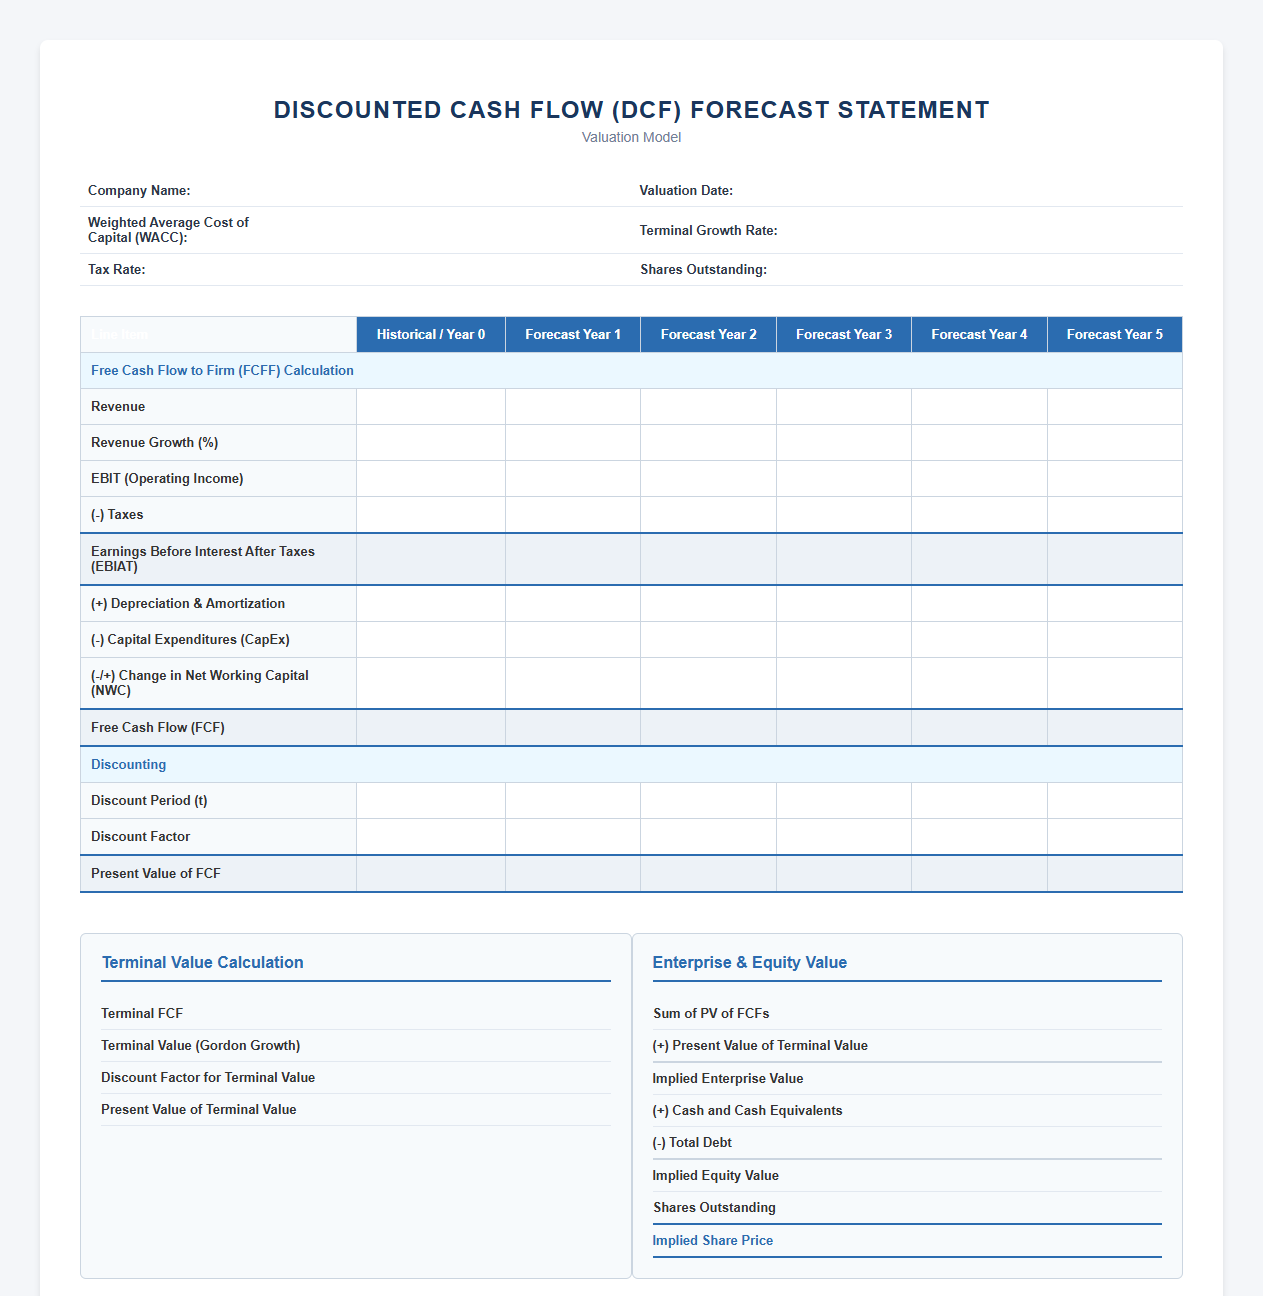 Download: .PDF
Business Valuation Discounted Cash Flow Template
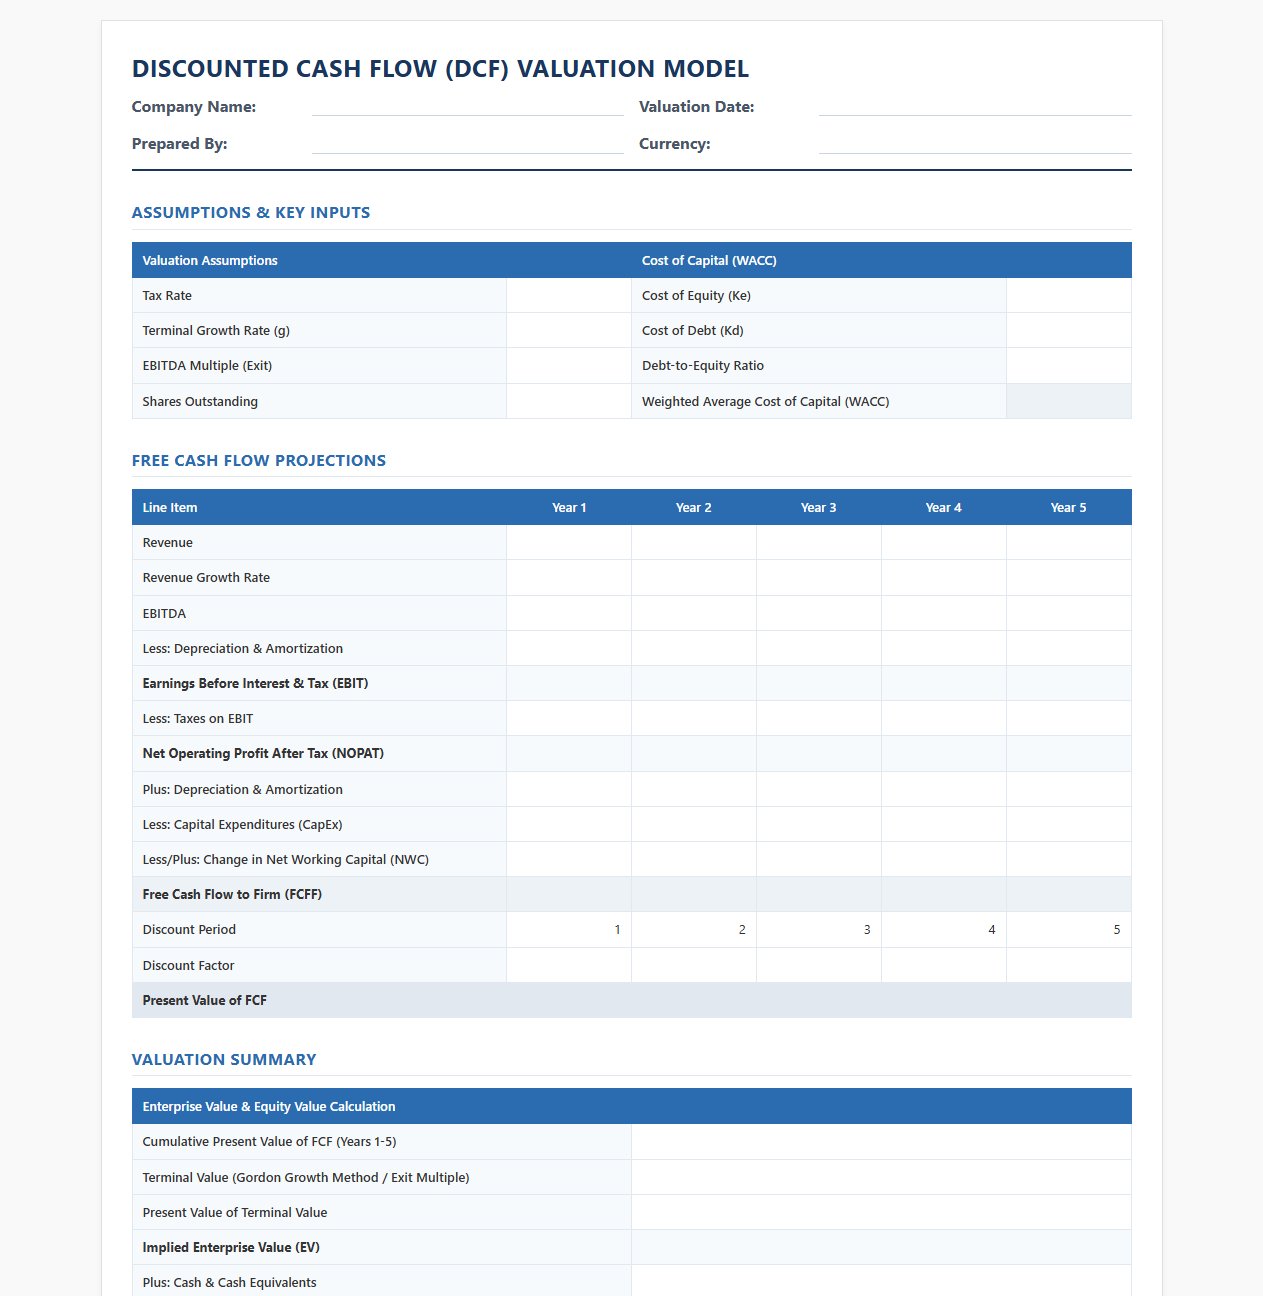 Download: .PDF
Introduction: The Imperative of Standardization in DCF Valuations
Discounted Cash Flow (DCF) analysis remains the gold standard for intrinsic valuation, yet its complexity makes it highly susceptible to manual errors. By utilizing a standardized DCF template, financial institutions can systematically reduce human error, align analytical assumptions, and dramatically improve the accuracy of investment decisions. This consistency ensures that analysts spend less time debugging broken cell references and more time evaluating strategic variables.
Implementing structured modeling frameworks delivers unrivaled valuation consistency, enhanced auditability for investors, and a scalable workflow that mitigates the risks of custom-built, error-prone spreadsheets.
Core Components of a Robust DCF Template
A highly functional DCF template must follow a logical and intuitive structural architecture. Separating inputs, calculations, and outputs is crucial for maintaining model integrity and allowing external reviewers to audit the valuation path seamlessly.
- Historical Financials Input Tab: Clean entry fields for three to five years of income statements, balance sheets, and cash flow statements.
- Assumption Driver Dashboard: A centralized control panel for revenue growth rates, operating margins, capital expenditure ratios, and working capital requirements.
- Free Cash Flow Calculation Engine: The core processing area where unlevered or levered cash flows are derived systematically.
- Discount Rate Calculator: A dedicated section for computing the weighted average cost of capital with transparent formula references.
- Terminal Value and Enterprise Value Summary: The final output section consolidating the present value of discrete cash flows and terminal value to derive equity value per share.
Standardizing Free Cash Flow (FCF) Projections
Standardizing the calculation of cash flows is essential to prevent analysts from omitting critical capital adjustments. Free Cash Flow to Firm (FCFF) measures the cash available to all capital providers, while Free Cash Flow to Equity (FCFE) measures the cash available solely to equity shareholders. Standard templates must enforce a strict, step-by-step calculation sequence to maintain analytical rigor.
- Start with Operating Income (EBIT) and deduct calculated taxes to arrive at Net Operating Profit After Tax (NOPAT).
- Add back non-cash charges, such as Depreciation and Amortization (D&A), which are historically deducted but do not represent actual cash outflows.
- Subtract Capital Expenditures (CapEx) to account for ongoing investments in property, plant, and equipment.
- Adjust for changes in Net Working Capital (NWC) by evaluating differences in operating assets and liabilities.
- For FCFE calculations, add net borrowing (debt issued minus debt repaid) to reflect cash flows available strictly to equity holders.
Establishing Consistency in WACC and Discount Rate Assumptions
The discount rate is one of the most sensitive variables in a DCF model. Without strict standardization, analysts may manipulate inputs to justify biased valuation targets. A robust template hardcodes the mathematical relationships governing the Weighted Average Cost of Capital (WACC), forcing consistency across cost of equity and cost of debt parameters.
To eliminate subjective distortion, templates should pre-define key formulas. For instance, Beta (β) must be systematically calculated using a consistent historical period and benchmark index to measure a security's systematic risk relative to the market. Similarly, the Risk-Free Rate (Rf) should be anchored to a standardized government bond yield matching the currency of the cash flows, while the Market Risk Premium (MRP) should rely on institutionalized long-term historical averages rather than ad-hoc estimates.
Normalizing Terminal Value Methodologies
A significant portion of a company's total intrinsic value is captured in its terminal value. Standardizing the calculation of this long-term horizon prevents exaggerated growth assumptions. Templates should run both the Perpetuity Growth Method and the Exit Multiple Method in parallel to serve as sanity checks against one another.
| Valuation Method | Core Assumptions | Primary Use Case | Template Safeguards |
|---|---|---|---|
| Perpetuity Growth Method | Constant long-term growth rate, normalized reinvestment rate. | Stable, mature companies in predictable industries. | Cap growth rate at long-term GDP growth (typically 2-3%). |
| Exit Multiple Method | Target EV/EBITDA or EV/Revenue multiple at the end of the forecast period. | Cyclical businesses or industries with active M&A activity. | Anchor multiples to historical industry peer averages. |
Risk Mitigation through Built-in Template Controls
Financial models are highly volatile assets when distributed across multiple teams. Standardized DCF templates must incorporate automated audit checks to ensure mathematical integrity. Integrating error-trapping formulas like IFERROR, balancing checks to ensure the balance sheet reconciles, and implementing cell locking on core formulas prevent accidental formula overwriting and model breakage.
Conclusion: Best Practices for Organization-Wide Template Adoption
Deploying a standardized DCF template requires continuous governance, training, and version control. Financial institutions should designate a centralized modeling committee to review, update, and lock master files. Regular audits of active models ensure compliance with standard corporate finance methodologies, ensuring that investment decisions are backed by rigorous, standardized data structures rather than fragmented individual preferences.
For template updates, user guides, or to report modeling anomalies, contact:Financial Modeling Governance Committee
Email: governance@valuationstandards.corp
Internal Location: HQ-Floor 12, Rev-Control Group
Leave a comment