Tax practitioners and corporate finance teams constantly battle the anxiety of regulatory audits, scope creep, and costly compliance errors during peak seasons. As global tax codes grow increasingly intricate each year, relying on informal agreements or outdated contract language is no longer a viable risk-management strategy.
Establishing robust, standardized agreement templates grants firms the operational clarity and legal protection needed to safeguard profit margins. For instance, incorporating precise clauses that define the exact scope of "annual compliance services"-such as specifying corporate filing preparation while explicitly excluding ongoing audit representation-serves as concrete proof of alignment. However, while these templates provide a powerful baseline, they must be treated as living documents that require tailoring to specific jurisdictional regulations.
This article will explore the essential components of tax compliance agreements, examine industry-standard templates, and outline best practices for minimizing professional liability.
Annual Tax Compliance Services Agreement Template
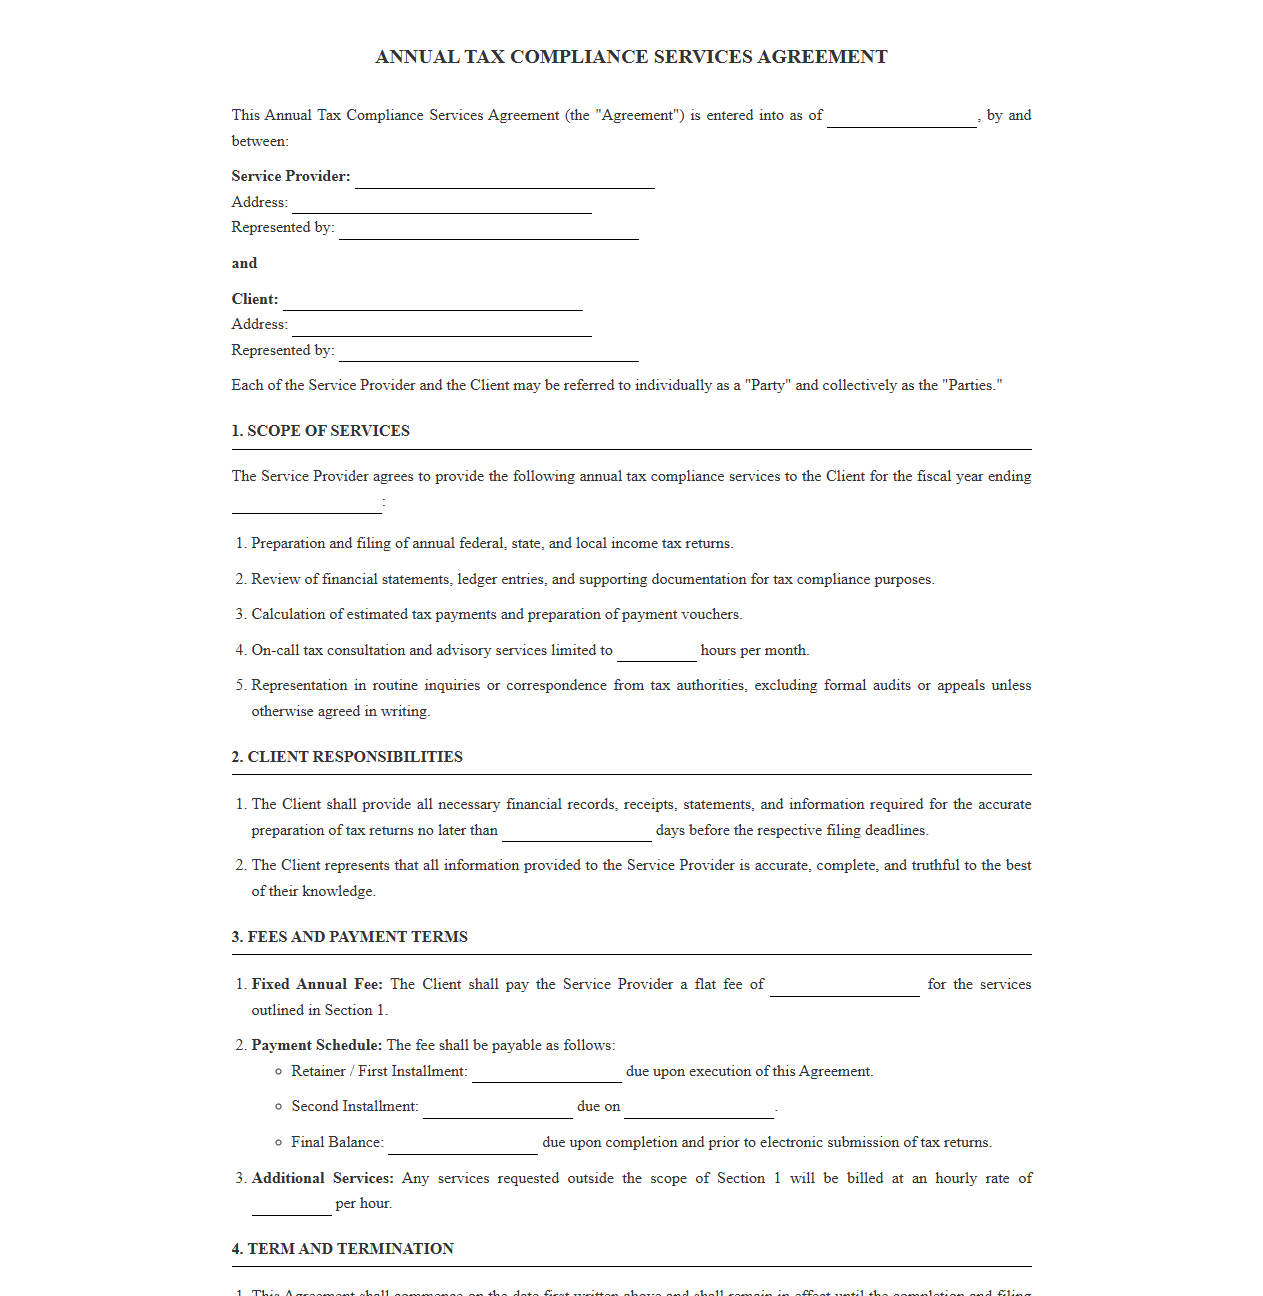 Download: .PDF
Year-End Tax Compliance Engagement Letter Template
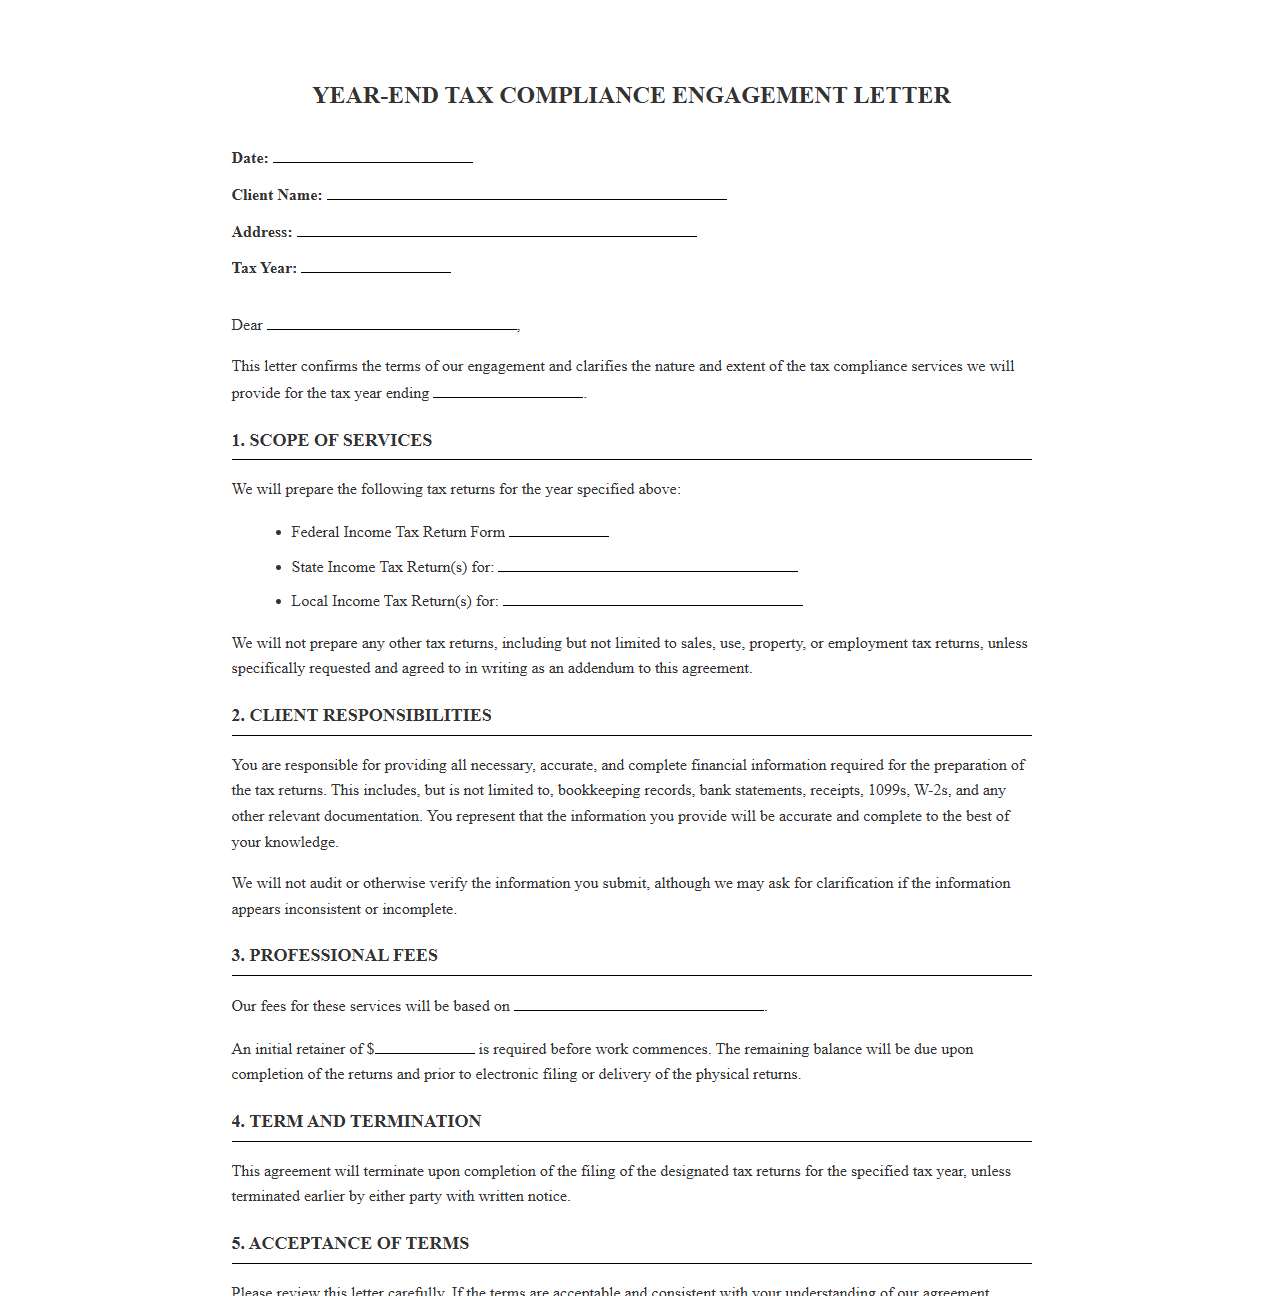 Download: .PDF
Recurring Annual Tax Filing and Compliance Contract
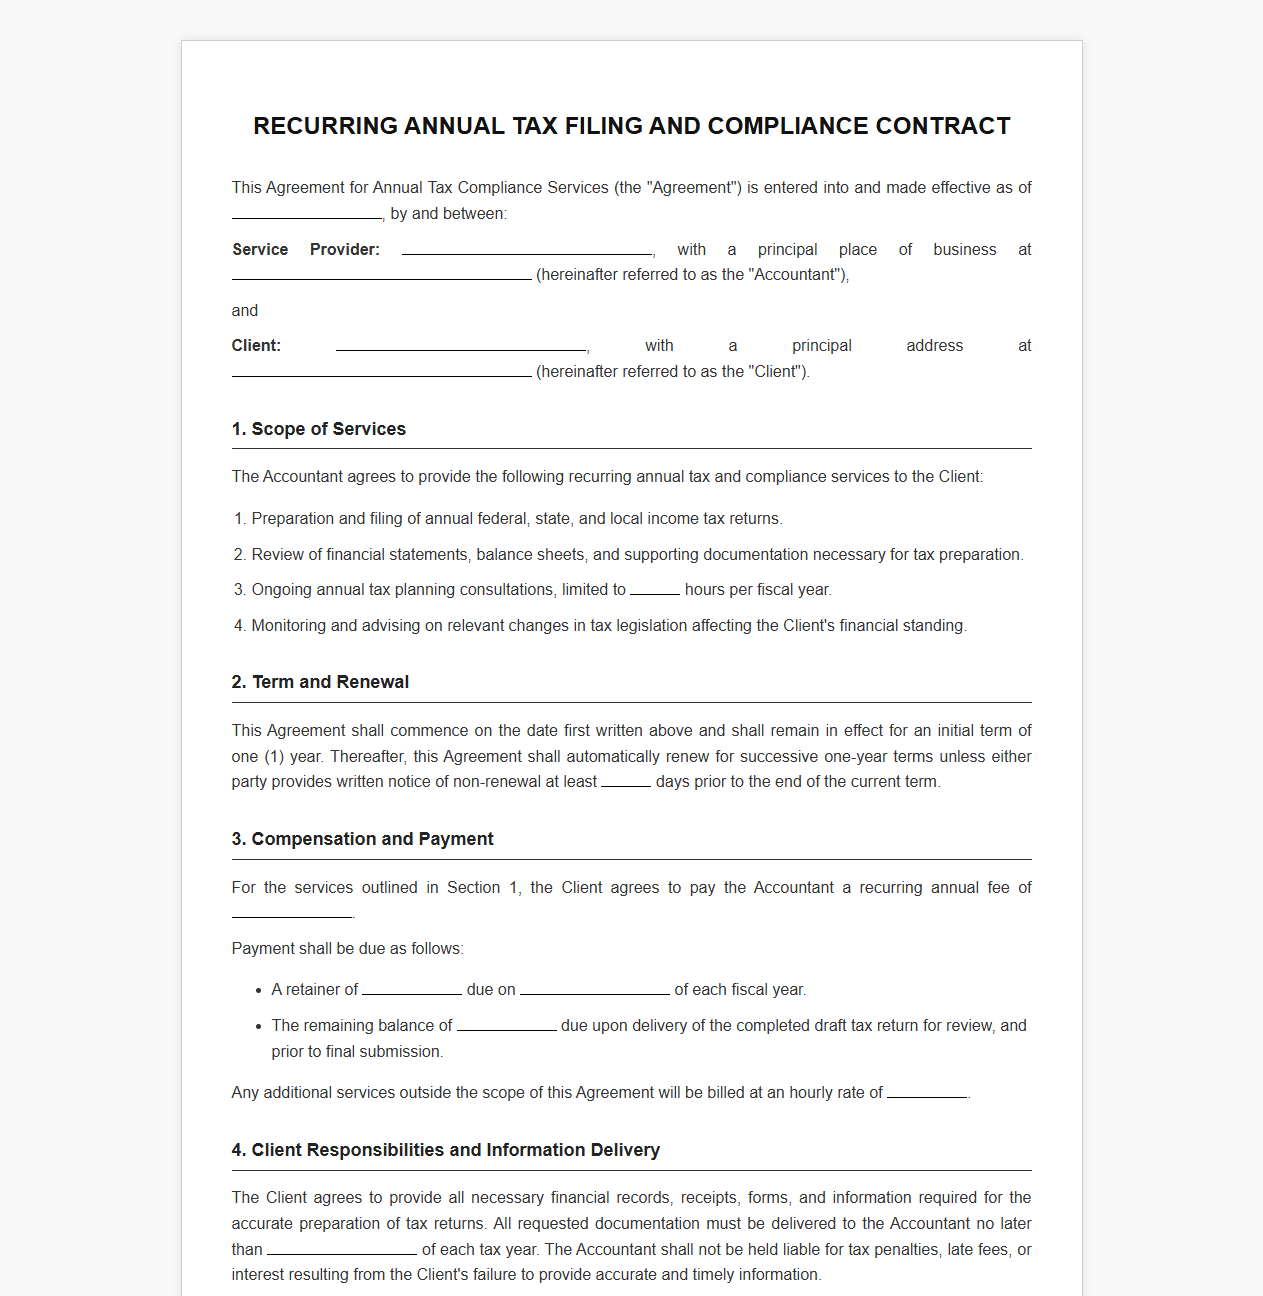 Download: .PDF
Annual Tax Preparation and Compliance Service Agreement
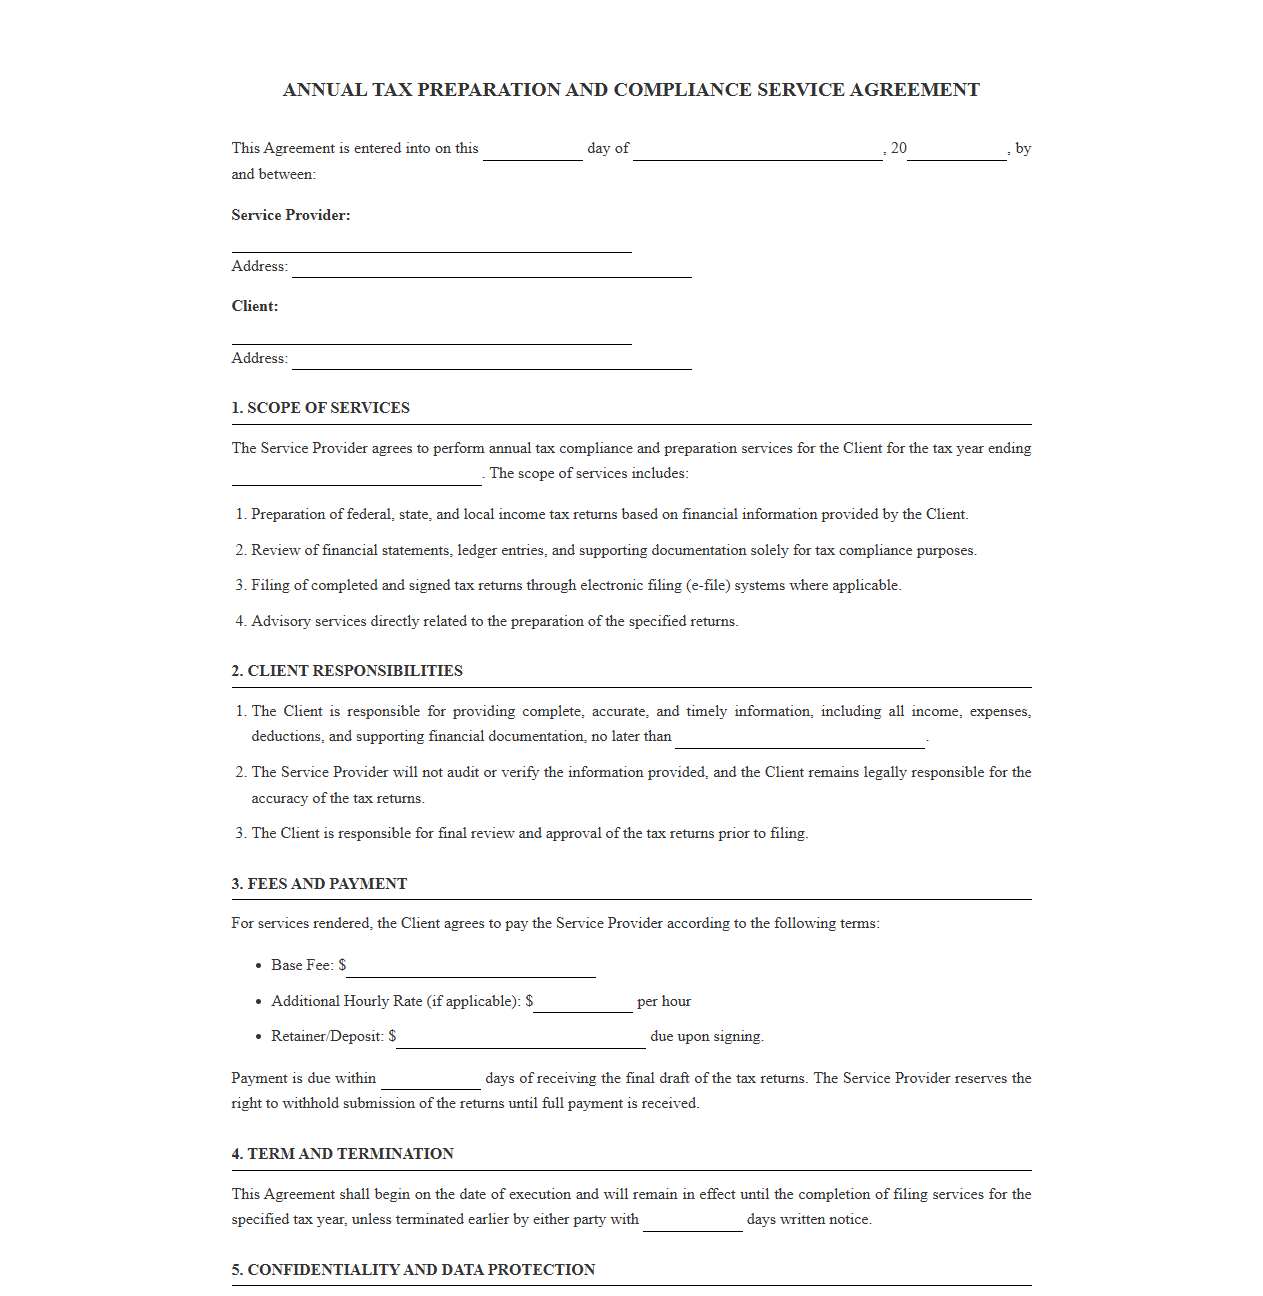 Download: .PDF
Corporate Annual Tax Compliance Service Contract Template
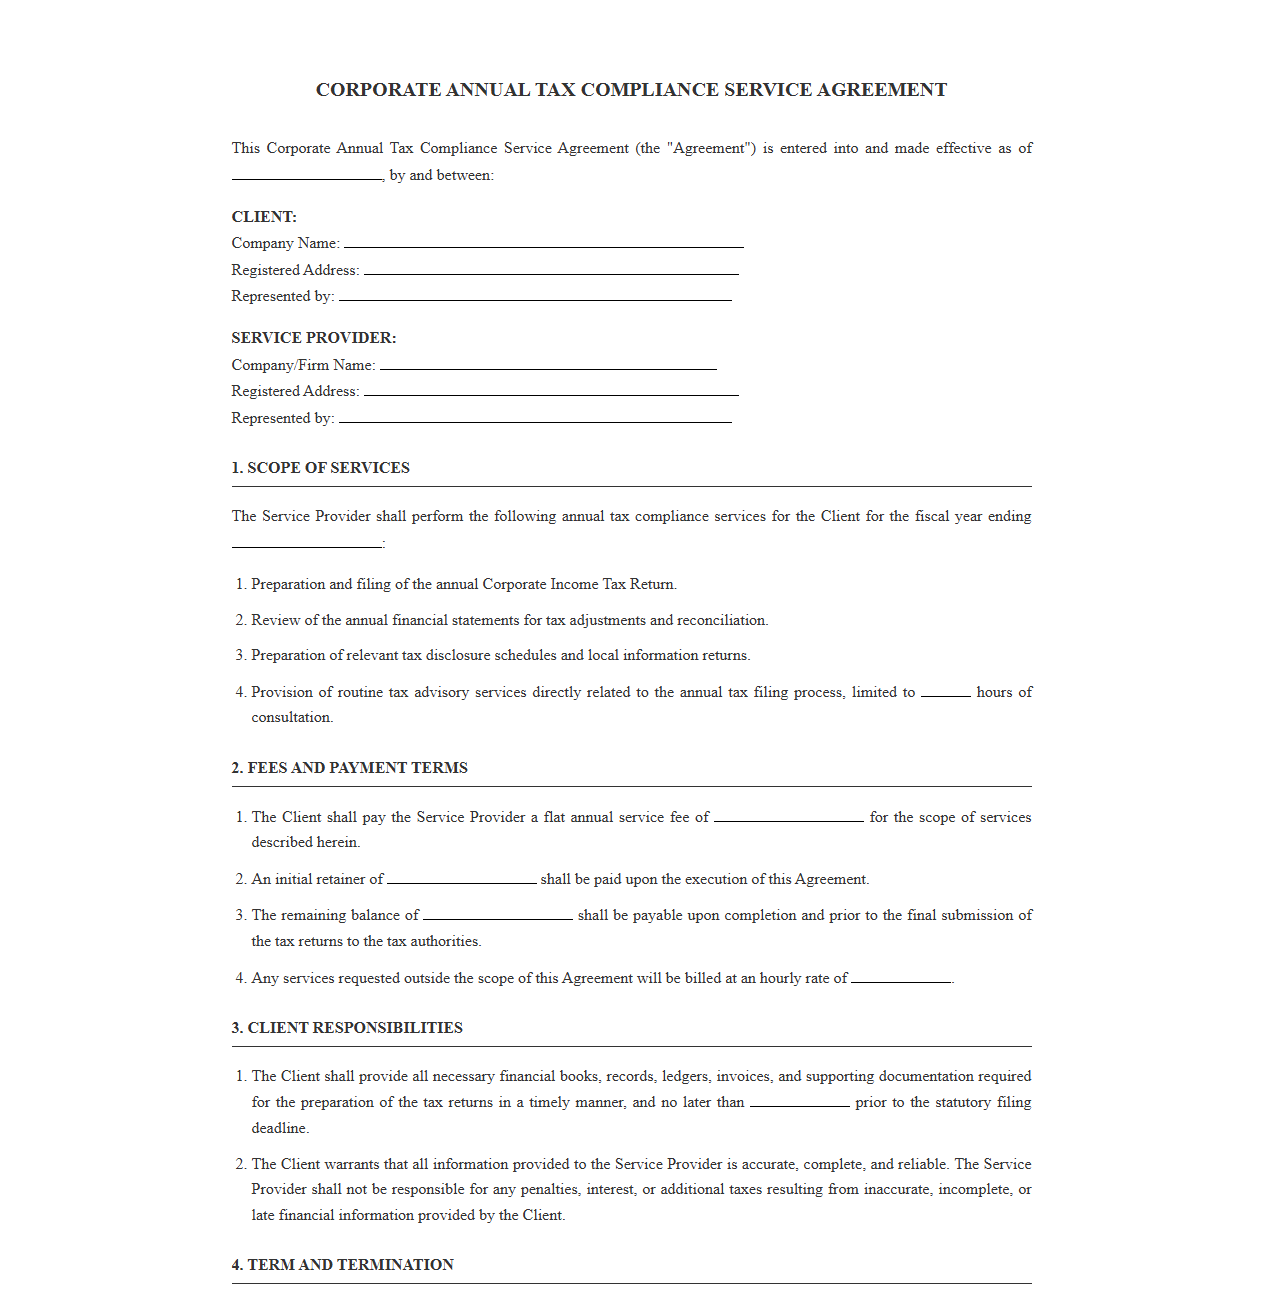 Download: .PDF
Master Agreement for Annual Tax Compliance Services
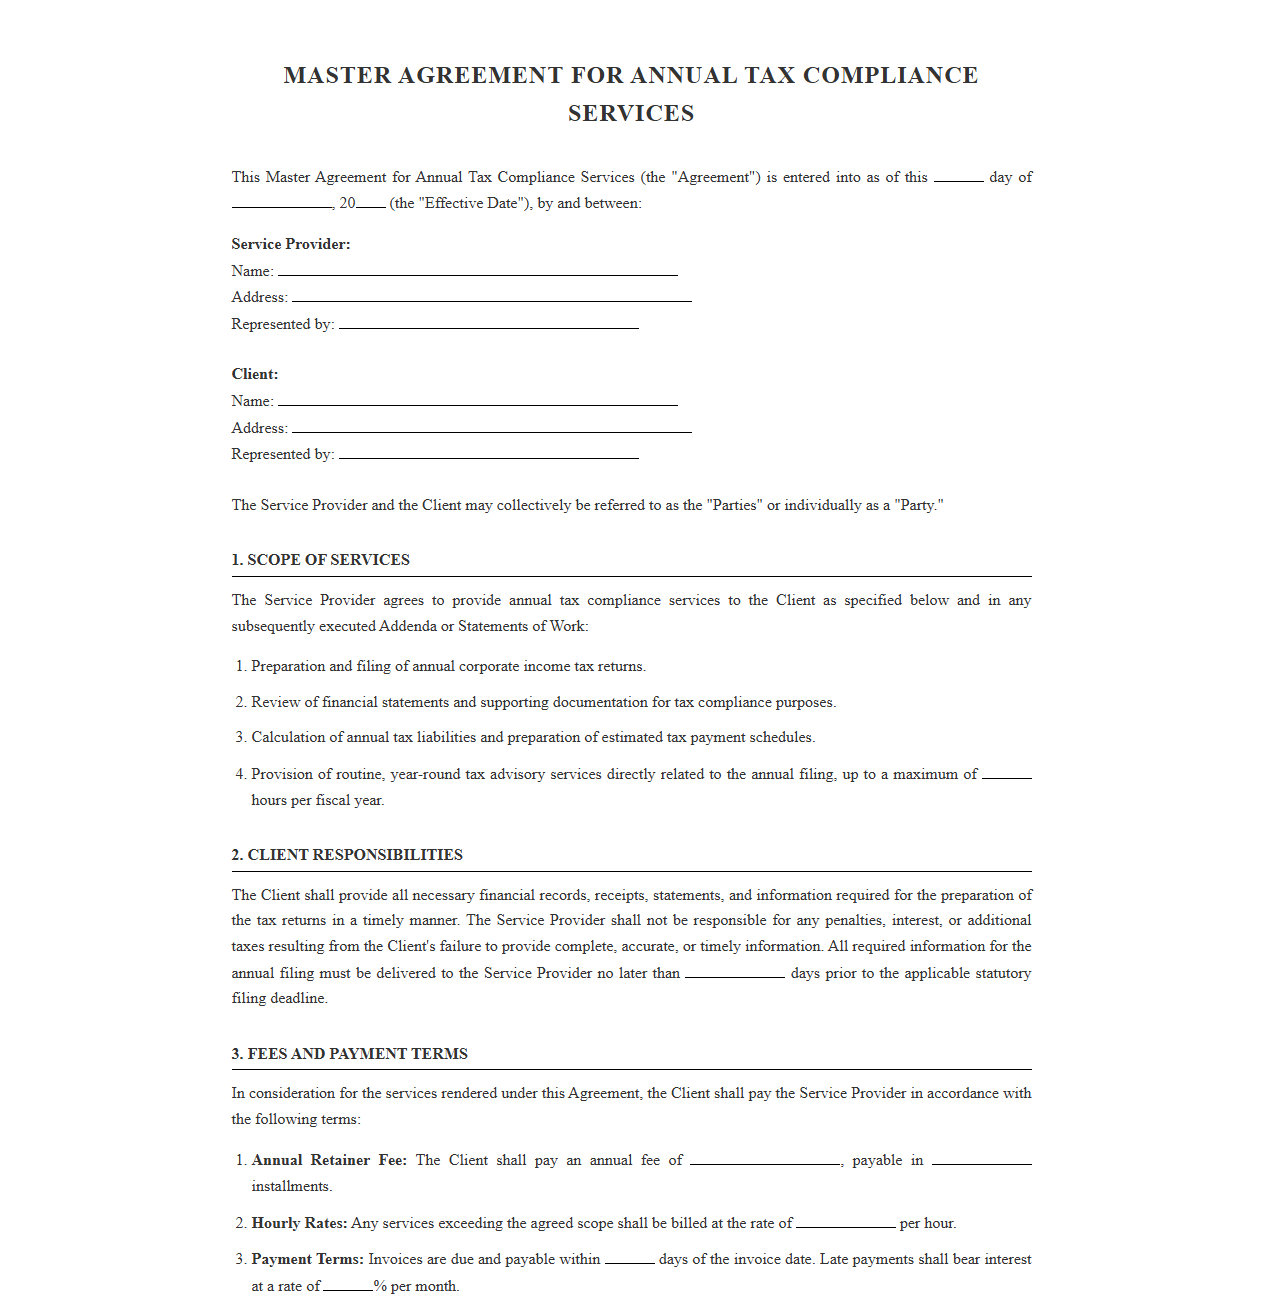 Download: .PDF
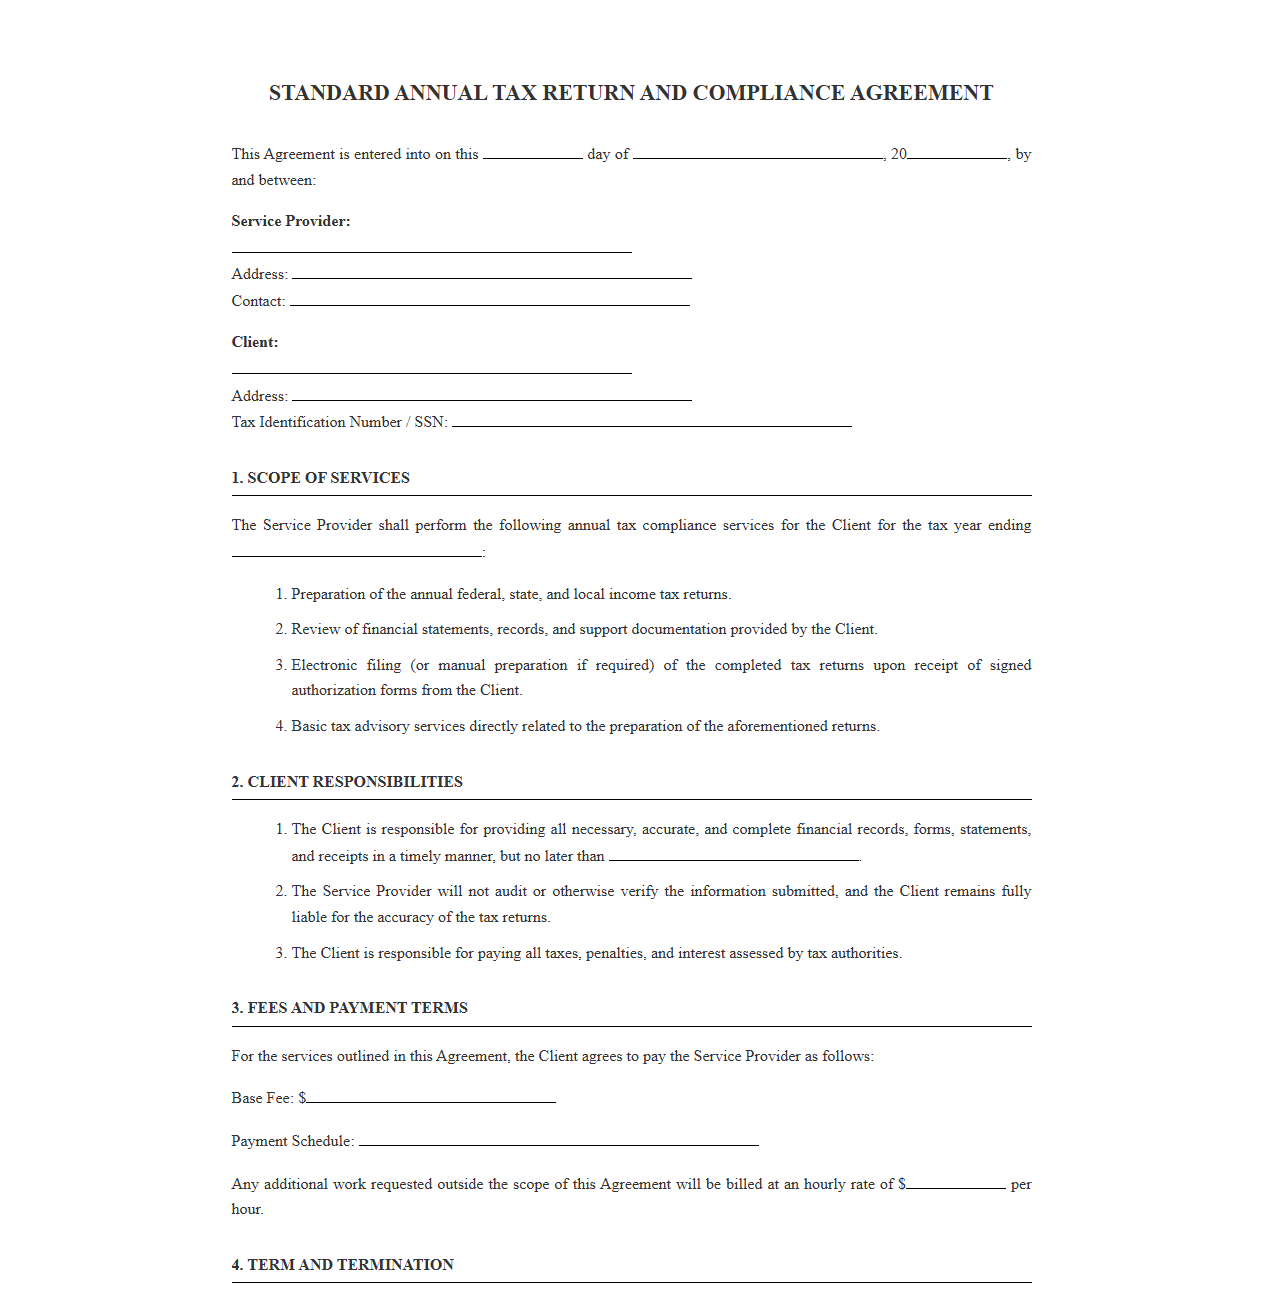
Standard Annual Tax Return and Compliance Agreement
 Download: .PDF
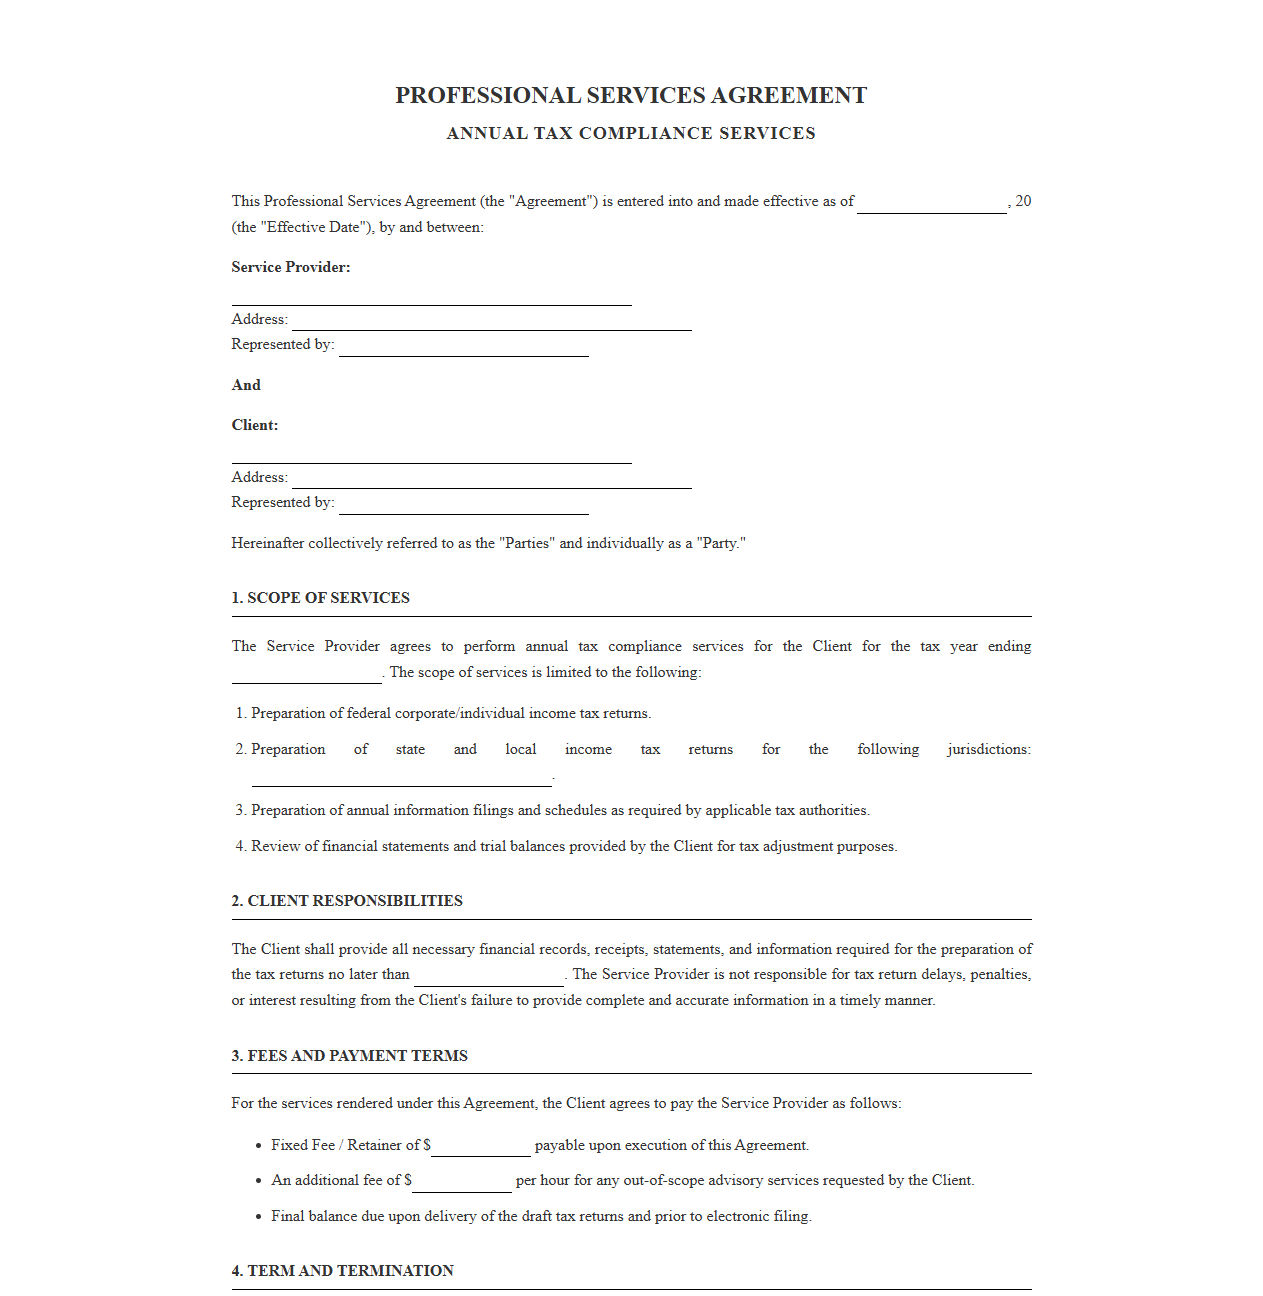
Professional Services Agreement for Annual Tax Compliance
 Download: .PDF
Navigating the Modern Landscape of Corporate Tax Risks
The global regulatory environment is shifting at an unprecedented pace. Each year, tax authorities introduce intricate amendments, digital reporting requirements, and aggressive enforcement strategies that catch even the most diligent enterprises off guard. Navigating these annual updates has become a high-stakes challenge for businesses of all sizes.
Operating without a clear strategy in this volatile environment exposes organizations to massive operational vulnerabilities. Unprecedented compliance risks emerge when internal teams fail to interpret complex legislative changes correctly. Failing to adapt leads to costly audits, severe financial penalties, and long-term reputational damage, making proactive risk management an absolute necessity for modern corporations.
The Strategic Value of Robust Compliance Agreements
In an era of intense regulatory scrutiny, a formal annual compliance service agreement serves as a vital protective barrier. This document establishes a clear mutual understanding, functioning as a shield against potential financial penalties and protracted legal disputes. By detailing the exact parameters of the engagement, both tax professionals and their clients can operate with absolute certainty and peace of mind.
A well-structured agreement does not merely outline tasks; it mitigates friction. For tax advisors, it prevents scope creep and unwarranted liability claims. For clients, it guarantees a dedicated level of service and ensures that their tax filings are handled in strict accordance with the latest statutory deadlines, keeping operational risks to a bare minimum.
Essential Clauses: Defining Scope and Liability Limits
A legally sound tax compliance contract must contain precise, unambiguous provisions that govern the relationship. Without these protective mechanisms, both parties remain vulnerable to misunderstandings and financial exposure.
Every professional service agreement should incorporate the following fundamental clauses:
- Scope of Work: A detailed breakdown of the exact tax returns, filings, and advisory services included in the annual fee.
- Limitation of Liability: A clause restricting the advisor's maximum financial exposure to a specified cap, typically equal to the fees paid under the contract.
- Indemnification: Protection for the tax firm against third-party claims resulting from inaccurate or falsified data provided by the client.
By establishing these boundaries early, you protect your firm's profitability and set realistic expectations for the client from day one.
Clarifying Roles: Client Responsibilities vs. Advisor Obligations
A successful tax compliance engagement relies on active cooperation and open communication. It is crucial to define where the advisor's work begins and where the client's duties end to avoid missed deadlines and compliance failures.
The operational framework of the engagement is managed through a balanced division of obligations:
- The client must provide accurate, complete, and fully reconciled financial documentation.
- All necessary records and source documents must be delivered to the advisor in a timely manner, well ahead of statutory filing deadlines.
- The advisor is obligated to review the provided information, apply relevant tax laws diligently, and prepare the required filings.
- The advisor must alert the client to potential tax risks identified during the preparation process.
When both parties adhere to this structured workflow, the likelihood of errors, late filings, and audits drops significantly.
Safeguarding Sensitive Financial Data and Confidentiality
Tax preparation involves handling highly sensitive financial data, intellectual property, and proprietary business structures. Modern service agreements must address the realities of cybersecurity threats and strict data protection laws.
"The parties agree to maintain strict confidentiality regarding all financial records, trade secrets, and personal information shared during the course of this engagement, implementing industry-standard security measures to prevent unauthorized access."
Incorporating robust non-disclosure agreements (NDAs) and privacy compliance clauses protects the integrity of both businesses. Secure data transmission protocols and clear policies on data retention and destruction help ensure compliance with modern data protection regulations, fostering deeper trust between the advisor and the client.
Establishing Clear Dispute Resolution and Termination Pathways
Even the strongest professional relationships can encounter friction, whether due to fee disagreements, service delays, or differing interpretations of tax regulations. Establishing a clear roadmap for resolving conflicts prevents minor issues from escalating into expensive court battles.
To maintain order during a disagreement, the contract should outline these specific procedures:
- An initial negotiation phase where senior representatives from both sides meet to resolve the issue amicably.
- A mandatory mediation clause requiring a neutral third party to facilitate discussions before any litigation can be initiated.
- A structured termination clause outlining the notice period required to end the contract and how unfinished work will be billed and transitioned.
These preemptive steps save time, protect financial resources, and allow both organizations to part ways professionally if the partnership is no longer viable.
Best Practices for Customizing and Deploying Your Templates
Having a master template is only the first step. To maximize efficiency, tax firms must tailor their compliance agreements to fit different client profiles, distinguishing between small startups and complex multinational corporations.
When deploying these contracts, firms should leverage digital signature platforms and automated client onboarding systems. This reduces administrative bottlenecks and speeds up the signing process.
Systematically updating and digitizing your agreements ensures your practice remains compliant, modern, and highly scalable.
Leave a comment