Managing long-term pension liabilities often leaves corporate finance teams drowning in complex, fragmented spreadsheets, where a single formula error can lead to compounding valuation discrepancies. Before implementing a digital solution, organizations must first navigate a shifting regulatory landscape where intense audit scrutiny makes absolute transparency paramount.
Utilizing specialized pension payable ledger templates grants accounting teams the structured precision needed to maintain flawless compliance. While these templates excel at organizing concrete daily metrics-such as employer contribution schedules and defined benefit obligations-it is important to note they are designed to streamline internal tracking rather than replace certified actuarial valuations.
This article will demonstrate how to deploy these specialized ledgers to eliminate manual entry errors, manage complex amortization schedules, and build a bulletproof audit trail for fiscal accuracy.
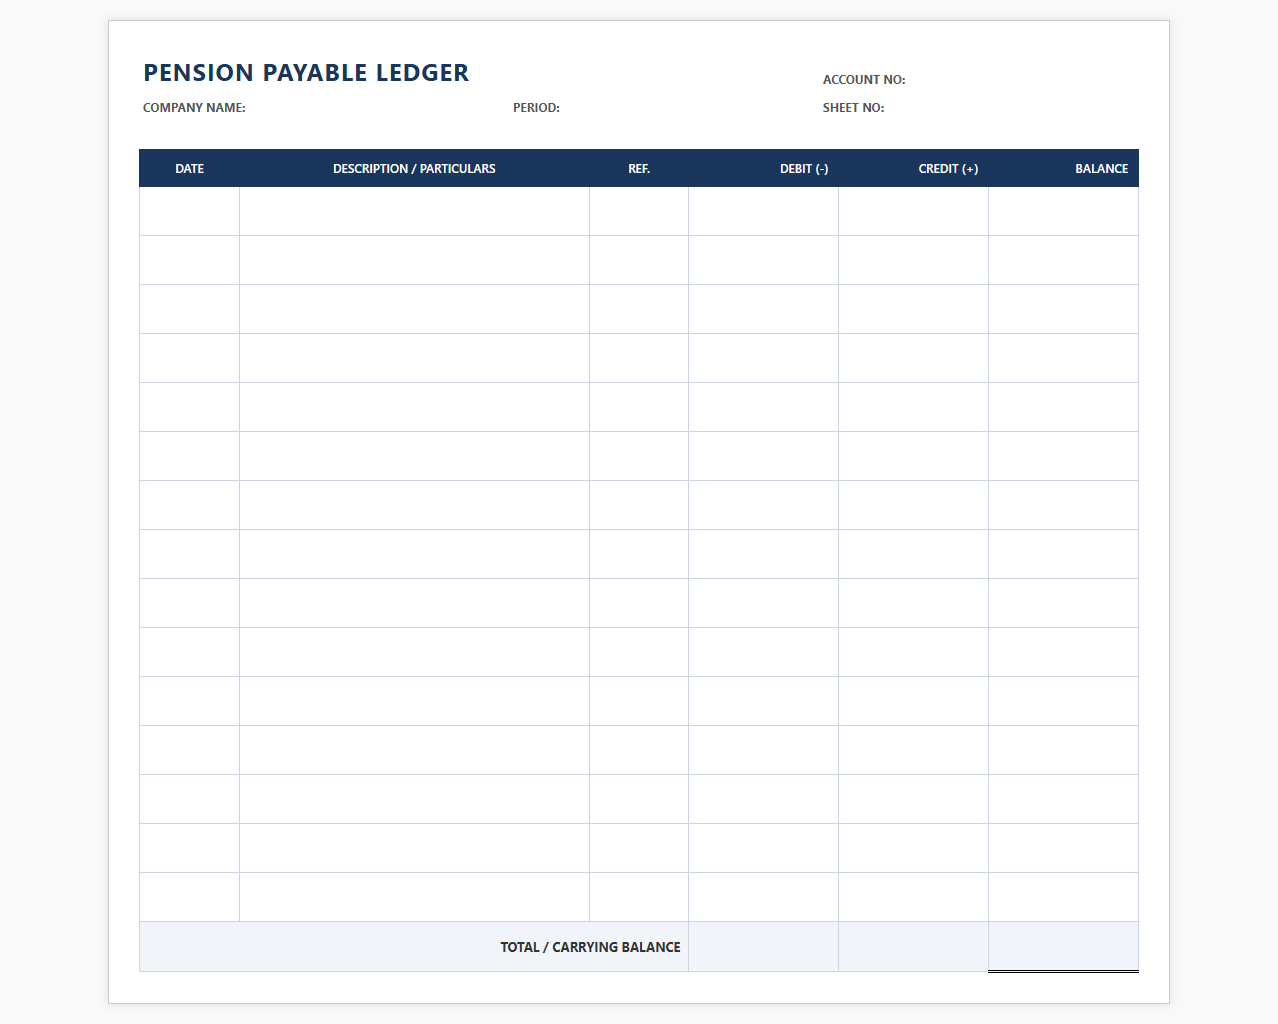
Pension Payable General Ledger Template
 Download: .PDF
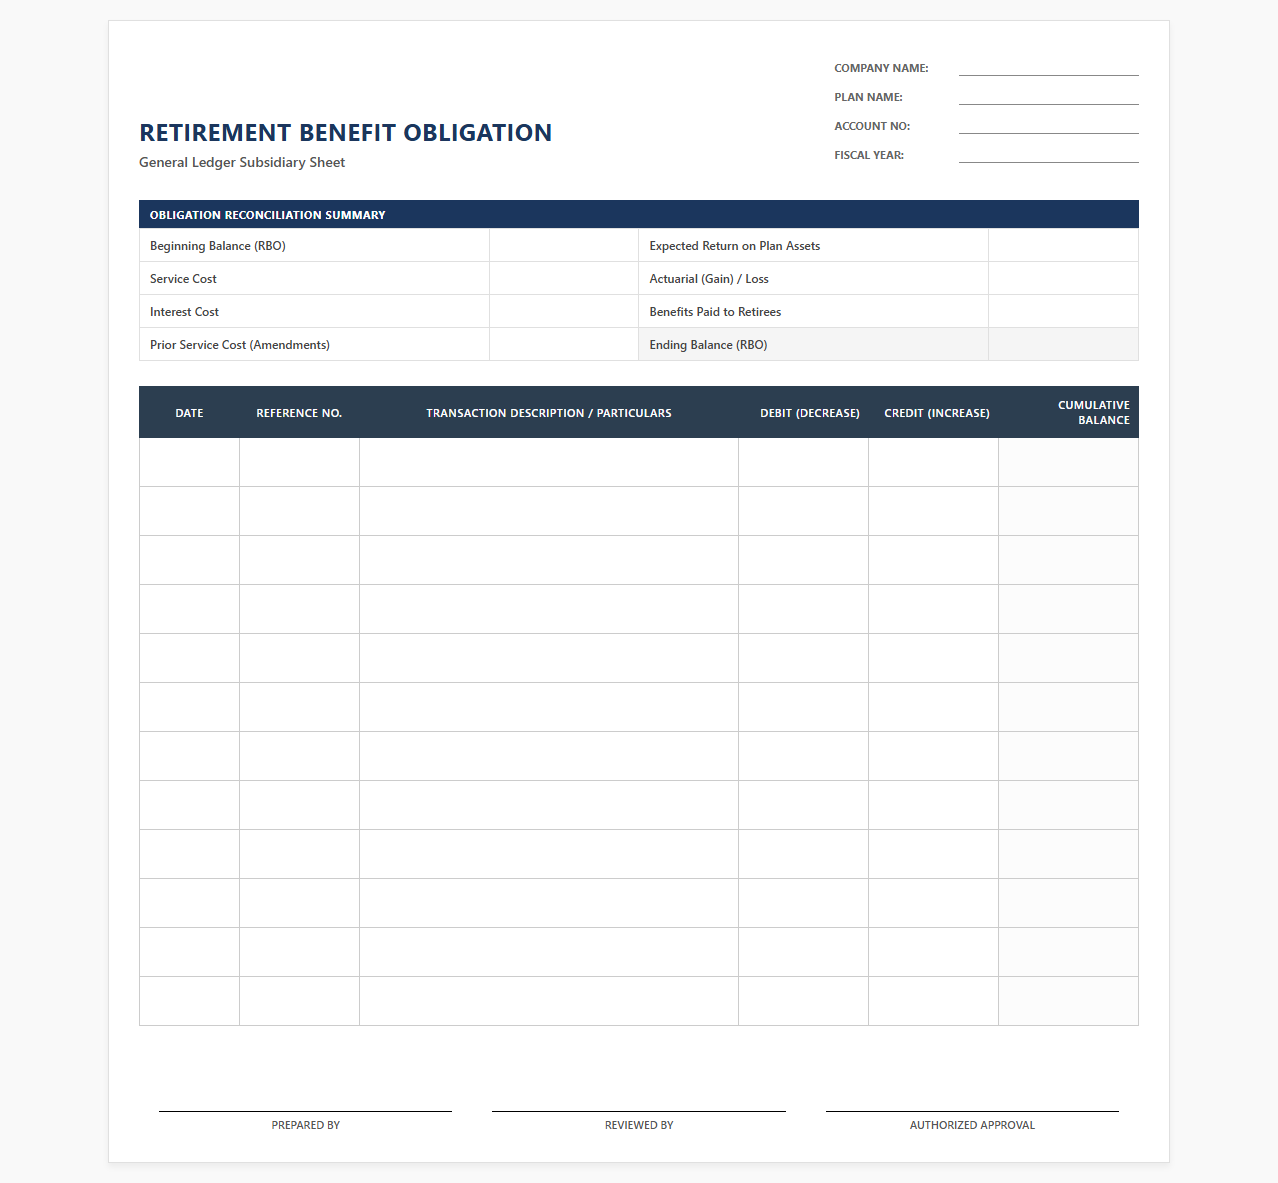
Retirement Benefit Obligation Ledger Sheet
 Download: .PDF
Employee Pension Liability Account Ledger
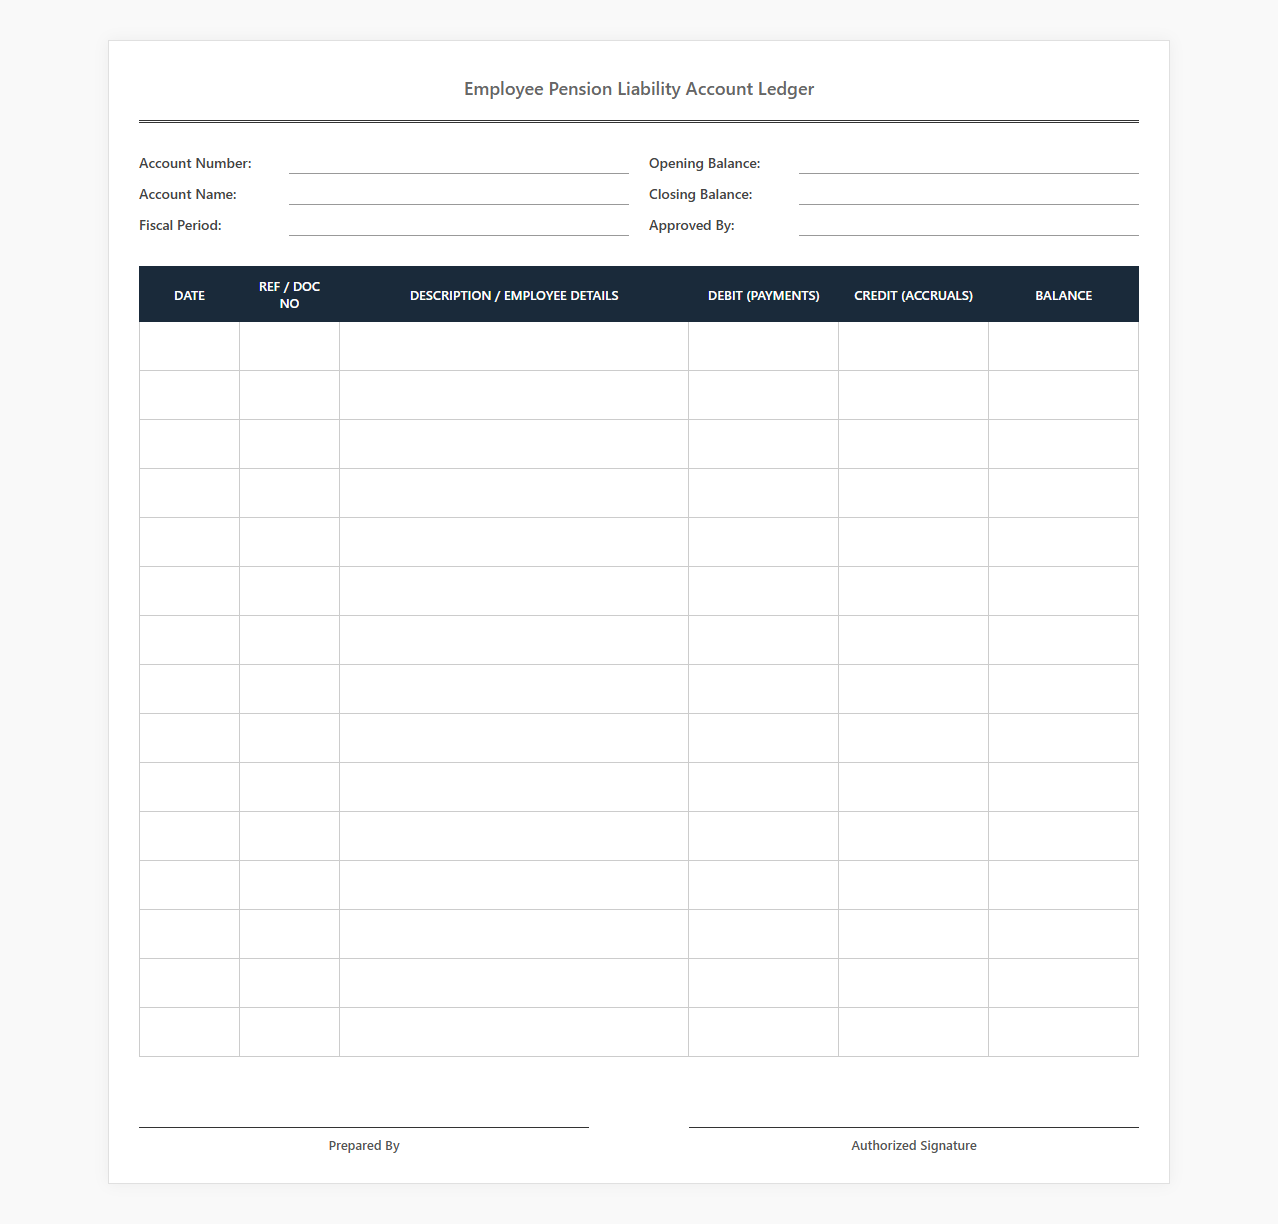 Download: .PDF
Pension Fund Payable Tracking Ledger
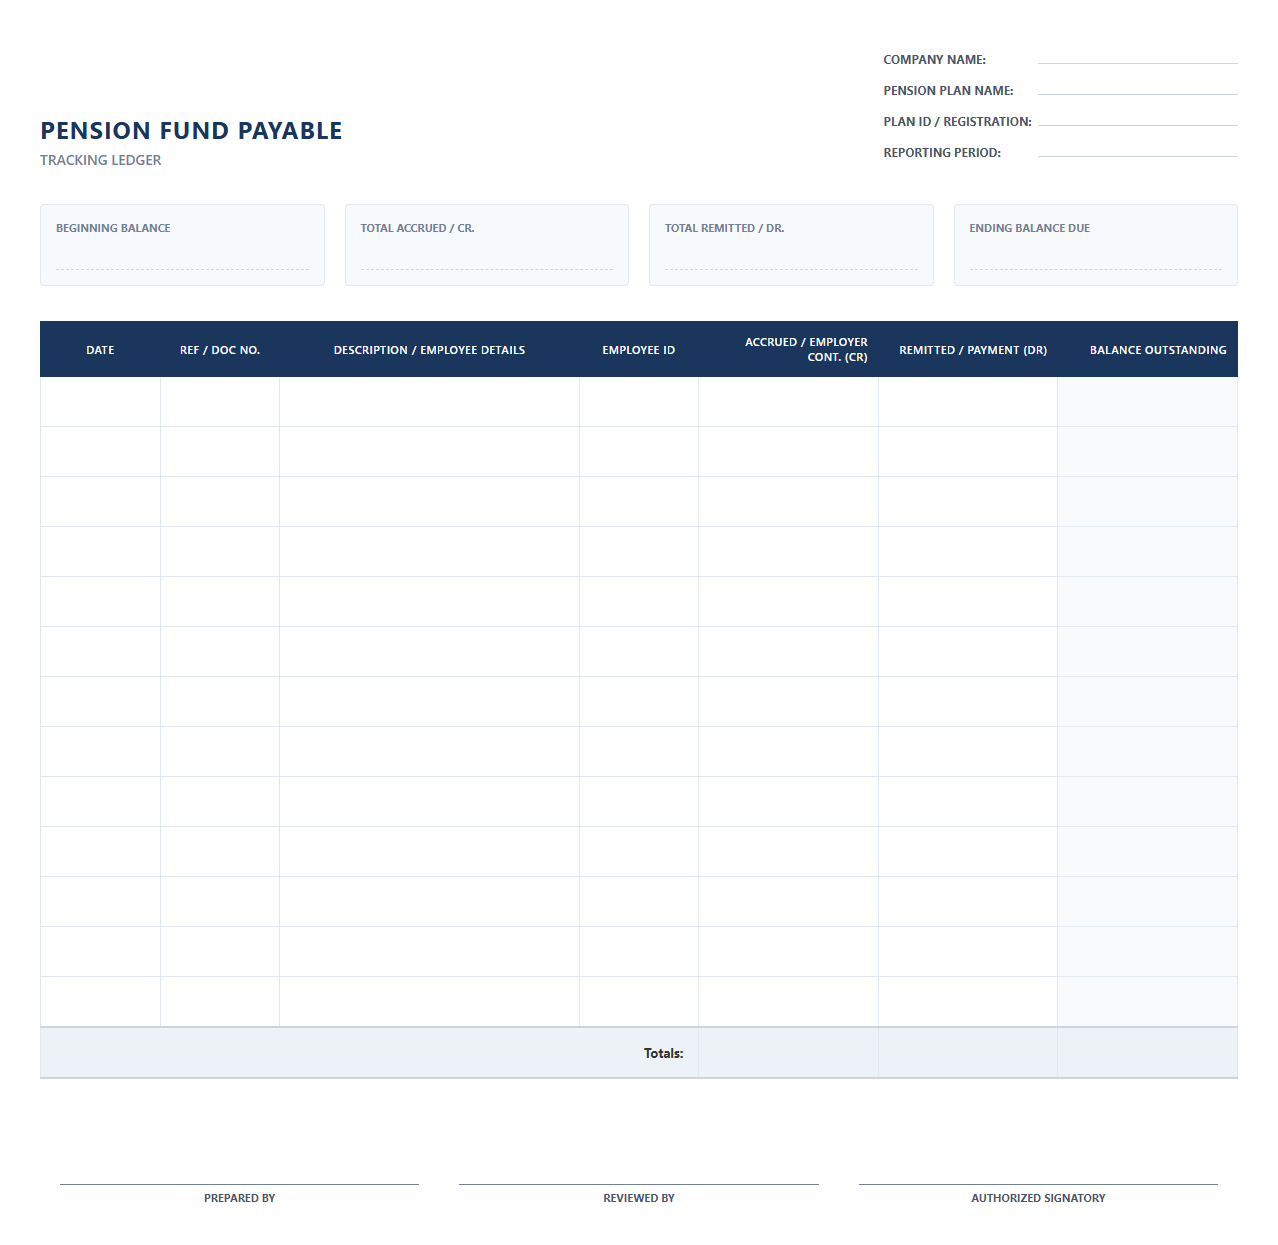 Download: .PDF
Monthly Pension Payable Reconciliation Ledger
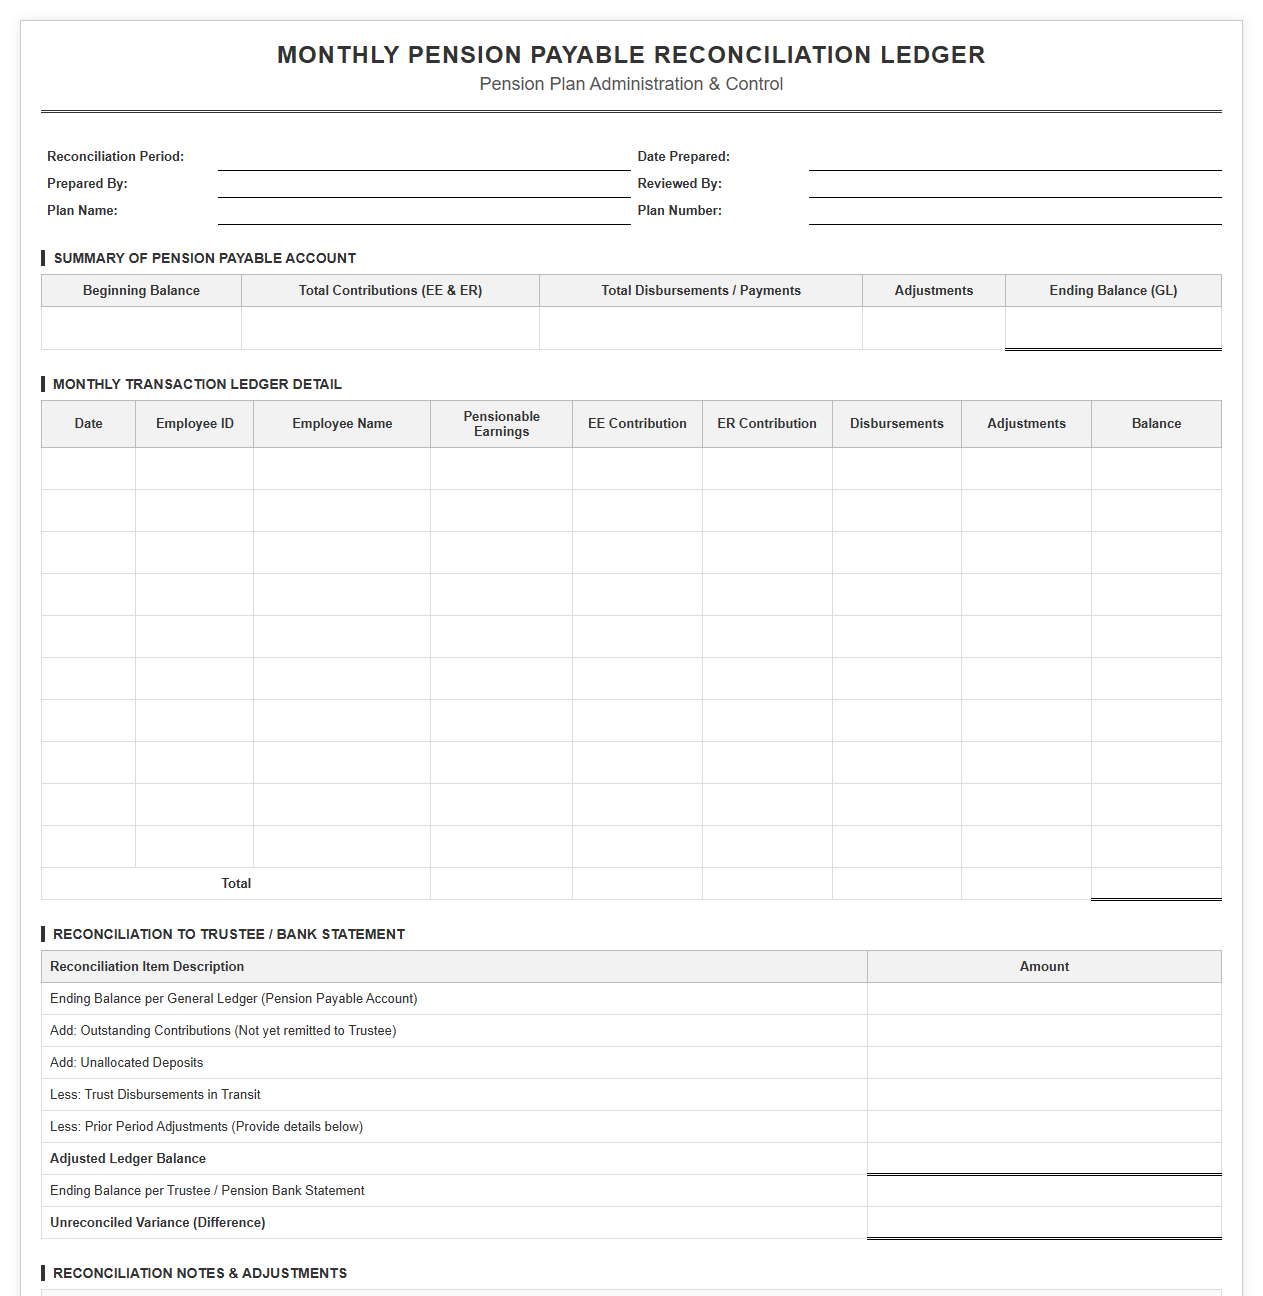 Download: .PDF
Defined Benefit Pension Liability Ledger
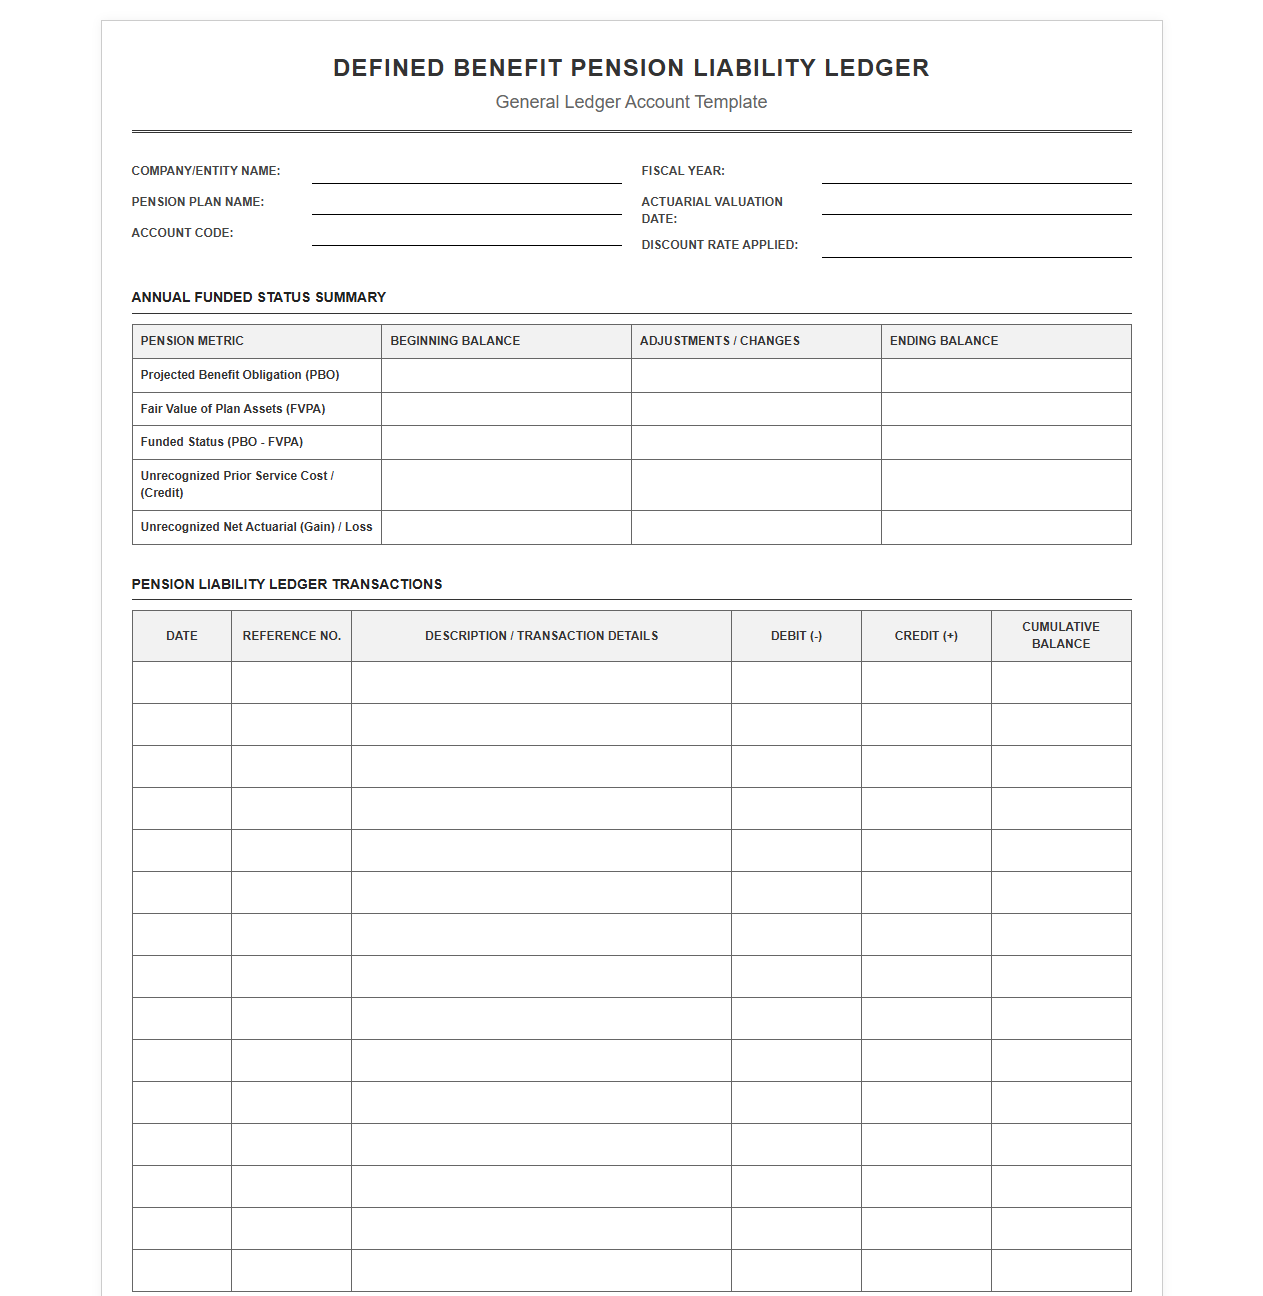 Download: .PDF
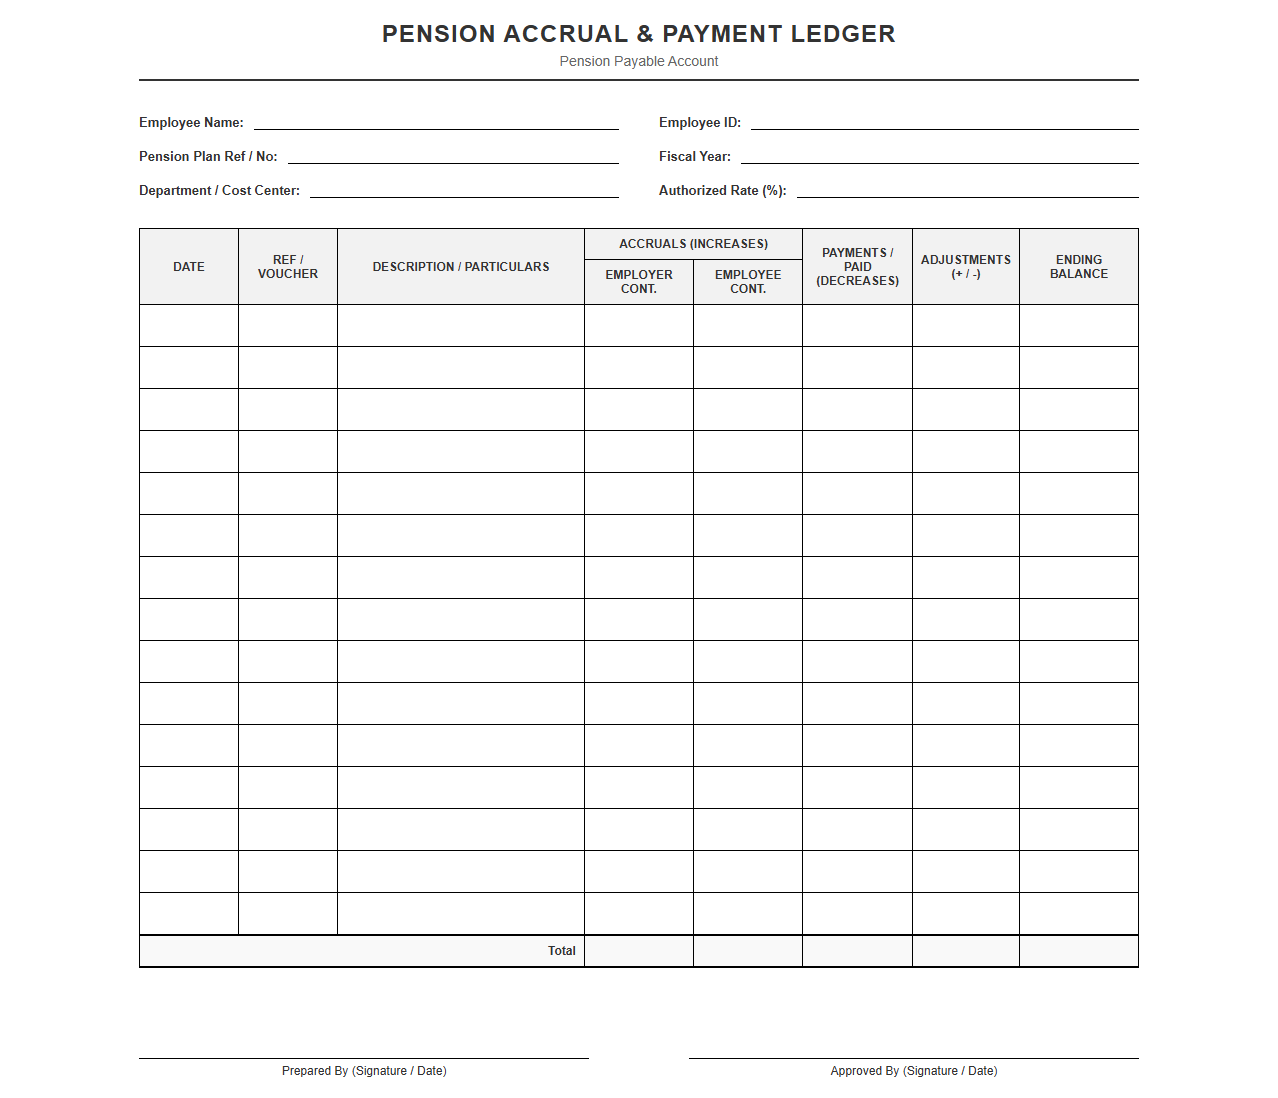
Pension Accrual and Payment Ledger Template
 Download: .PDF
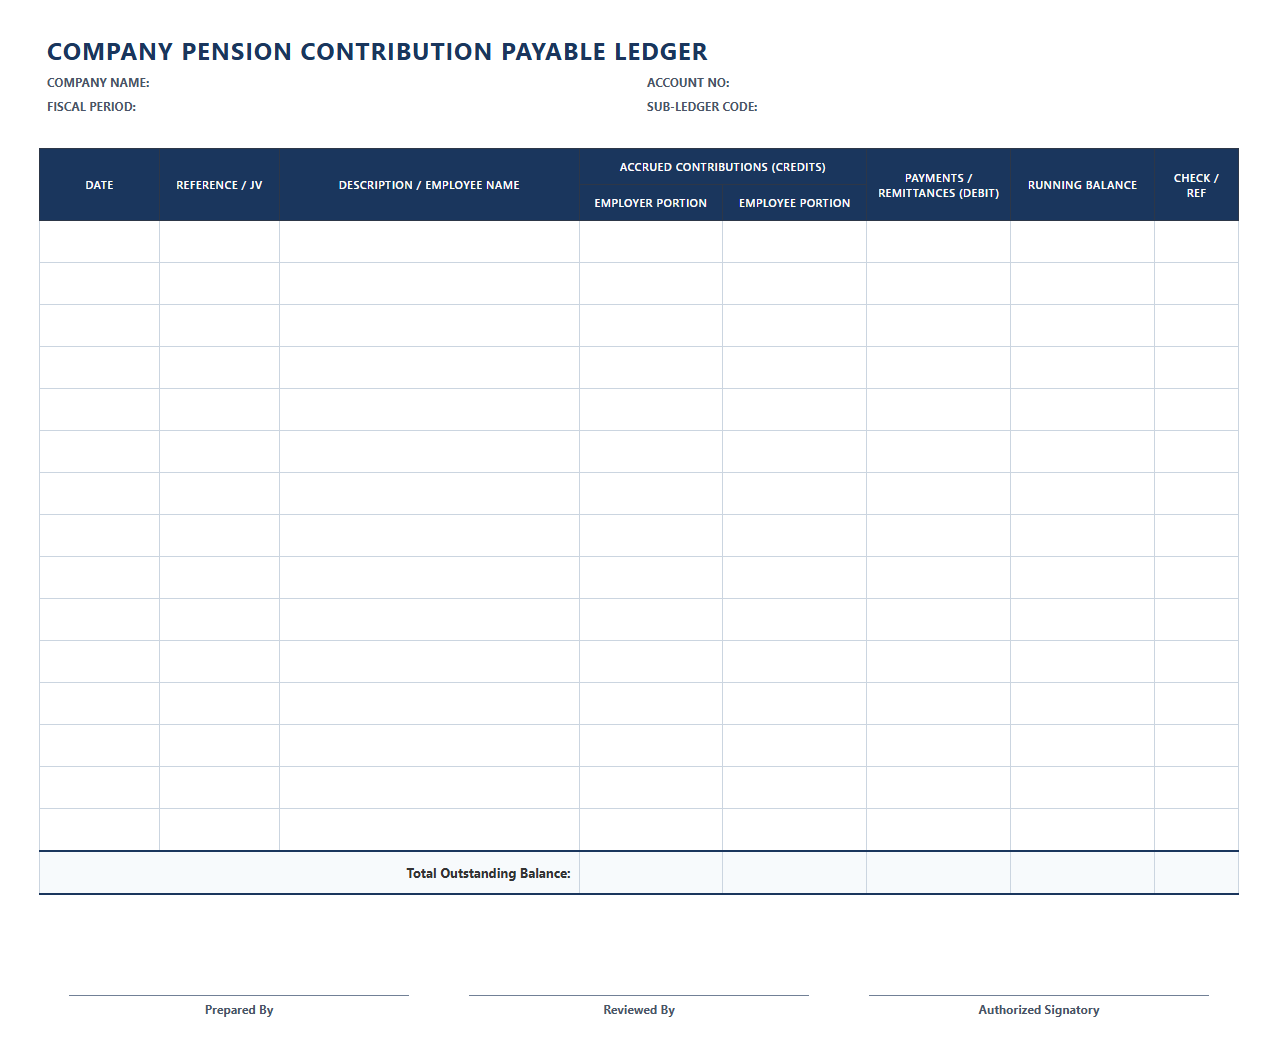
Company Pension Contribution Payable Ledger
 Download: .PDF
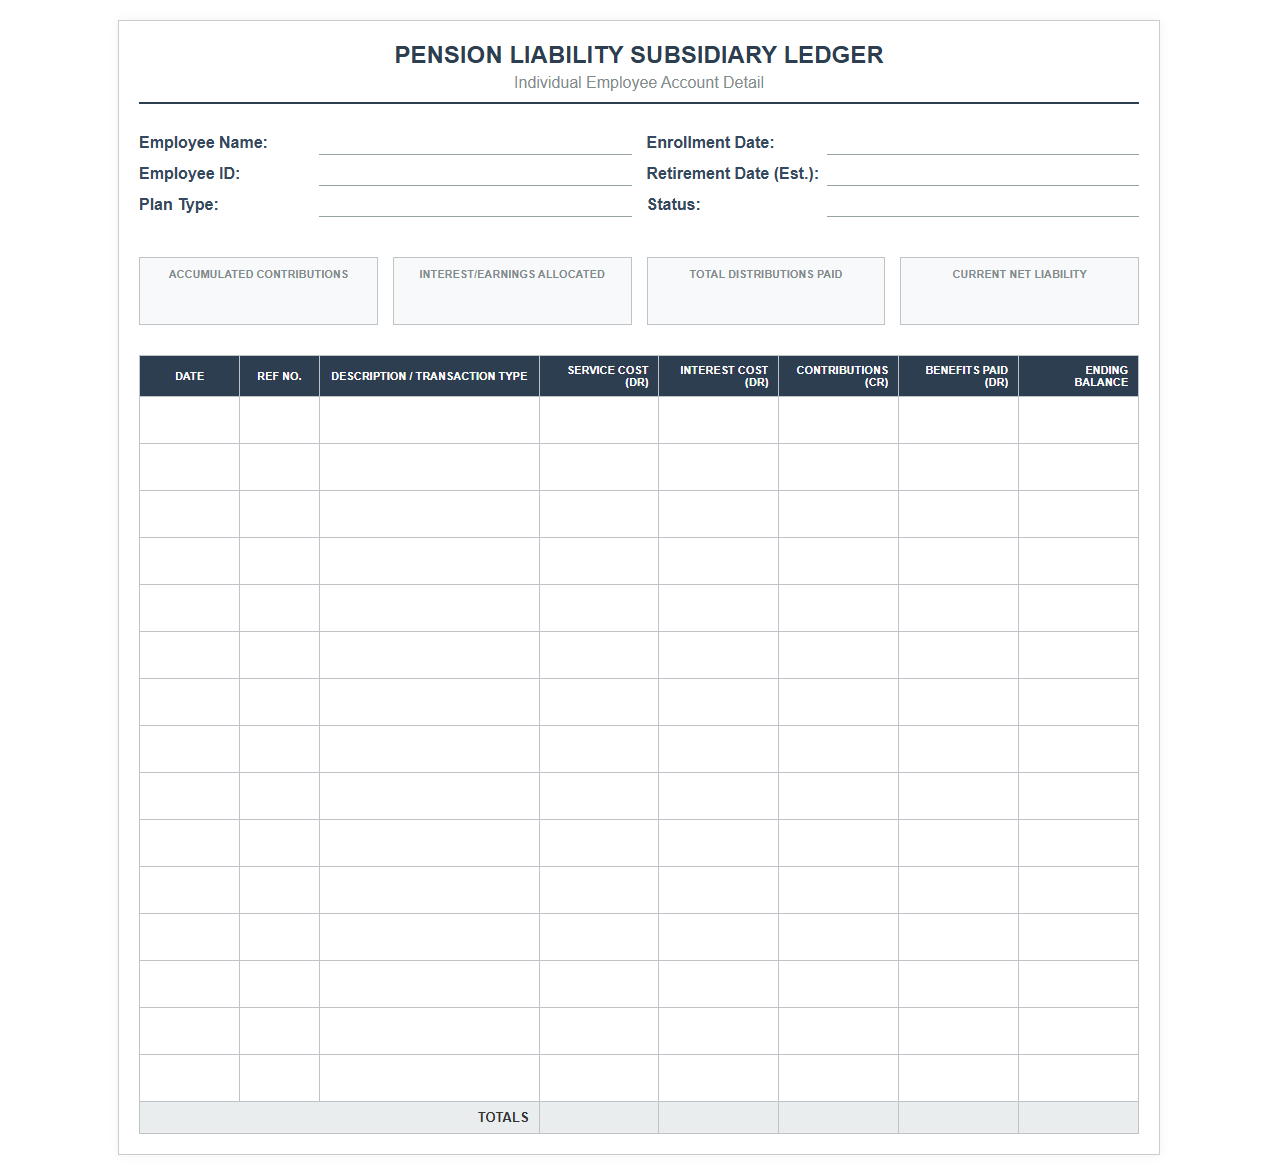
Pension Liability Subsidiary Ledger Template
 Download: .PDF
Introduction to Modern Pension Liability Challenges
Managing long-term pension liabilities is one of the most complex financial obligations a modern enterprise can face. Unlike standard short-term liabilities, pension plans span decades, requiring financial teams to project future payouts based on fluctuating economic indicators, changing demographics, and evolving market conditions.
For modern corporations, maintaining absolute financial accuracy when tracking these obligations is non-negotiable. Even minor miscalculations in projected benefit obligations can result in material misstatements on balance sheets, leading to severe regulatory penalties, eroded investor confidence, and compromised corporate liquidity.
The Strategic Necessity of Specialized Pension Ledgers
Generic accounting ledgers are highly effective for day-to-day transactional tracking, but they inherently fall short when tasked with managing the multi-layered variables of defined benefit pension plans. Standard software lacks the specialized frameworks required to calculate amortization, track interest costs, and adjust for actuarial gains and losses dynamically.
"Standard corporate accounting systems are structurally unequipped to handle the compound actuarial tracking required for pension liabilities, making dedicated sub-ledgers a necessity for precise financial reporting."
Without a specialized pension payable template, organizations struggle to segregate service costs from interest expenses, often leading to skewed operational metrics and inaccurate representations of true long-term financial health.
Core Components of an Effective Pension Payable Template
To successfully capture the granular financial realities of an enterprise retirement plan, a pension payable ledger must contain specific, structured data fields. These fields ensure that both current operational impacts and future obligations are documented in real time.
- Service Cost: The increase in the projected benefit obligation resulting from employee service during the current fiscal period.
- Interest Cost: The accretion of the pension liability over time, calculated using the beginning-of-year discount rate.
- Expected Return on Plan Assets: The projected growth of the pension fund's investments, offsetting the gross liability.
- Actuarial Gains/Losses: Adjustments resulting from differences between previous actuarial assumptions and actual experience.
- Benefit Payments: The actual cash outflows distributed to retirees during the reporting period.
- Discount Rate: The percentage rate used to determine the present value of future pension obligations.
Safeguarding Financial Accuracy and Regulatory Compliance
Regulatory bodies demand unprecedented transparency regarding corporate retirement obligations. Enterprises must adhere to stringent accounting standards such as ASC 715 (US GAAP) and IAS 19 (IFRS), which dictate exactly how pension assets and liabilities are valued and reported.
By implementing a specialized template built for compliance, financial managers can prevent costly reconciliation errors. These templates automate the complex math behind amortizing unrecognized prior service costs and corridor adjustments, ensuring that the figures reported to auditors are mathematically sound and compliant with international standards.
Step-by-Step Guide to Deploying Pension Templates
Transitioning from manual tracking to a dedicated pension ledger template requires a systematic approach to preserve data integrity and align with existing accounting cycles.
- Customize Template Parameters: Align the template's fields with your specific plan rules, adjusting for unique vesting schedules and benefit formulas.
- Populate Historical Actuarial Data: Import past actuarial valuations, plan asset balances, and historical discount rates to establish a reliable baseline.
- Define Journal Entry Mappings: Create clear rules for how monthly pension accruals and payments map to your general ledger accounts.
- Establish a Multi-Step Verification Workflow: Implement an internal audit gate where actuarial inputs are cross-checked by a secondary reviewer before locking the ledger.
Integrating Ledger Templates with Enterprise ERP Systems
While specialized templates function as powerful stand-alone tools, their true value is unlocked when integrated directly with main Enterprise Resource Planning (ERP) systems. Automated integration bridges the gap between high-level general ledgers and granular pension calculations.
By mapping variables such as pension_asset_value, service_cost_accrual, and discount_rate_variance directly into ERP software, financial teams can establish seamless, automated data flows. This continuous synchronization eliminates manual data-entry errors and provides executive leadership with real-time visibility into the organization's net pension liability.
Best Practices for Long-Term Pension Ledger Maintenance
Maintaining a pension ledger is not a one-time setup; it requires continuous oversight and regular updates to reflect changing market realities and workforce demographics. Financial managers must establish a rigorous maintenance schedule to prevent the ledger from falling out of alignment with actual obligations.
Regular communication with external actuaries ensures that updated discount rates and life expectancy tables are integrated promptly. Additionally, conducting biannual internal audits of the ledger's formulas helps spot anomalies before they escalate into reporting discrepancies.
Leave a comment