For corporate finance teams, reconciling factored receivables often feels like chasing a moving target. Managing multi-party cash flows between the seller, debtor, and factor introduces immediate tracking discrepancies. Before investing in complex automation, organizations must first establish a rigorous operational foundation to bridge these complex cash-flow gaps.
Standardizing this baseline through structured ledger templates grants teams immediate transactional clarity and eliminates costly reconciliation lag. Please note: these templates are highly effective but require disciplined, daily ledger hygiene to prevent aging mismatches.
By systematically categorizing reserve holdbacks, advance rates, and factor discount fees, organizations can dramatically reduce month-end disputes. This guide details how to structure these templates, establish standardized data fields, and implement a bulletproof reconciliation workflow.
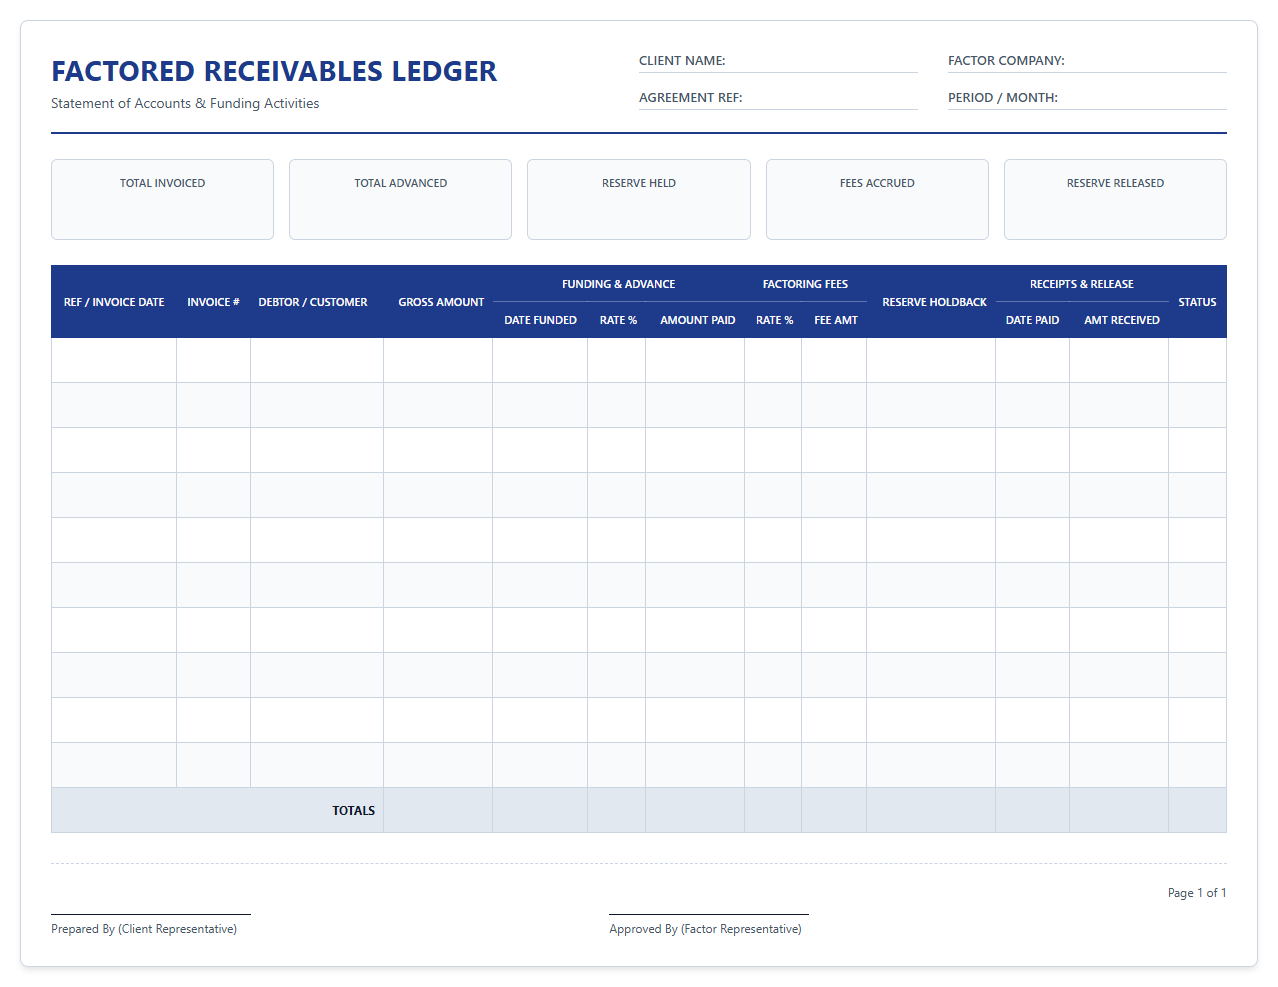
Factored Receivables Ledger Template
 Download: .PDF
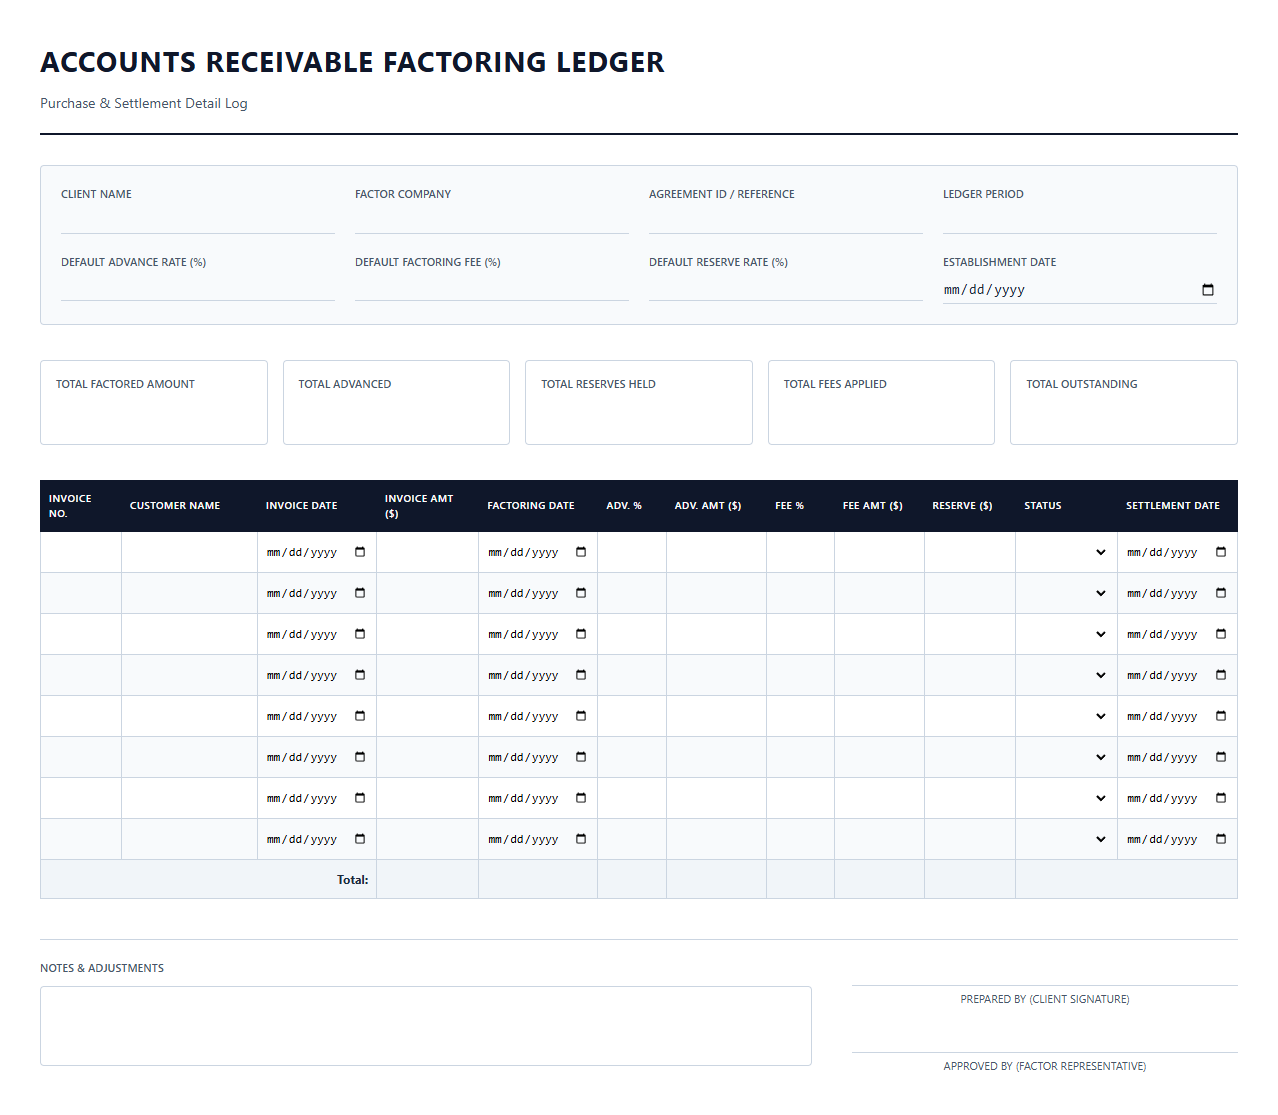
Accounts Receivable Factoring Ledger
 Download: .PDF
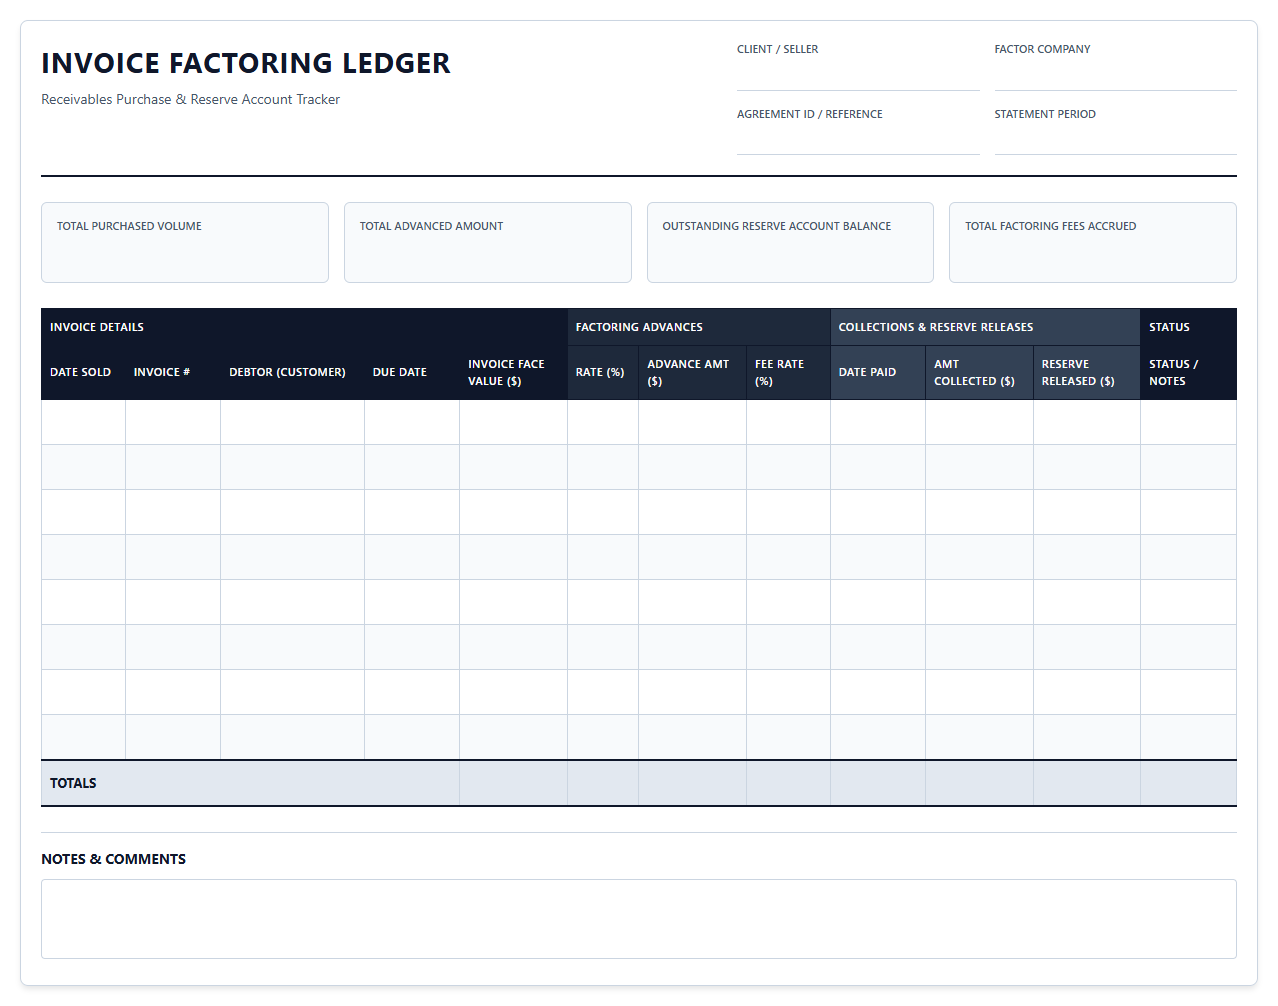
Invoice Factoring Ledger Template
 Download: .PDF
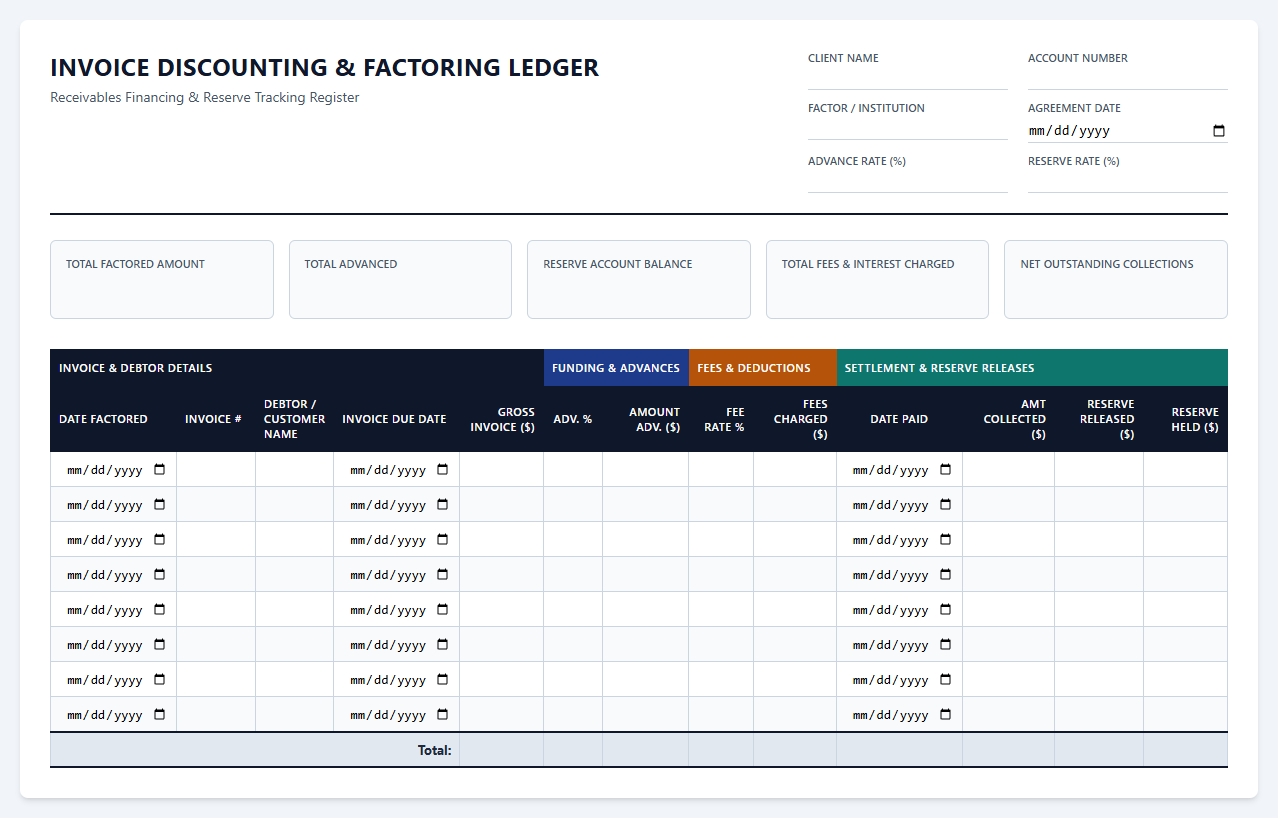
Invoice Discounting and Factoring Ledger
 Download: .PDF
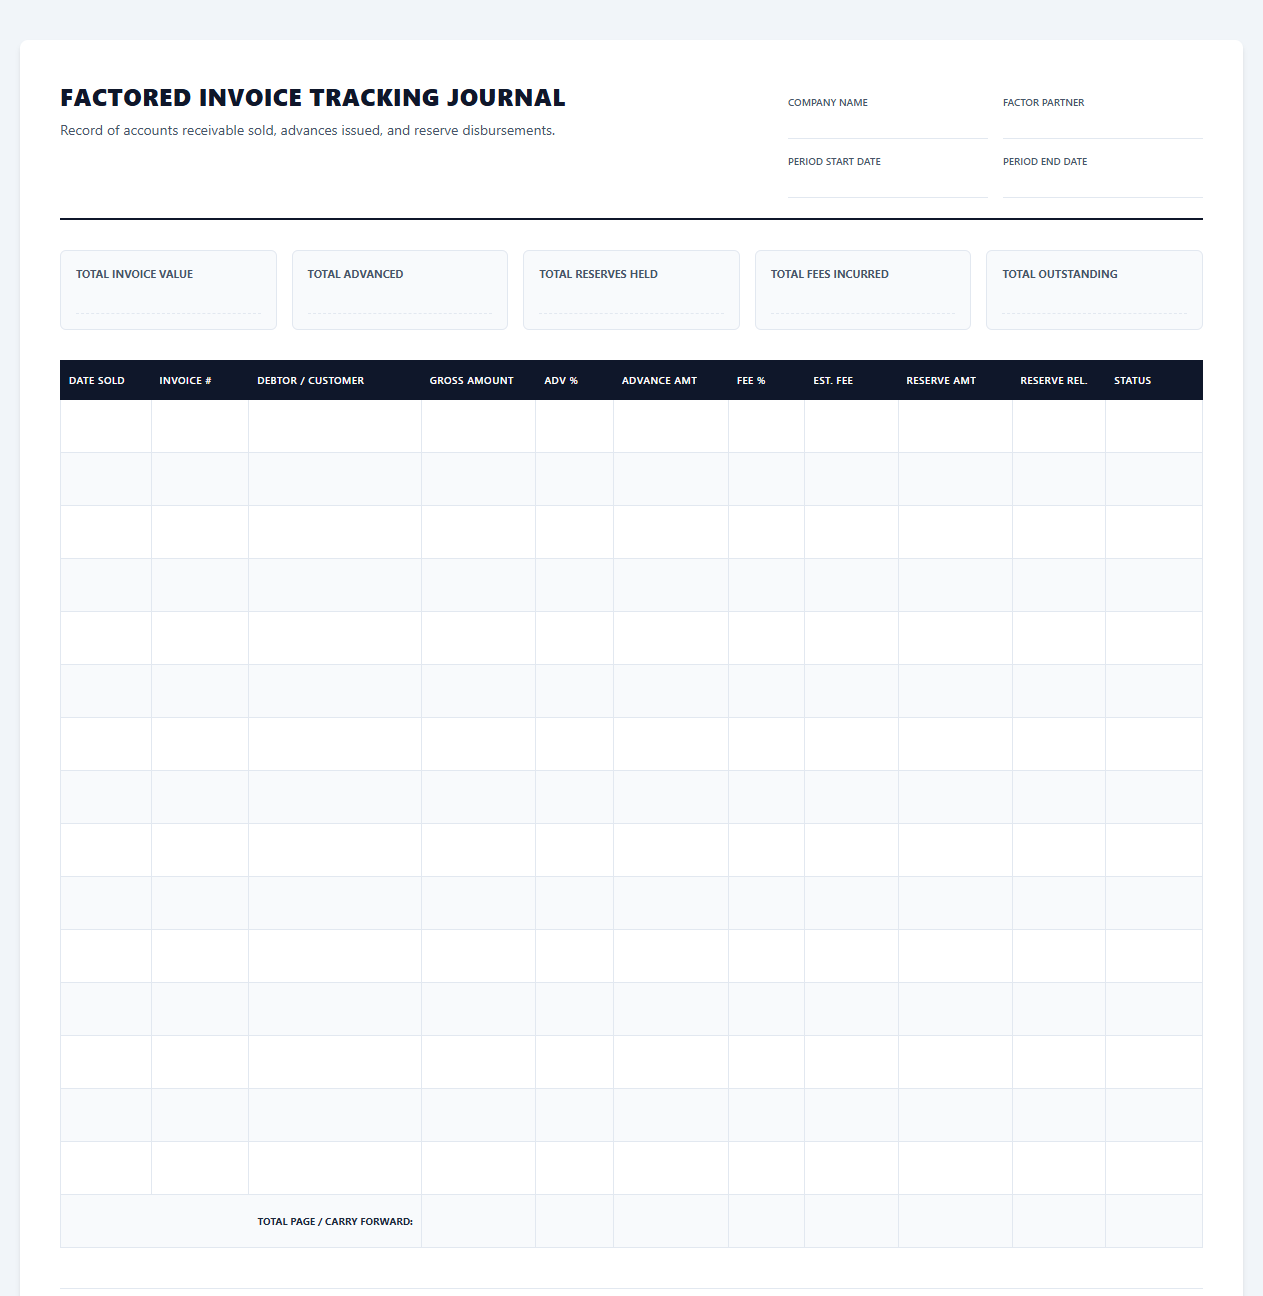
Factored Invoice Tracking Journal
 Download: .PDF
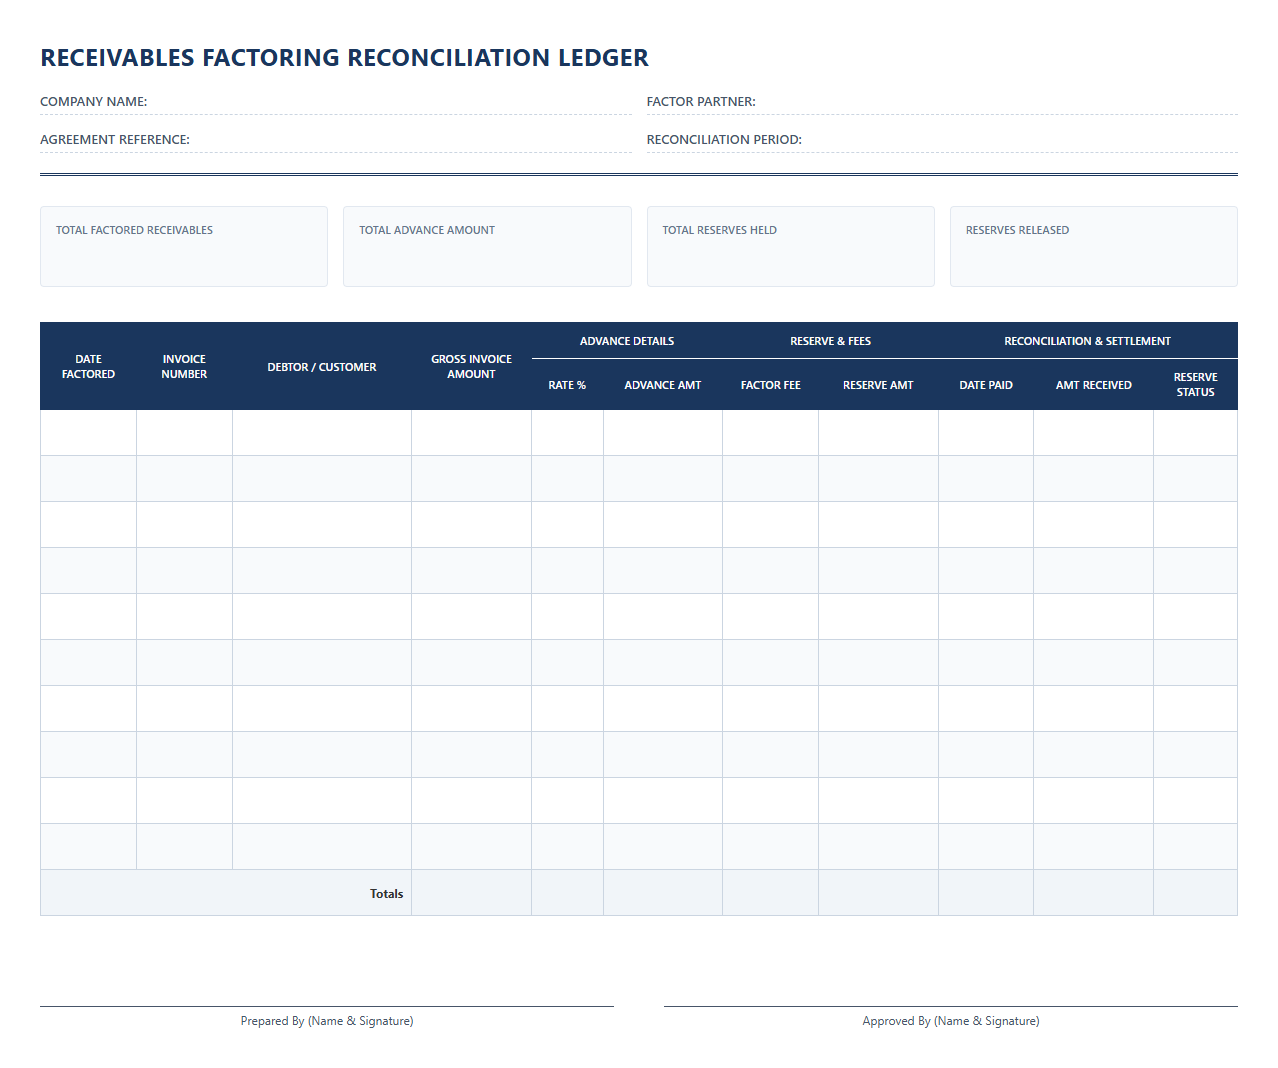
Receivables Factoring Reconciliation Ledger
 Download: .PDF
Factored Accounts Receivable Reconciliation Sheet
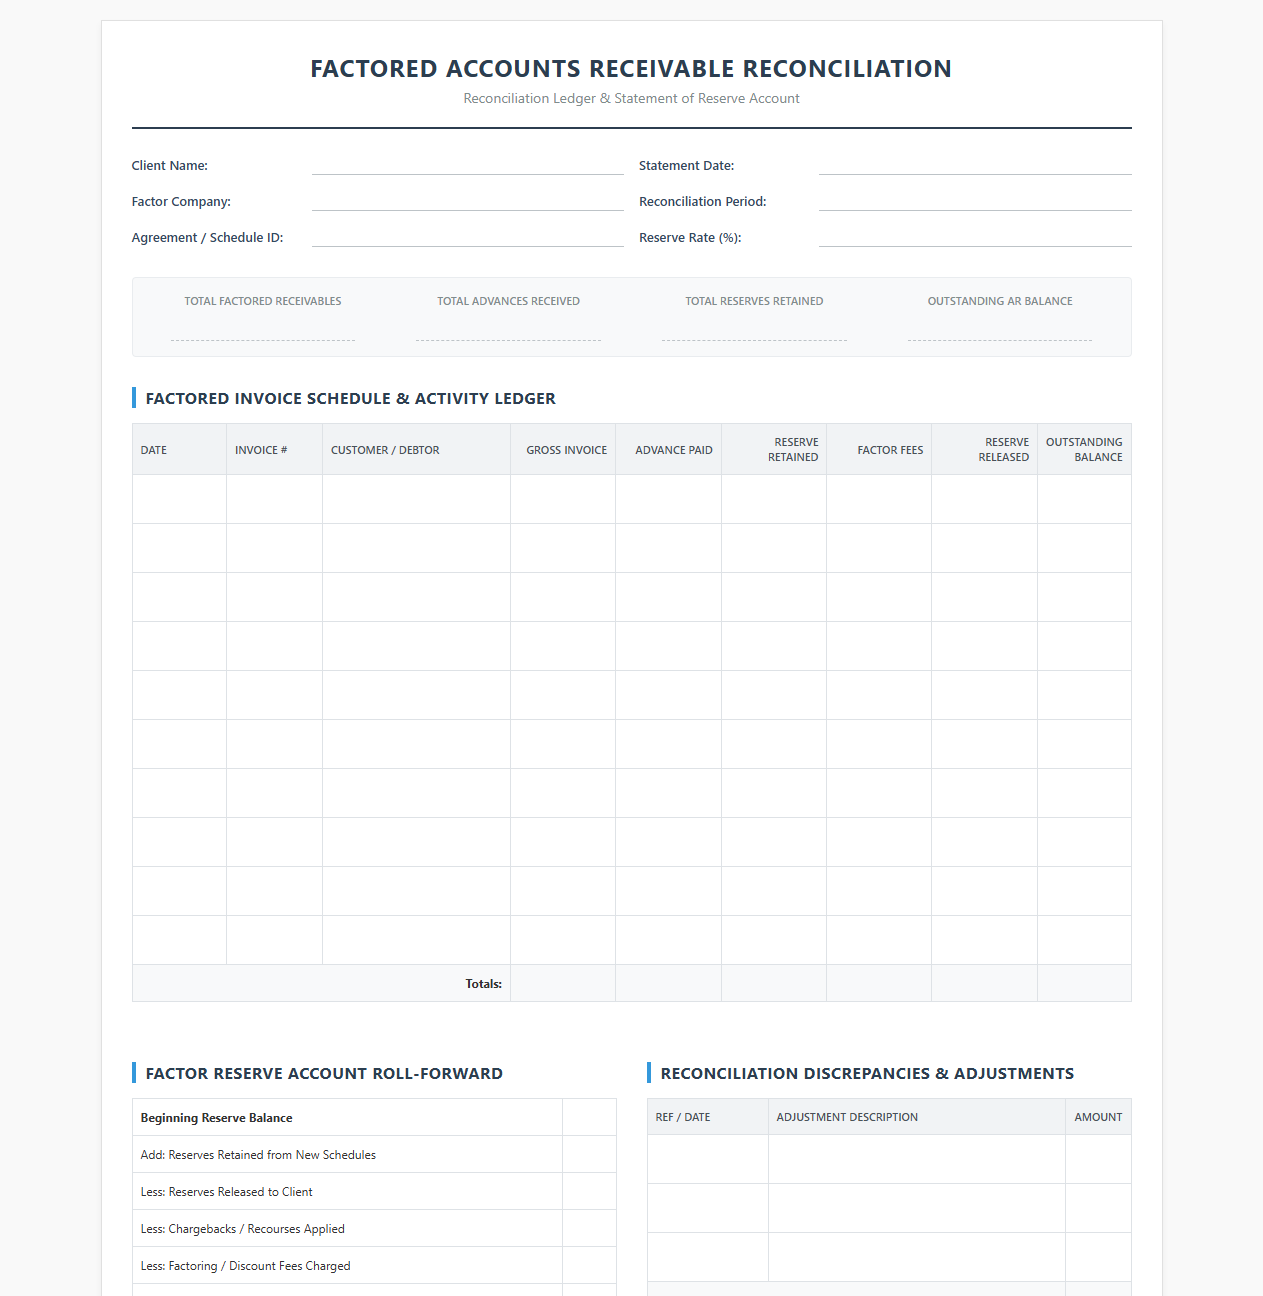 Download: .PDF
Debt Factoring Register Template
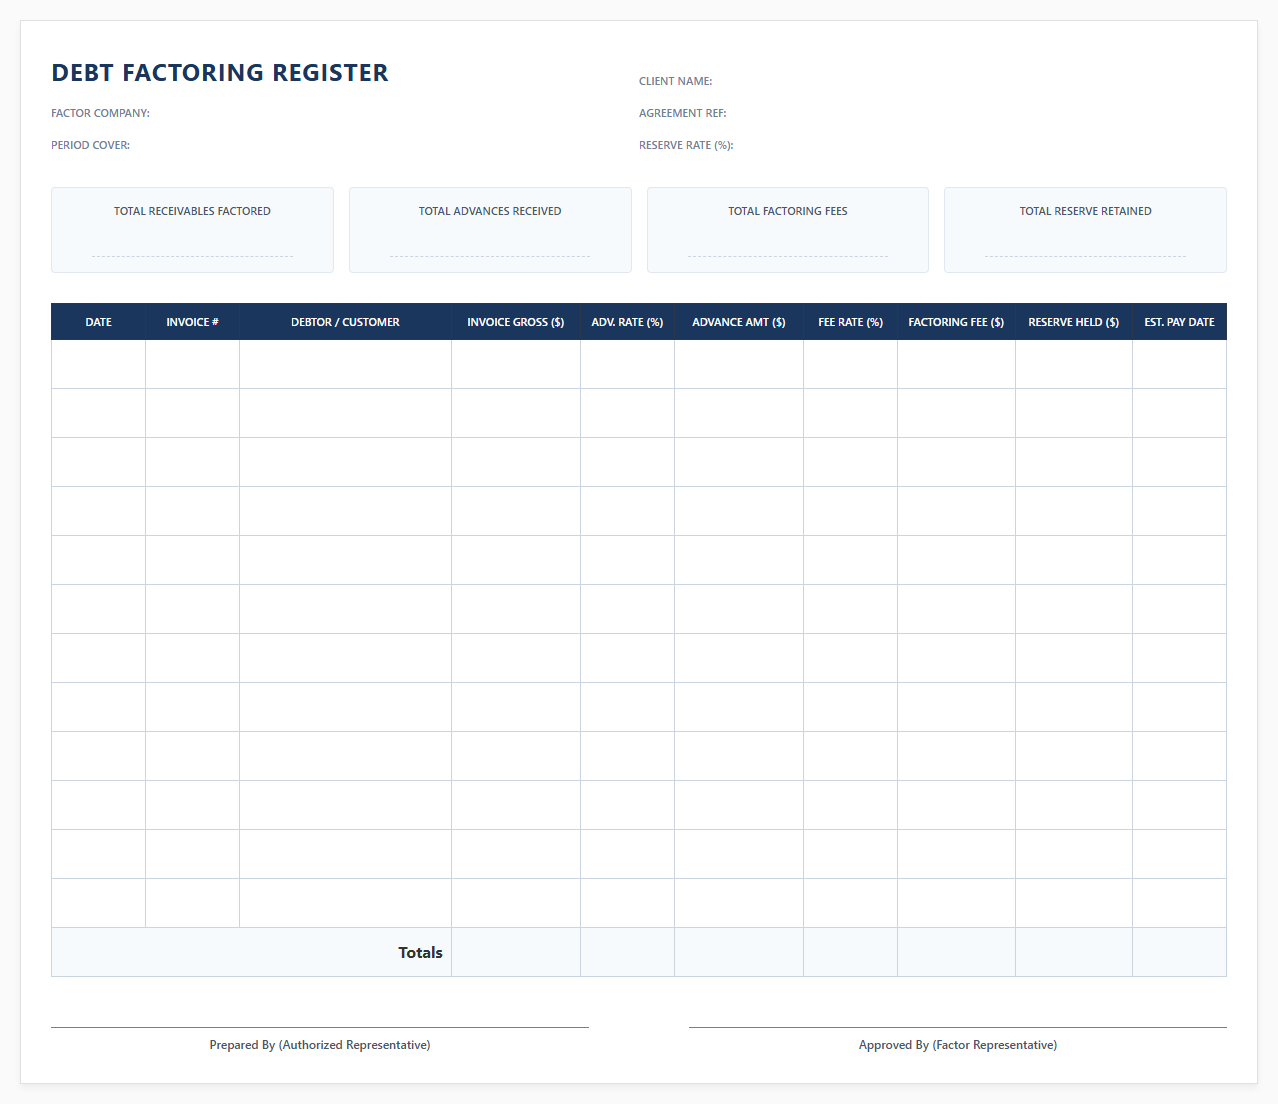 Download: .PDF
Introduction: The Complexity of Factored Receivables
Factoring accounts receivable is a powerful tool for accelerating cash flow, yet it introduces unique layers of accounting complexity. Unlike standard sales transactions where a customer pays an invoice directly, factoring involves a tripartite financial arrangement. The presence of the factor alters the flow of cash, dividing a single invoice lifecycle into multiple distinct financial events.
When an invoice is factored, the business receives an immediate advance-typically a percentage of the total invoice value. The remaining balance is held in a reserve account, which is only released, minus the factor's service fees, after the end customer clears the debt. Managing these split payments, tracking the fluctuating reserve holds, and accurately documenting complex factoring fees require precise bookkeeping. Without a structured system, businesses quickly lose visibility into their actual cash position and outstanding receivables.
The Hidden Costs of Fragmented Ledger Systems
Many businesses attempt to track factored invoices using disparate, non-standardized spreadsheets or manual templates. This ad-hoc approach inevitably leads to severe reconciliation bottlenecks, data duplication, and reporting errors that distort the company's true financial health.
"Fragmented systems turn what should be a straightforward cash-acceleration strategy into an administrative nightmare, burying finance teams under hours of manual verification."
When tracking systems are not standardized, several operational vulnerabilities arise:
- Unapplied Cash Discrepancies: Difficulty in matching customer payments received by the factor against original open invoices on the internal subledger.
- Miscalculated Fee Expenses: Failure to properly separate interest charges, processing fees, and administrative surcharges from the principal invoice amounts.
- Aging Report Distortion: Factored invoices appearing as critically overdue in internal systems long after the business has already received the cash advance.
Blueprint of a Standardized Factoring Ledger Template
To maintain absolute financial clarity, organizations must deploy a standardized ledger template. This template acts as a single source of truth, capturing every critical variable of the factoring transaction from origination to final settlement.
| Field Name | Data Type | Description |
|---|---|---|
| Invoice ID | Alphanumeric | The unique internal identifier for the generated invoice. |
| Original Invoice Value | Currency | The total gross amount billed to the customer. |
| Advance Rate | Percentage | The percentage of the invoice value advanced by the factor (e.g., 80%). |
| Advance Amount Paid | Currency | The actual cash received during the initial funding phase. |
| Reserve Amount Holdback | Currency | The portion retained by the factor until customer payment is secured. |
| Factoring Fees incurred | Currency | The total discount fees and administrative charges levied by the factor. |
Accounting for Reserves and Factoring Fees
Accurate bookkeeping requires precise journal entries to reflect the reduction in accounts receivable, the cash cash-inflow, and the temporary asset represented by the reserve account. The reserve account is not an expense; rather, it is a restricted asset that must be tracked diligently until final release.
When factoring occurs, the initial entry typically involves debiting Cash and debiting a Due from Factor (Reserve) asset account, while crediting Accounts Receivable. Because factoring fees can be structured as flat rates or tiered based on how long the invoice remains unpaid, bookkeeping must dynamically calculate these costs before final ledger posting.
Step-by-Step Reconciliation Workflow
Reconciling internal records with the factoring company's weekly or monthly statement is vital to prevent leakage and catch banking discrepancies early. Follow this structured process to keep records perfectly aligned:
- Verify the total gross value of all newly submitted invoices against the factor's schedule of accounts report.
- Confirm that the initial cash advances received in the bank account match the calculated advance amounts in the ledger.
- Review the factor's collection report to identify which customers paid, noting any short payments or disputes.
- Calculate the exact factoring fees charged for the period and compare them to the factor's invoice or statement breakdown.
- Reconcile the release of reserve funds to the bank, ensuring the cash received matches the total reserve minus the applied fees.
Mitigating Errors through Automated Validation Rules
Manual data entry is highly prone to human error, which can quickly compound when handling high-volume transactions. Building automated validation rules and formula checks directly into your ledger template ensures that discrepancies are flagged immediately.
By enforcing logical validation constraints, you prevent math errors and guarantee data integrity. Below is an example of a logical formula representation used to validate ledger balancing:
IF (Advance_Amount + Reserve_Amount) != Original_Invoice_Value:
    FLAG_ERROR("Discrepancy in funding distribution")
ELSE:
    CALCULATE_FEE(Tiered_Rate, Days_Outstanding)
Applying these validation rules ensures that the sum of the components always equals the whole, safeguarding the integrity of your balance sheet and preventing missed collections or unaccounted fee leakage.
Conclusion: Elevating Financial Visibility and Control
Implementing a standardized factoring ledger is a critical step for businesses leveraging accounts receivable financing. By establishing structured templates, clear reconciliation processes, and automated validation rules, organizations can eliminate tracking blind spots and reduce administrative overhead.
These practices ensure highly accurate financial reporting, allowing leadership to maintain precise cash flow forecasting and absolute audit readiness. Transforming how you account for factored receivables secures the control needed to scale operations with confidence.
Leave a comment