Accounting departments frequently struggle with month-end reconciliation discrepancies, where timing mismatches between payroll cycles and fiscal cutoffs lead to frustrating balance sheet errors. Before addressing these discrepancies directly, financial leaders must first establish a robust framework that satisfies the accrual matching principle. Utilizing a standardized accrued payroll ledger template grants organizations immediate control over their outstanding liabilities, transforming a chaotic closing process into a streamlined, audit-ready routine.
However, it is important to note that these templates serve as structural frameworks; their success depends on a firm grasp of underlying payroll variables. For example, accurately calculating unbilled hourly wages, accrued PTO, or prorated bonuses at the exact cutoff date provides the concrete proof needed to validate your journal entries. In this article, we will introduce our comprehensive ledger templates, explain how to deploy them, and share best practices for eliminating financial discrepancies permanently.
Payroll Accrual Journal Entry Template
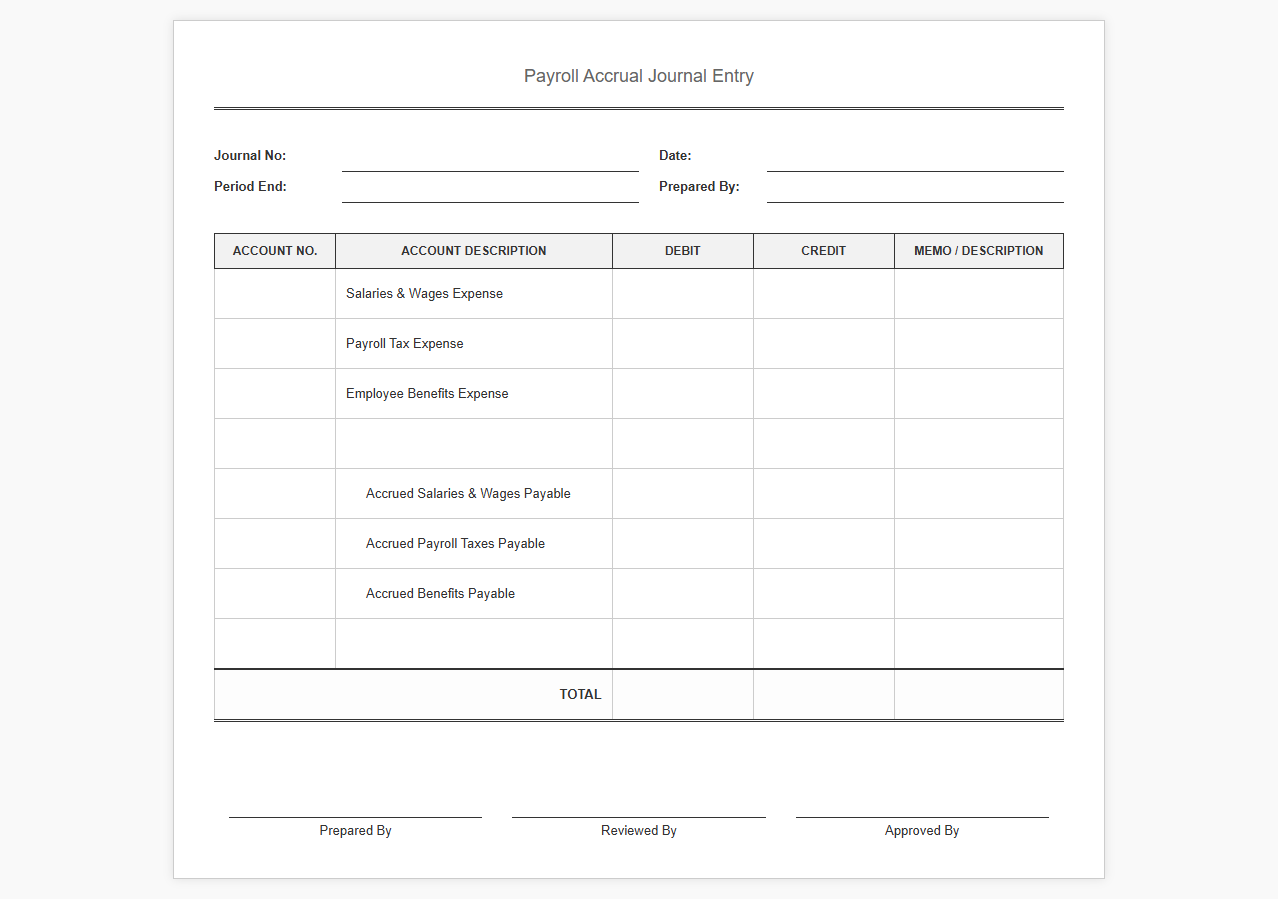 Download: .PDF
Monthly Salary and Wage Accrual Ledger
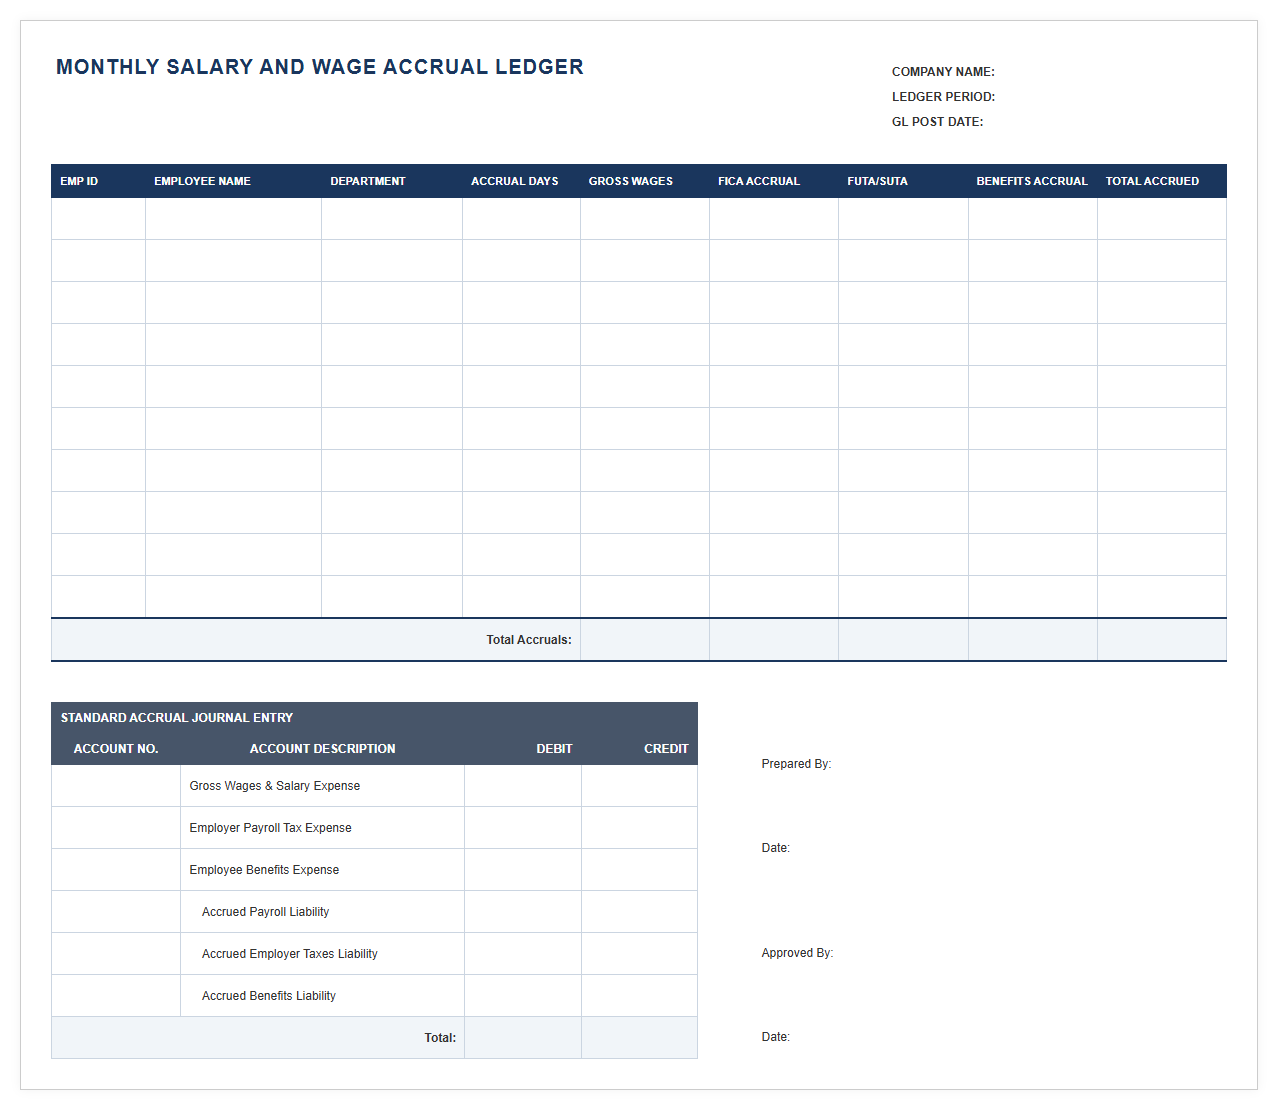 Download: .PDF
Accrued Payroll Liability Balance Sheet Template
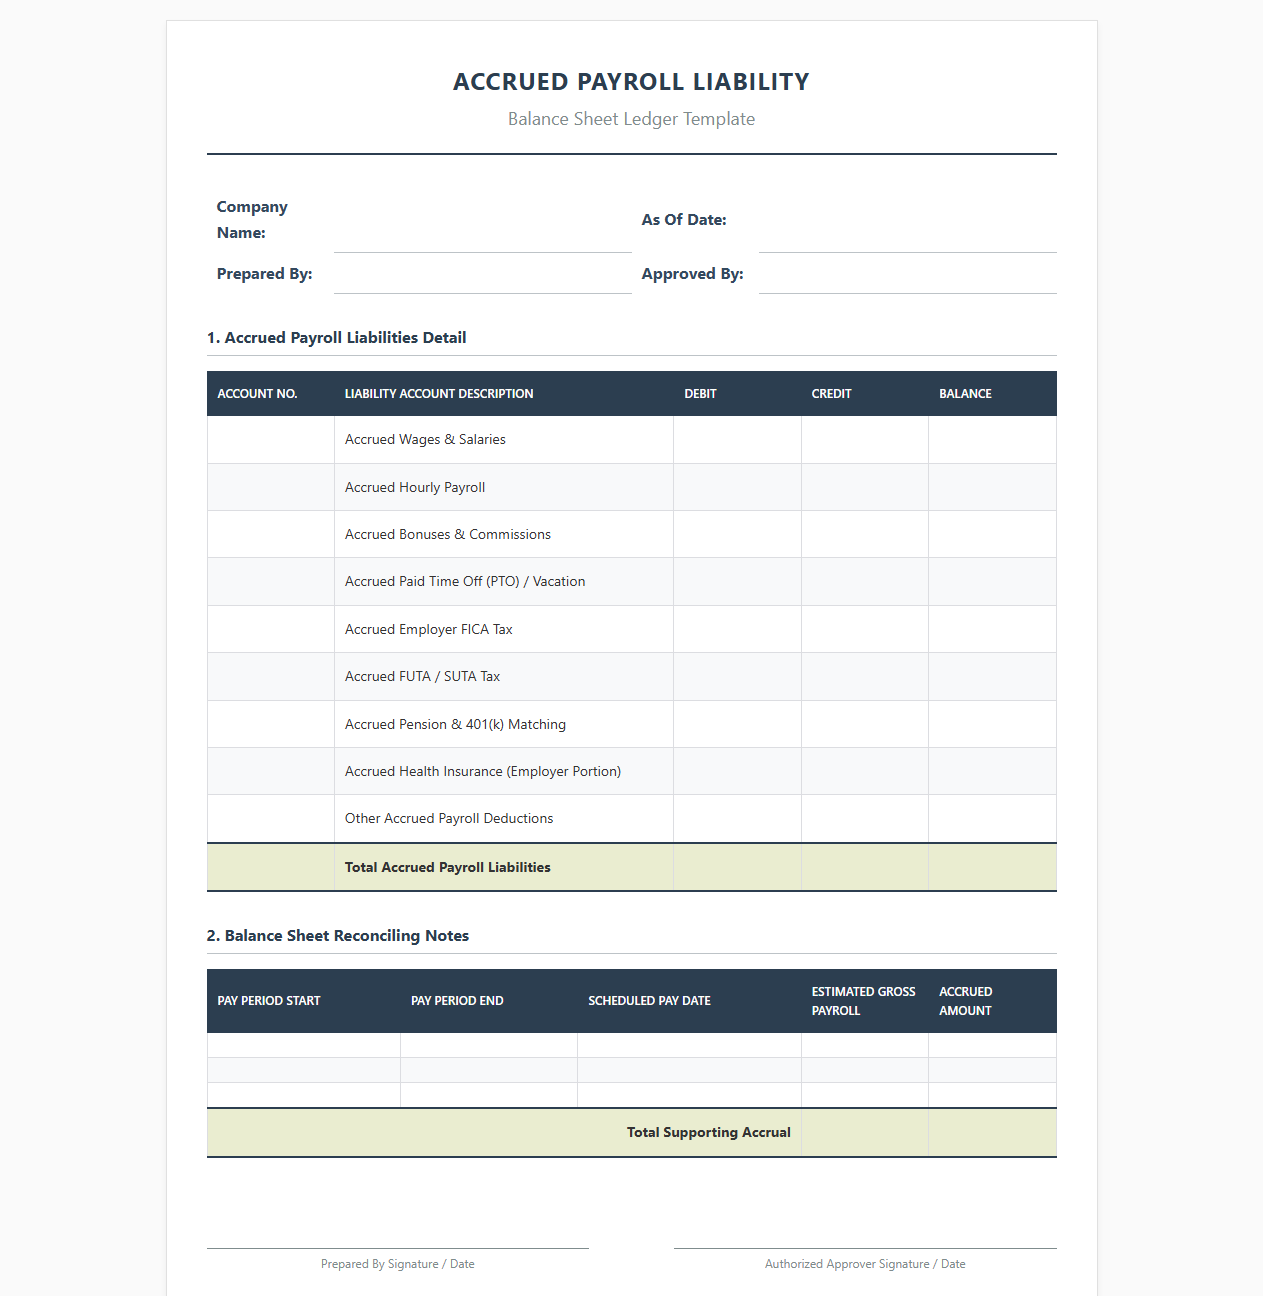 Download: .PDF
Employee Benefits and Payroll Accrual Ledger
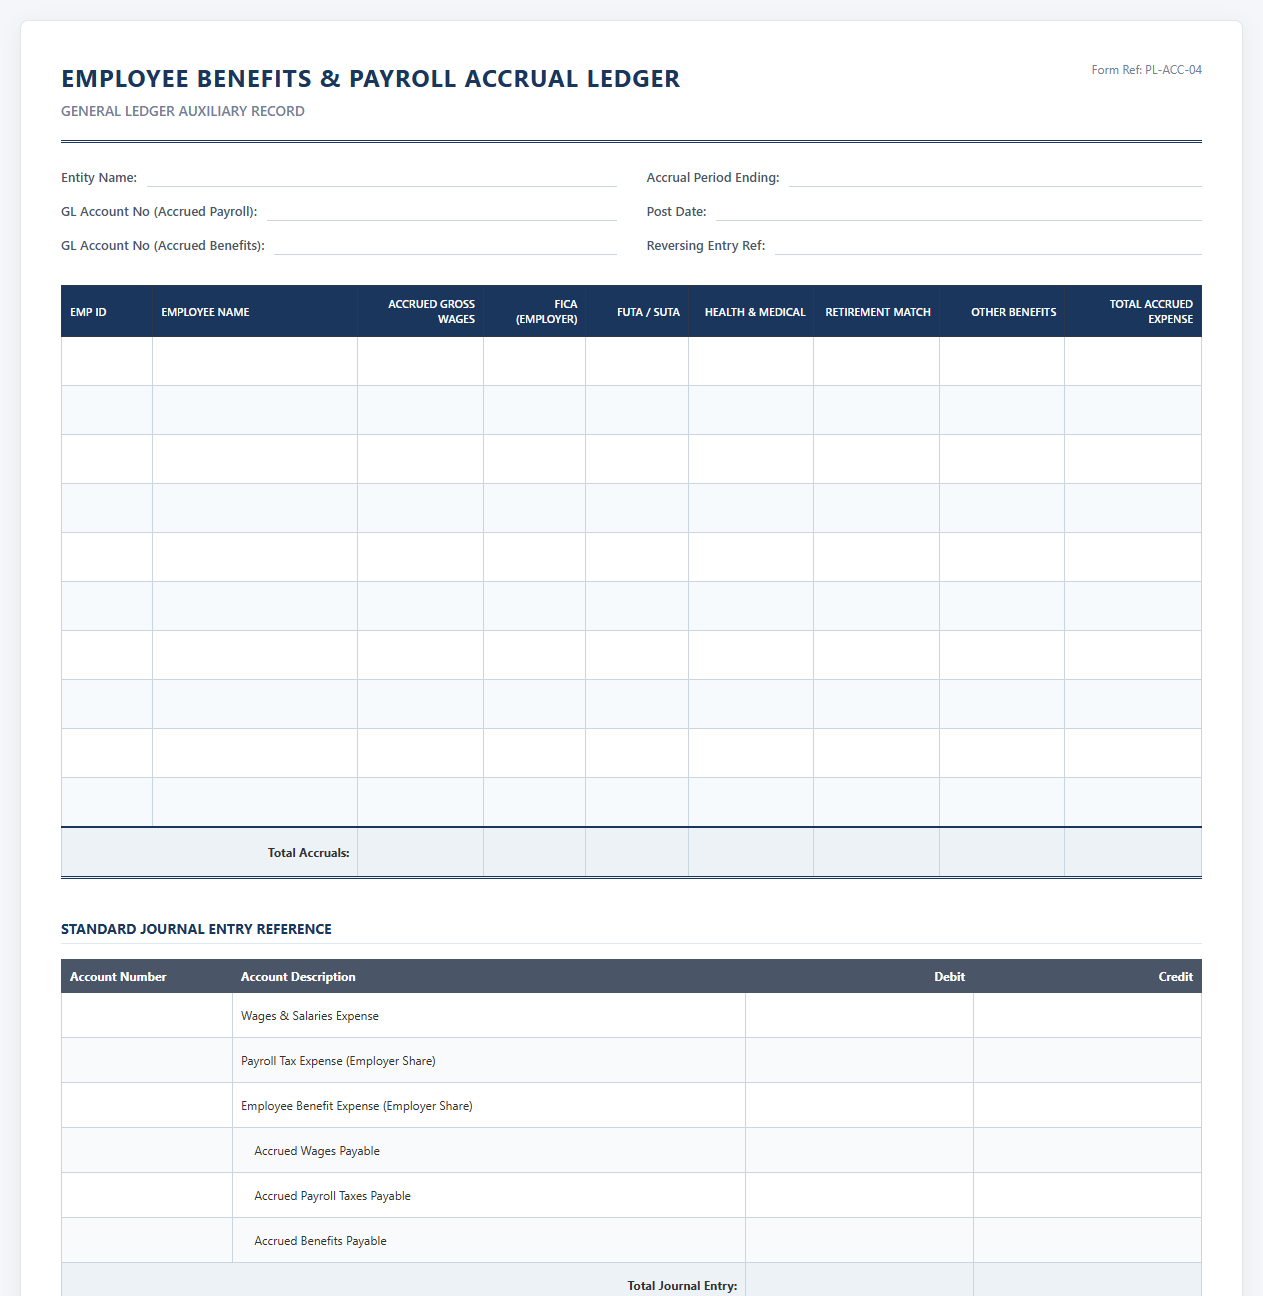 Download: .PDF
Year End Payroll Accrual Reconciliation Worksheet
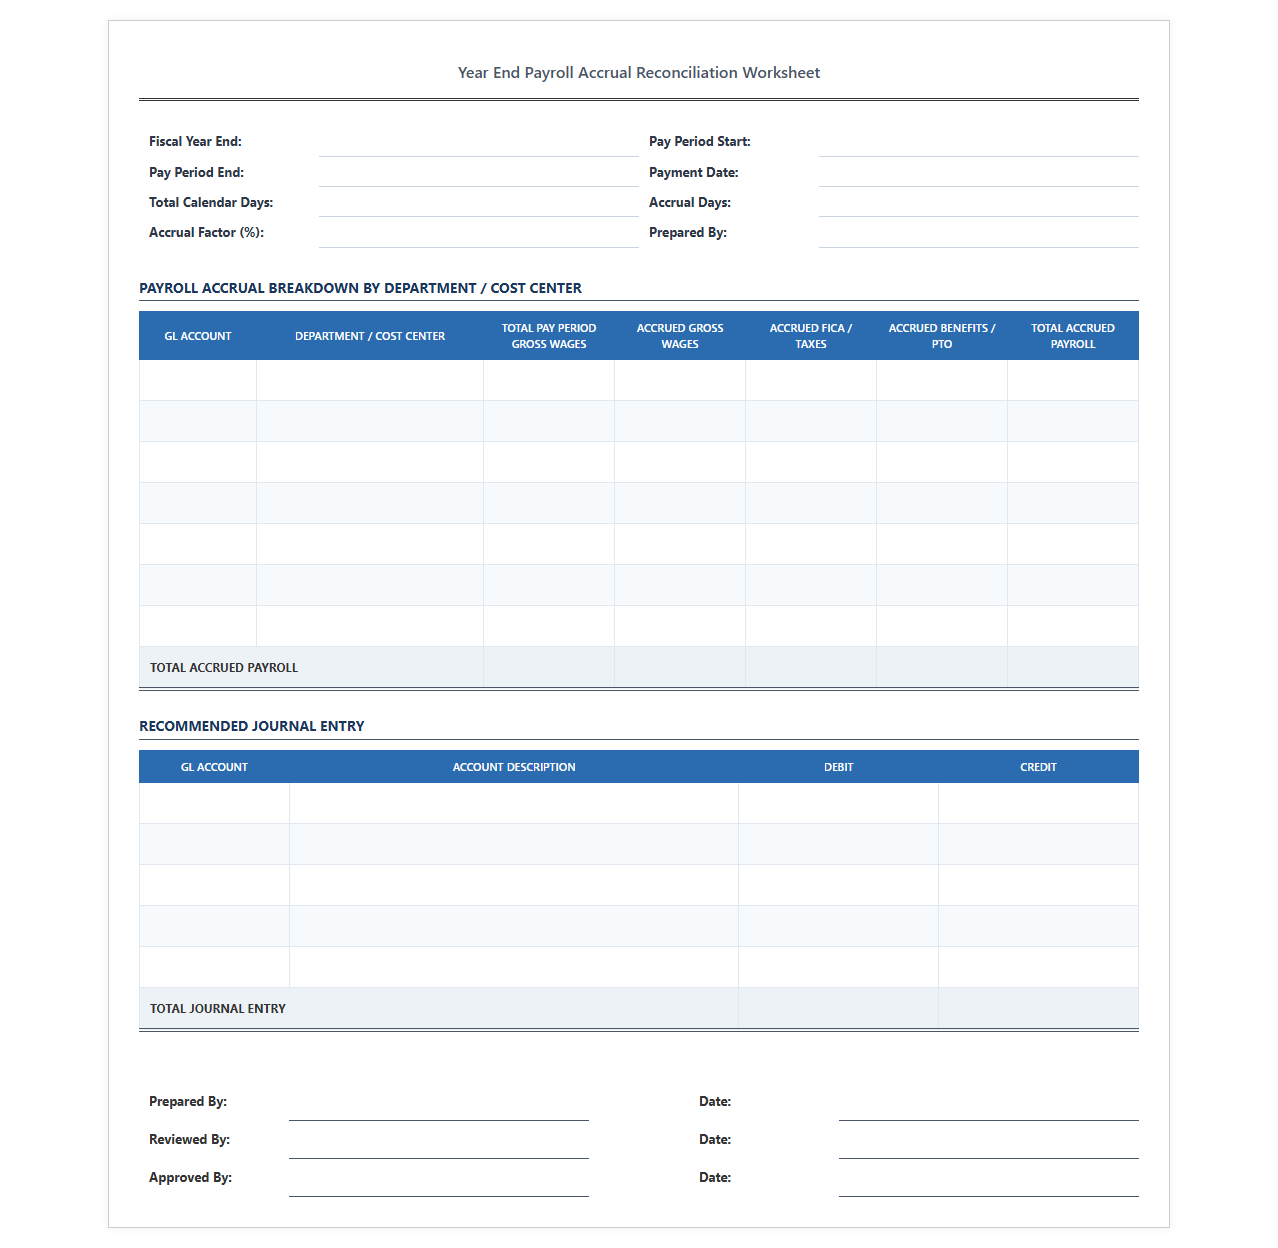 Download: .PDF
Hourly Wages Accrued Ledger Template
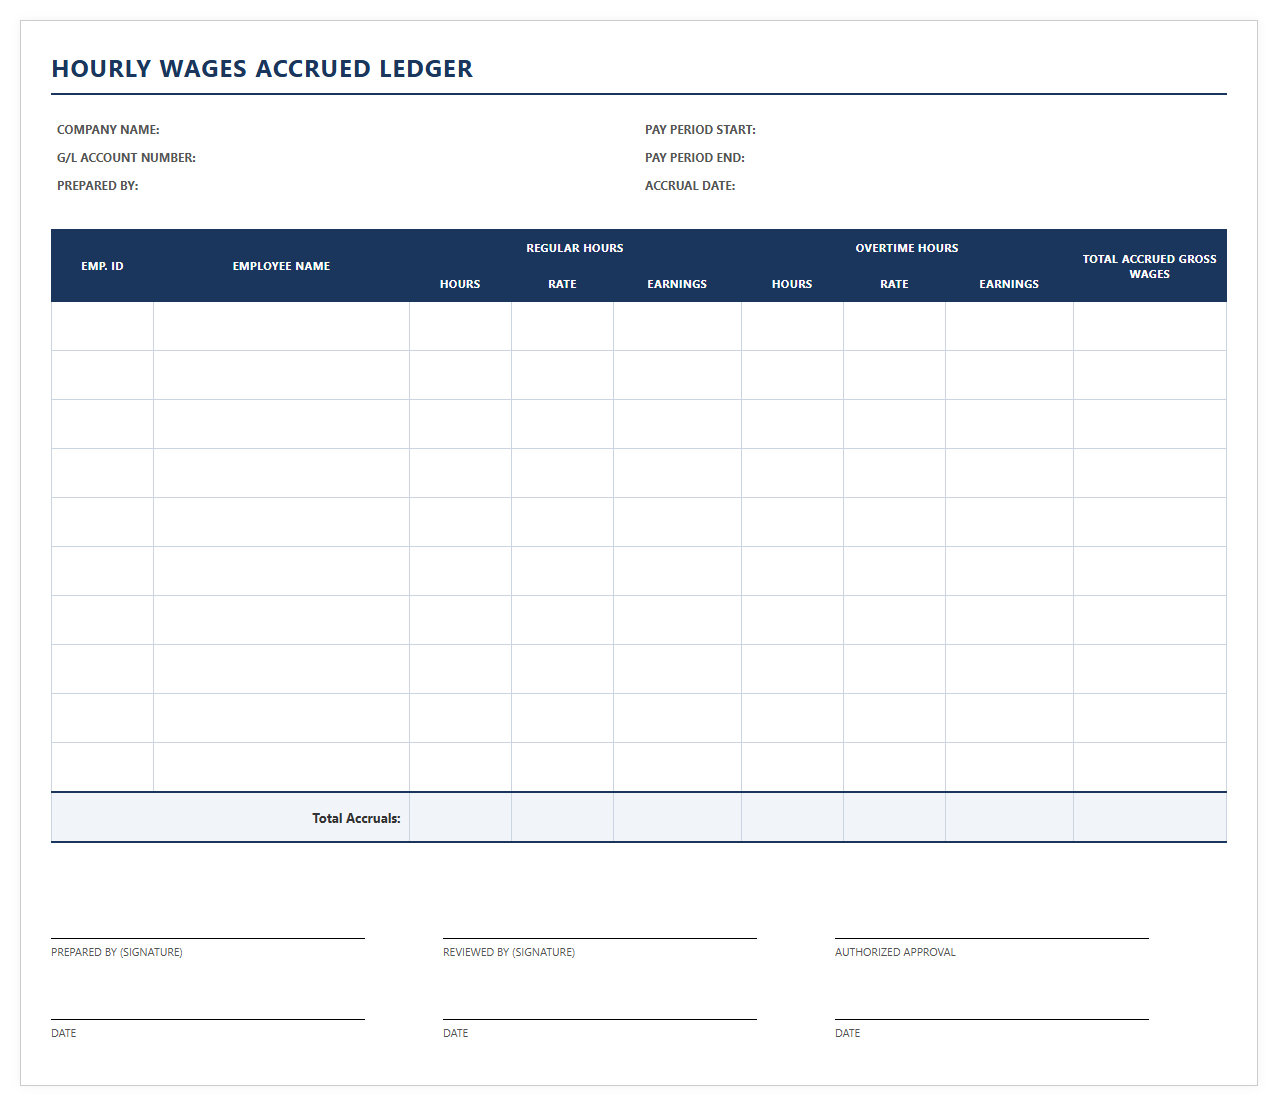 Download: .PDF
Biweekly Payroll Accrual Accounting Ledger
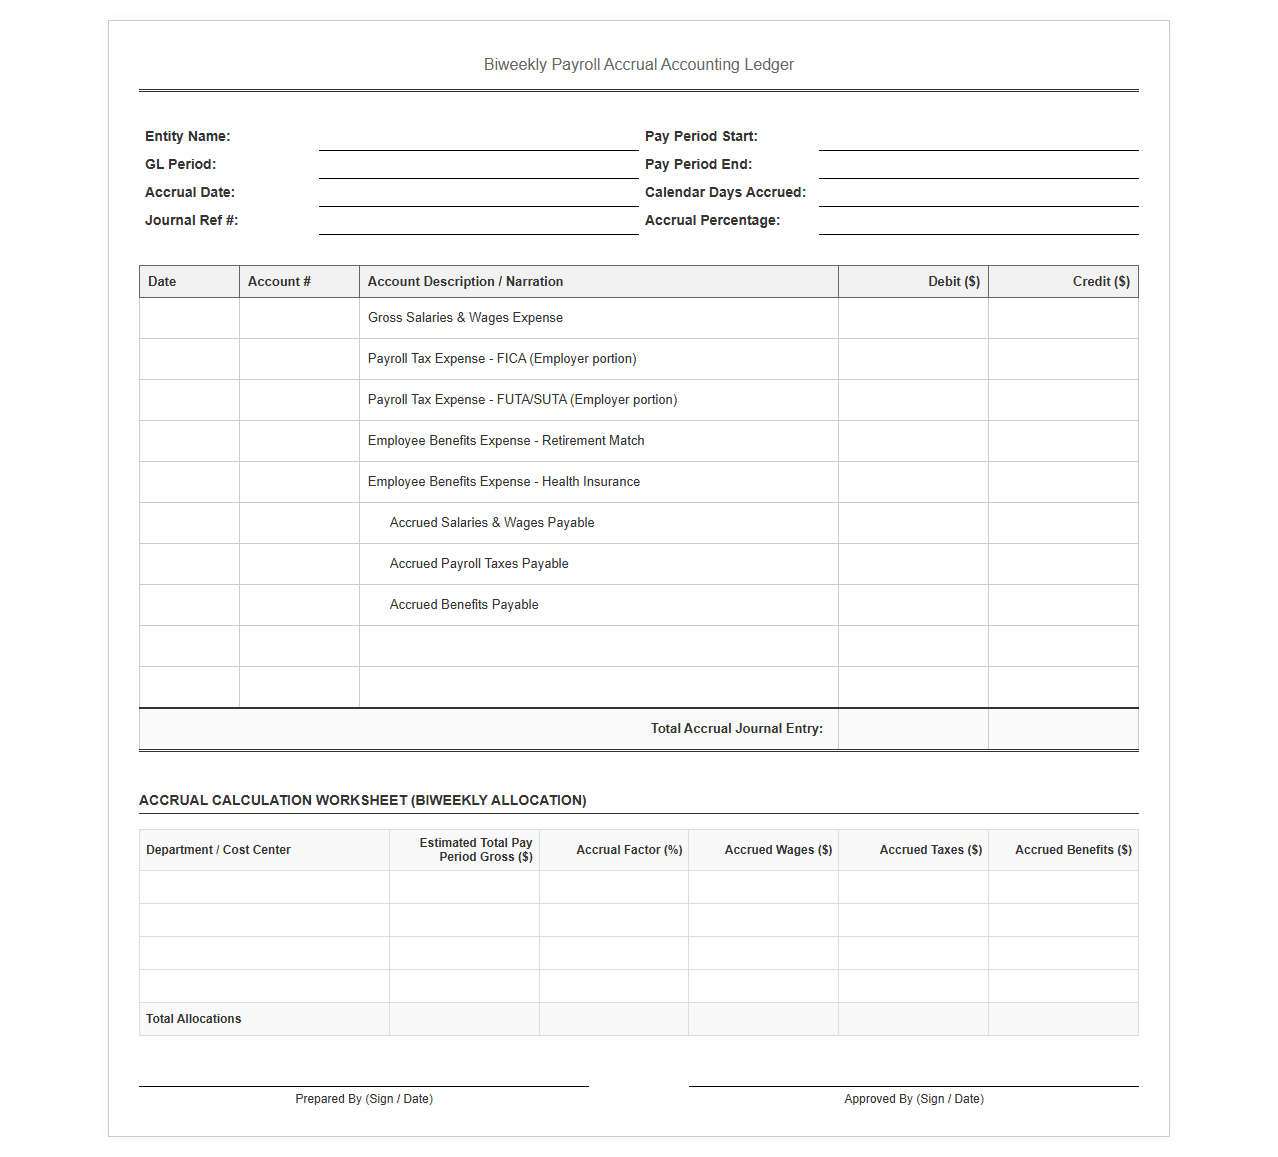 Download: .PDF
Payroll Tax and Accrued Salary Ledger
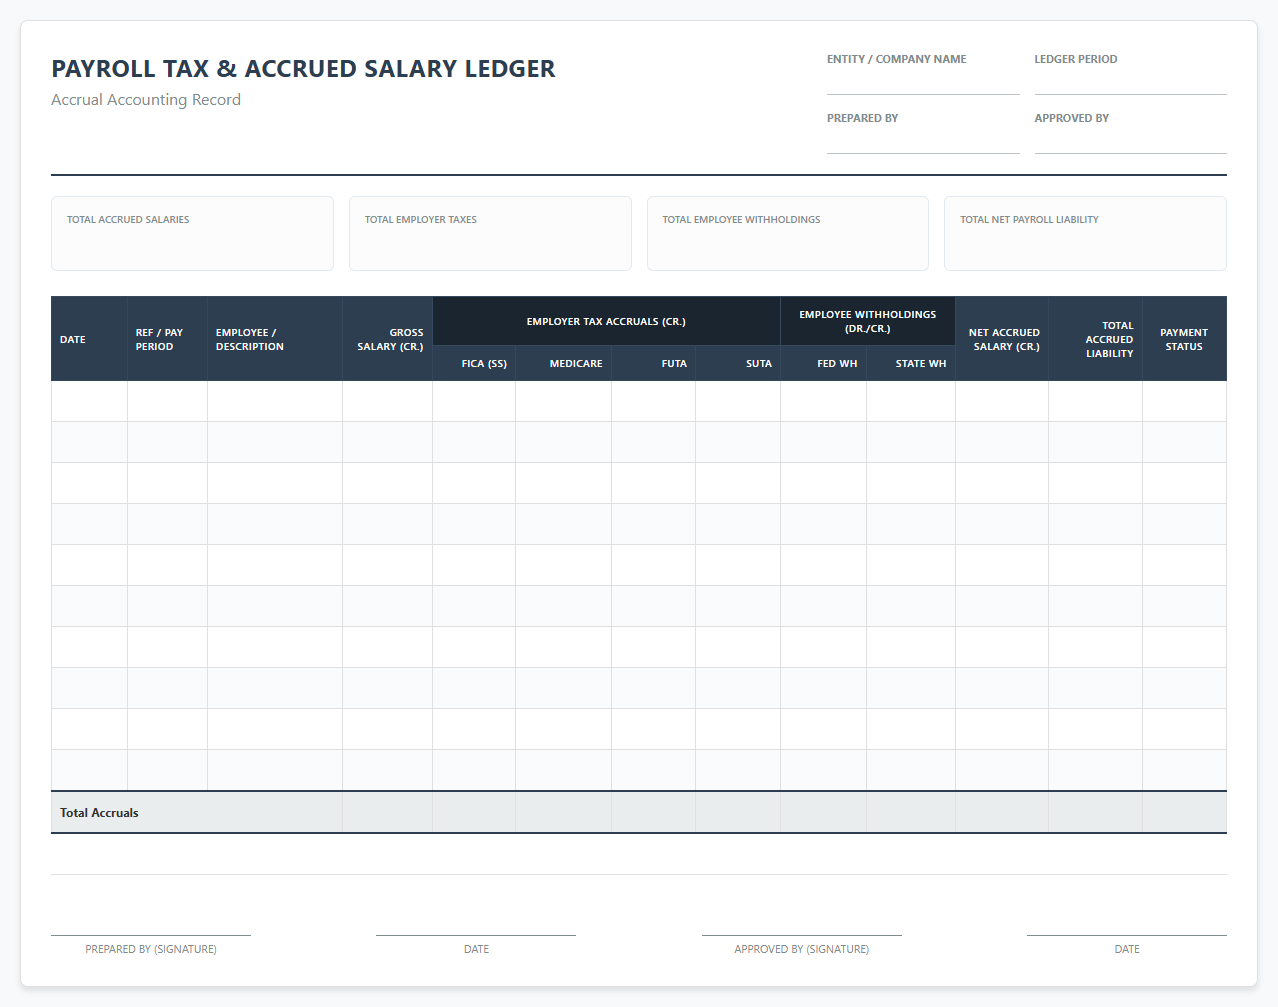 Download: .PDF
Demystifying Accrued Payroll in Modern Accounting
Accrued payroll represents the accumulation of liabilities for employee compensation that has been earned but not yet paid out by the end of a given accounting period. In modern accounting, tracking this liability with precision is vital for maintaining gap-free financial reporting. Under the matching principle of accrual accounting, businesses must record expenses in the period they occur, regardless of when cash changes hands. This ensures that a company's financial statements reflect its true operational costs and liabilities, preventing misleading spikes in profitability and providing stakeholders with a transparent view of the organization's financial health.
The Financial Toll of Manual Ledger Discrepancies
Relying on manual tracking for accrued payroll introduces severe operational risks. Businesses often face hefty tax penalties due to miscalculated withholding rates and filing delays. Furthermore, inaccurate tracking leads to misallocated budgets, where departments make strategic decisions based on skewed expense data. Beyond financial metrics, inconsistent pay schedules or errors in calculation breed employee distrust, eroding organizational morale. Implementing structured, standardized templates is essential to eliminate these human errors and secure financial accuracy.
Anatomizing the Perfect Accrued Payroll Ledger Template
A highly functional payroll ledger template requires dedicated fields to capture every detail of your liabilities. To ensure complete auditability, your ledger must include the following essential columns:
- Pay Period Dates: Start and end dates for the exact work interval being accrued.
- Employee Identifiers: Unique IDs and department codes to facilitate cost-center allocation.
- Gross Earnings: Total wages earned, including base pay, overtime, and bonuses, before any deductions.
- Withholdings: Itemized tax deductions, healthcare premiums, and retirement contributions.
- Net Accrued Amounts: The actual cash obligation owed to employees after subtracting withholdings.
- Employer Taxes: Accrued employer-side liabilities such as FICA and unemployment contributions.
Step-by-Step Guide to Deploying Your Ledger Template
Transitioning from chaotic manual files to a structured digital ledger requires a systematic deployment strategy. Follow these steps to ensure a smooth transition:
- Define the Accounting Period Parameters: Align your ledger structure with your corporate fiscal calendar and set distinct payroll boundaries.
- Input Initial Balances: Transfer outstanding accrual balances from the previous period to establish a clean starting baseline.
- Import Raw Payroll Data: Load verified hourly logs, timesheets, and salary rates directly into the template's staging sheet.
- Map Fields to General Ledger Accounts: Assign appropriate debits and credits corresponding to wages, benefits, and tax liabilities.
- Lock Reference Data and Formulas: Secure tax brackets and operational constants to prevent accidental overwriting during regular data entry.
Formulas and Automation for Error-Free Calculations
To scale your payroll ledger without compounding errors, you must leverage built-in spreadsheet functions. For example, to automatically calculate the progressive tax tier for gross wages in cell B2, use =IFS(B2<=11000, B2*0.10, B2<=44725, 1100+(B2-11000)*0.12). To pull specific employee withholding percentages dynamically from a reference sheet, implement a robust lookup function such as =XLOOKUP(A2, EmployeeDB!A:A, EmployeeDB!C:C, 0). Automating your net pay columns using basic subtraction, like =B2-SUM(C2:E2), protects the integrity of the calculations and guarantees mathematical consistency across hundreds of lines of data.
Streamlining the Reconciliation and Audit Process
Reconciling accrued payroll ledger balances with physical bank transactions is the ultimate defense against financial discrepancies. Accountants must regularly cross-verify the ending accrual balances against the bank's clearing account entries. These steps guarantee that the expenses reported on your profit and loss statements match your cash disbursements during subsequent pay cycles.
"Internal control standard: Always verify that the balance in the Accrued Payroll liability account at the end of the month equals the gross wages earned by employees but unpaid as of the final calendar day."
Sustaining Accuracy with Continuous Payroll Auditing
Maintaining the long-term integrity of your financial systems requires a continuous approach to ledger hygiene. Schedule monthly internal reviews to check for structural changes in tax laws and verify the accuracy of the underlying formulas. Investing in ongoing education for your accounting staff ensures everyone is aligned on protocol and ledger maintenance. Consistently updating your workflows guarantees that financial statements remain compliant, transparent, and accurate. Prioritizing systemic precision transforms payroll from a routine administrative burden into an asset for strategic financial planning.
Leave a comment