Navigating the intricate labyrinth of partnership capital account reporting often leaves tax professionals grappling with disparate data and inconsistent methodologies. This operational strain has intensified with the IRS's stringent mandates requiring capital accounts to be reported strictly on a partner-by-partner tax basis.
Deploying structured return templates, however, grants tax departments a standardized framework that dramatically reduces reconciliation errors and mitigates audit exposure. It is important to stipulate that while these templates do not replace bespoke tax counsel, they serve as a critical operational guardrail to ensure mathematical and structural alignment. For instance, managing complex Section 704(b) book-to-tax adjustments and tracking revaluations becomes highly systematic when driven by standardized inputs.
This article explores how to deploy these structured templates, streamline your data-gathering workflows, and master the nuances of modern partnership reporting.
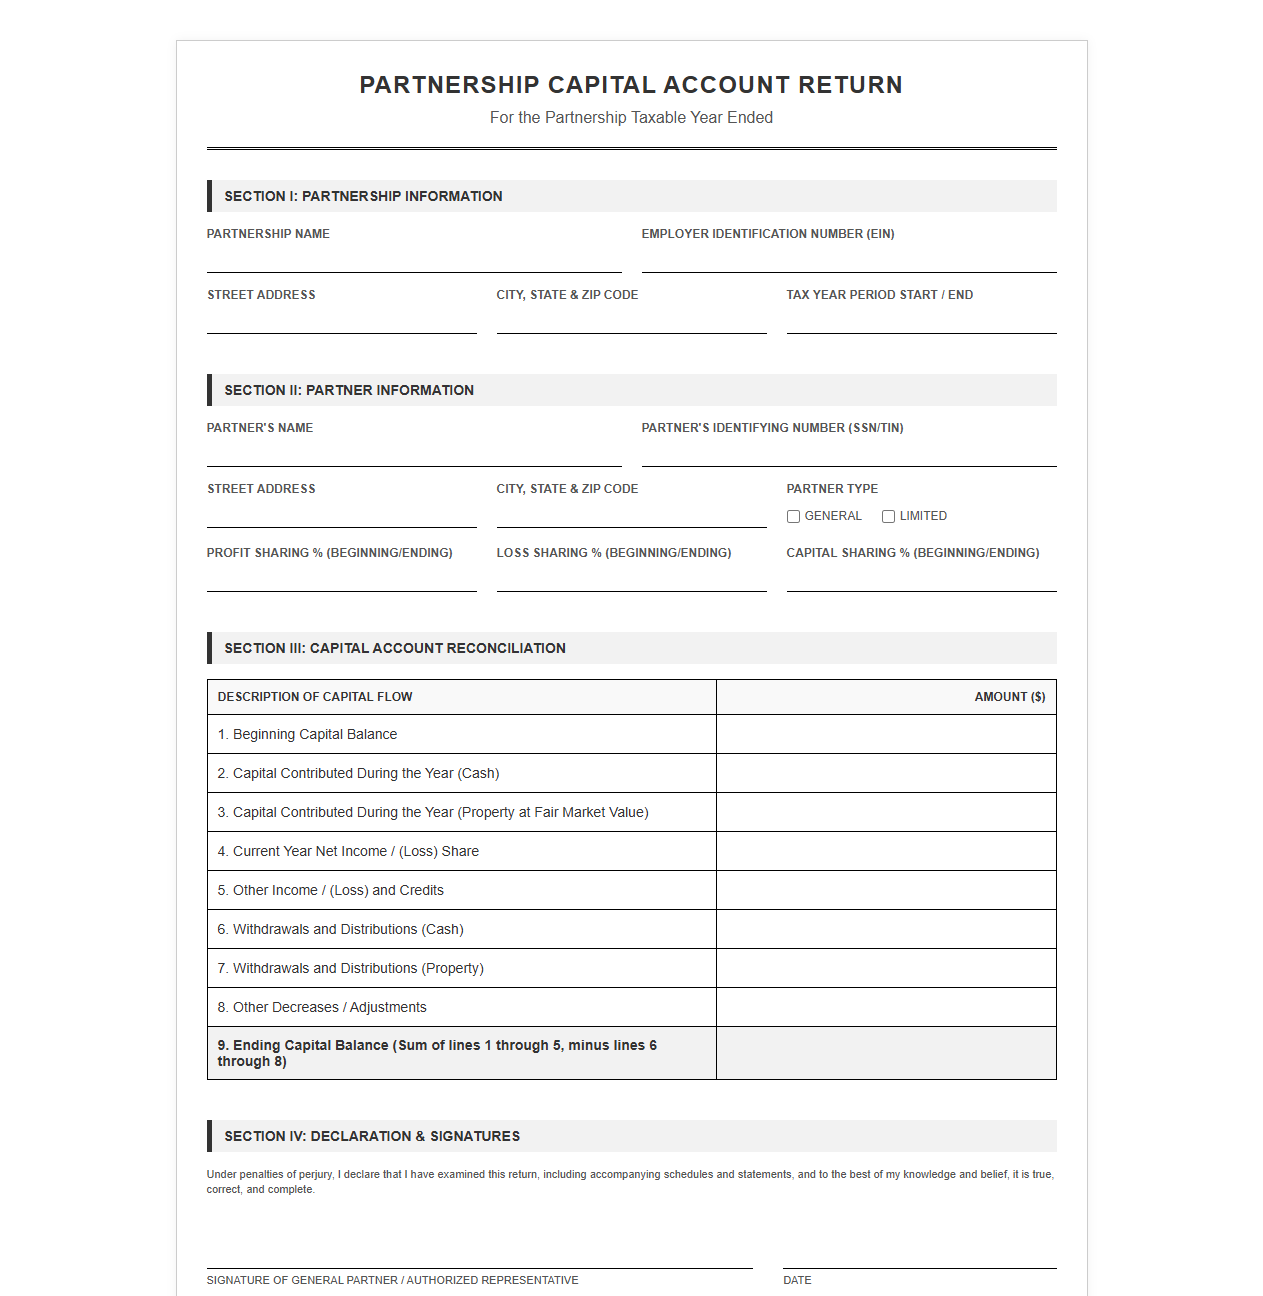
Partnership Capital Account Return Form
 Download: .PDF
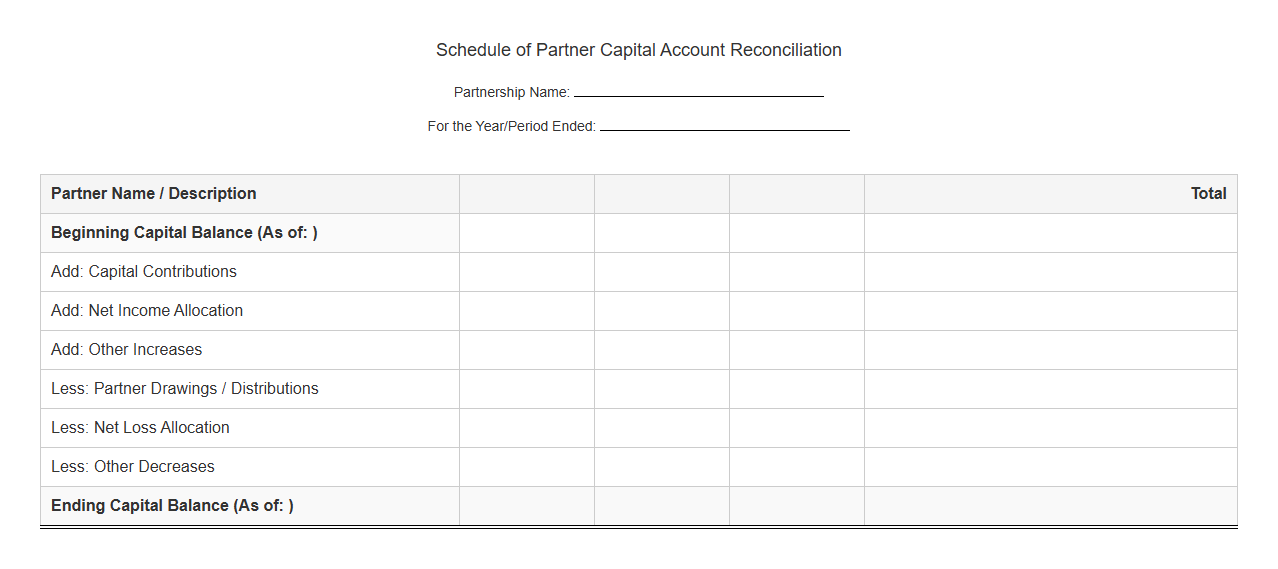
Schedule of Partner Capital Account Reconciliation
 Download: .PDF
Annual Partnership Capital Account Statement Template
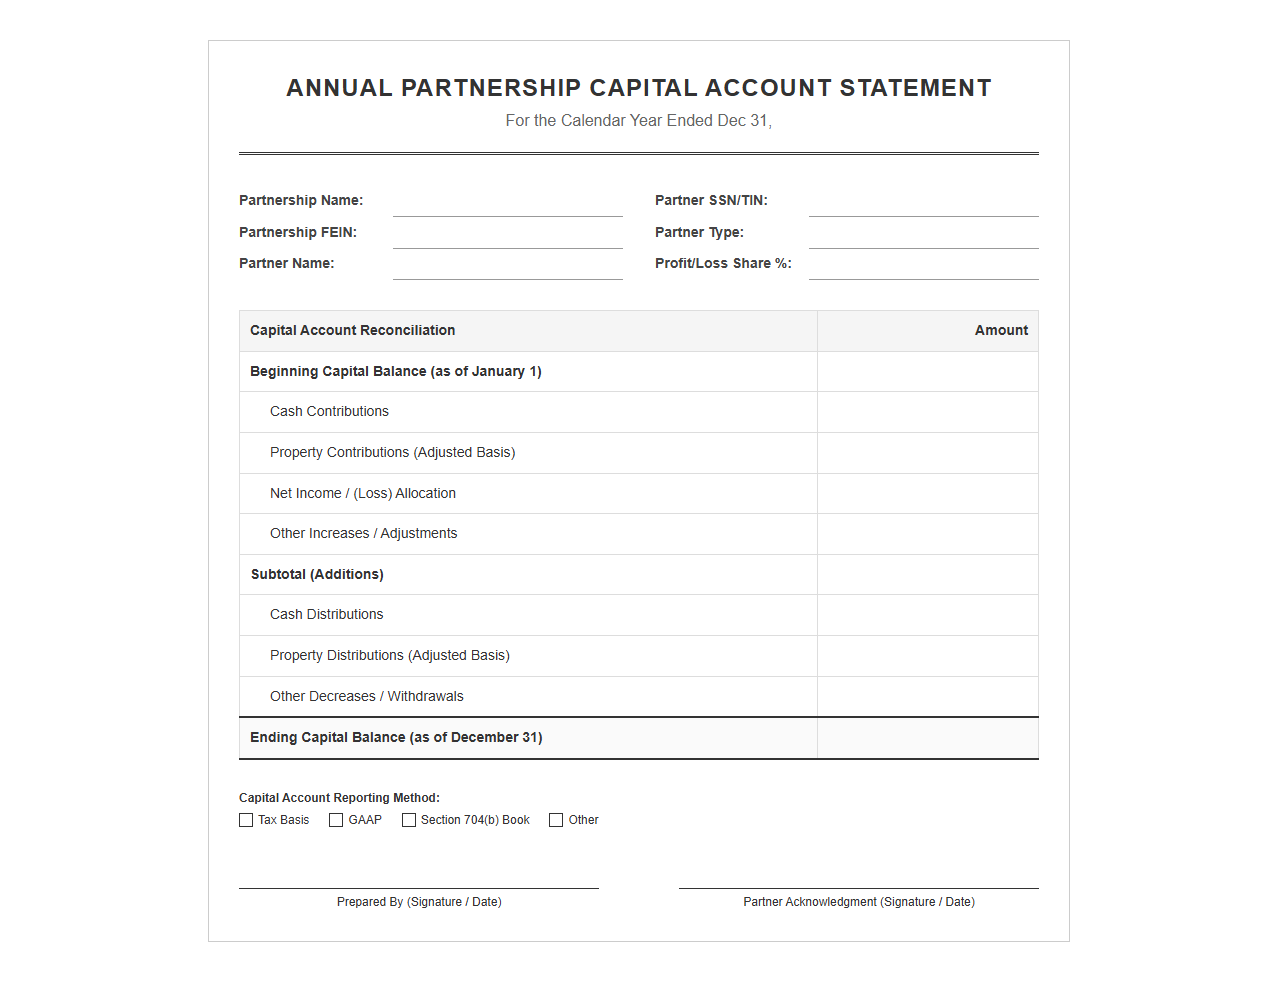 Download: .PDF
Partnership Capital Account Distribution and Return Sheet
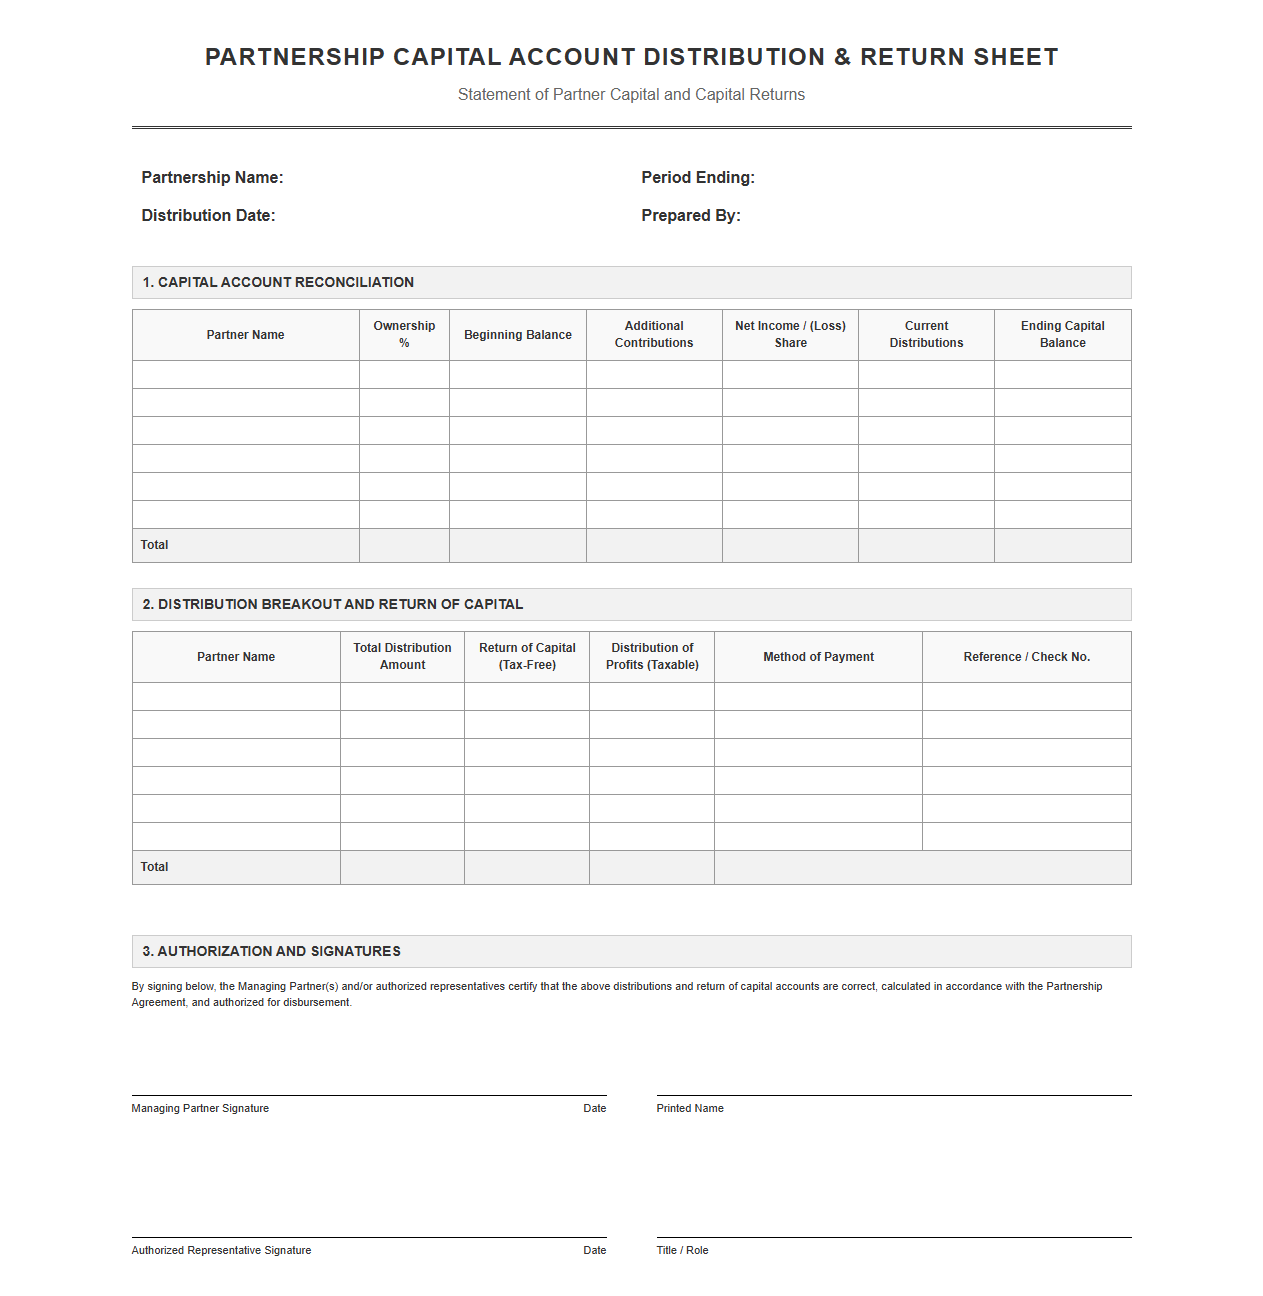 Download: .PDF
Partner Capital Contribution and Withdrawal Ledger
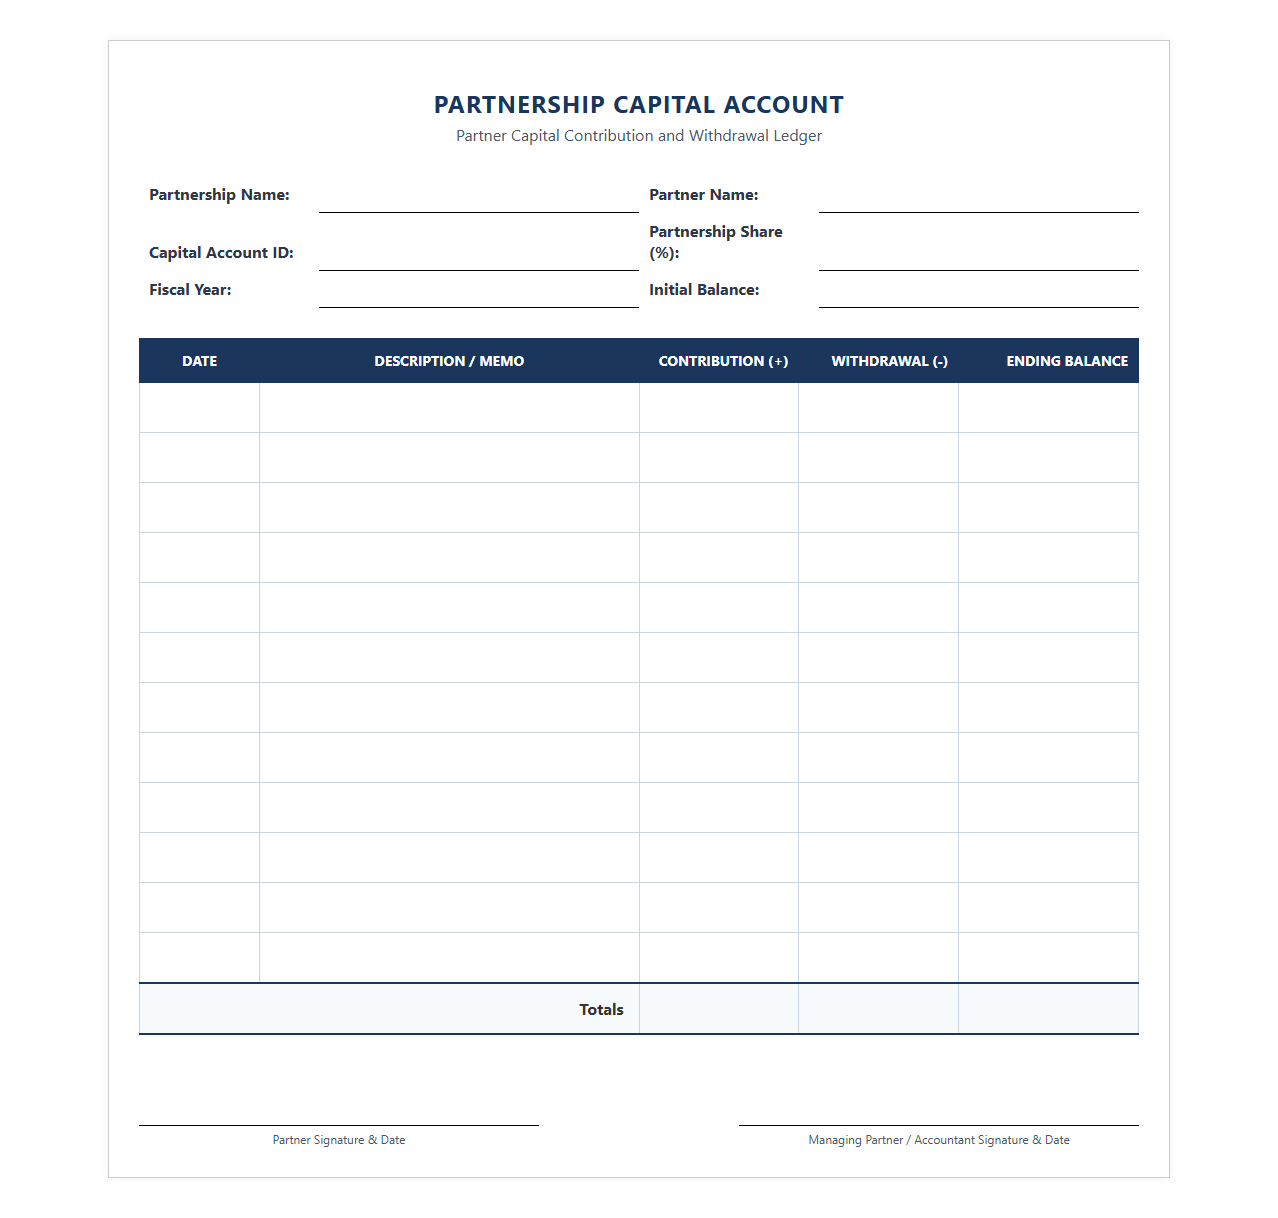 Download: .PDF
Partnership Capital Account Balance Declaration Template
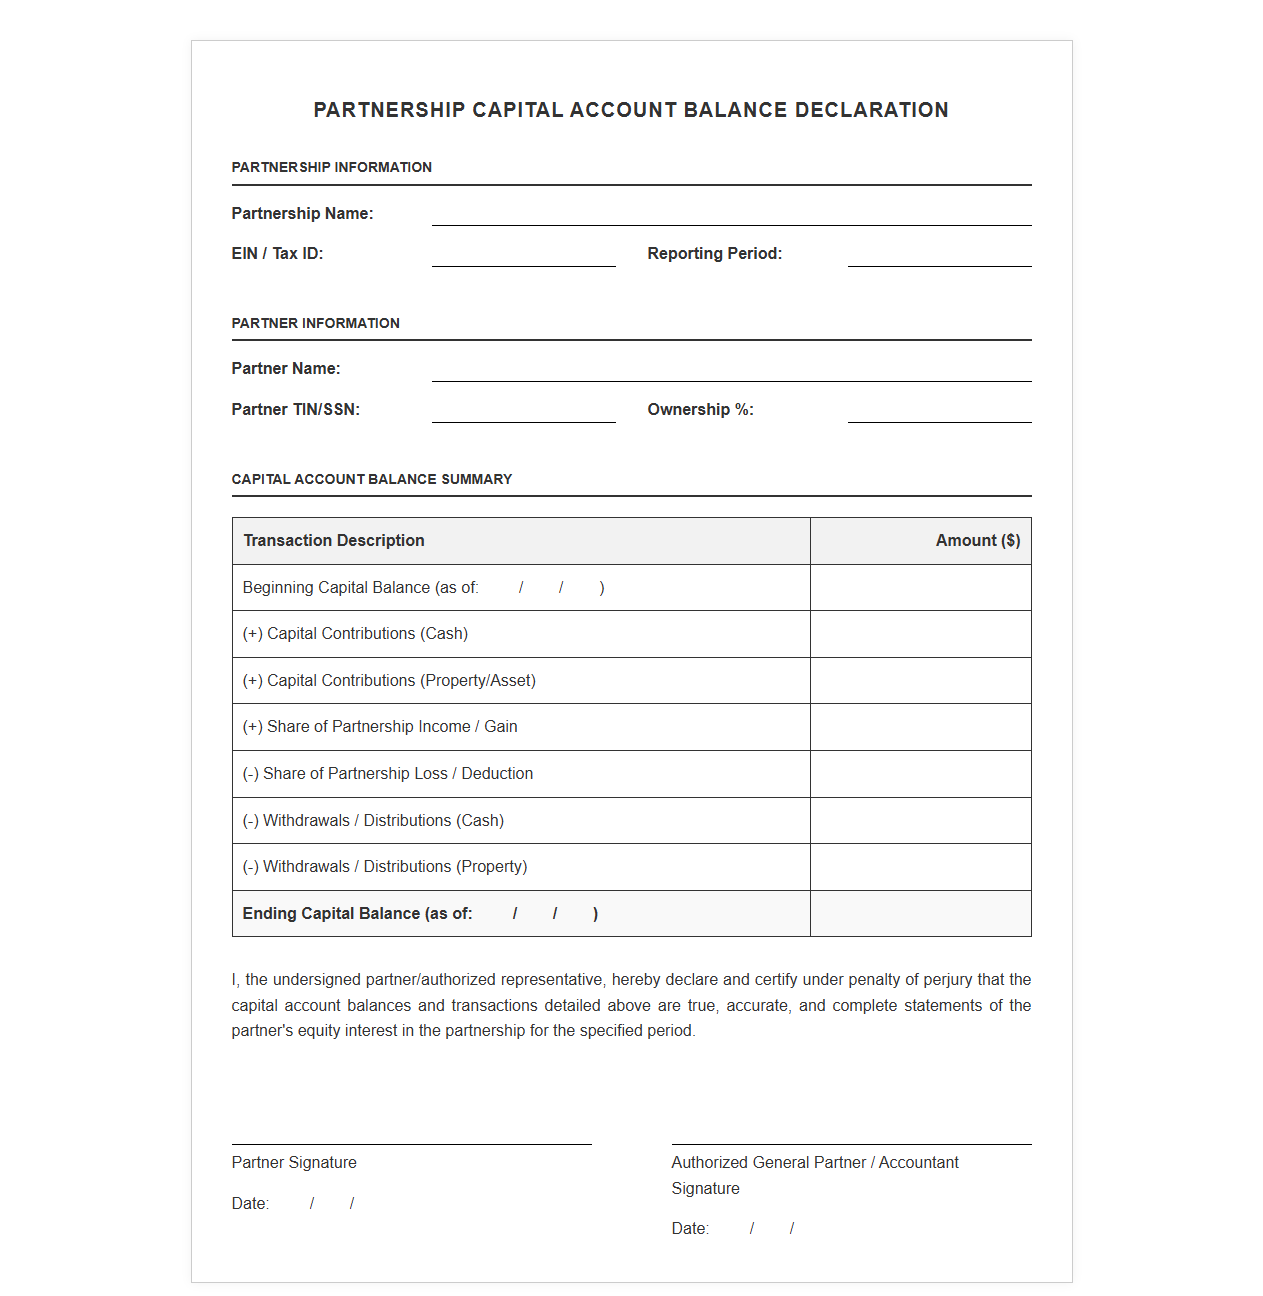 Download: .PDF
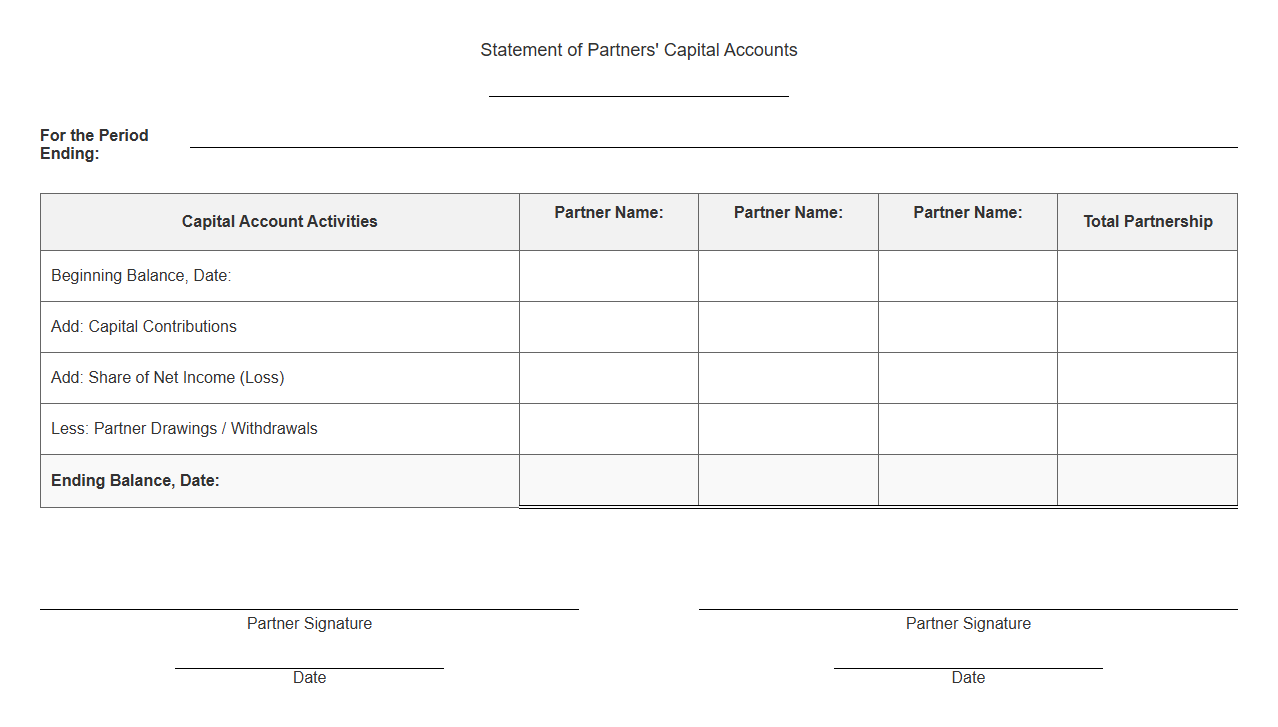
Statement of Partners Capital Accounts Form
 Download: .PDF
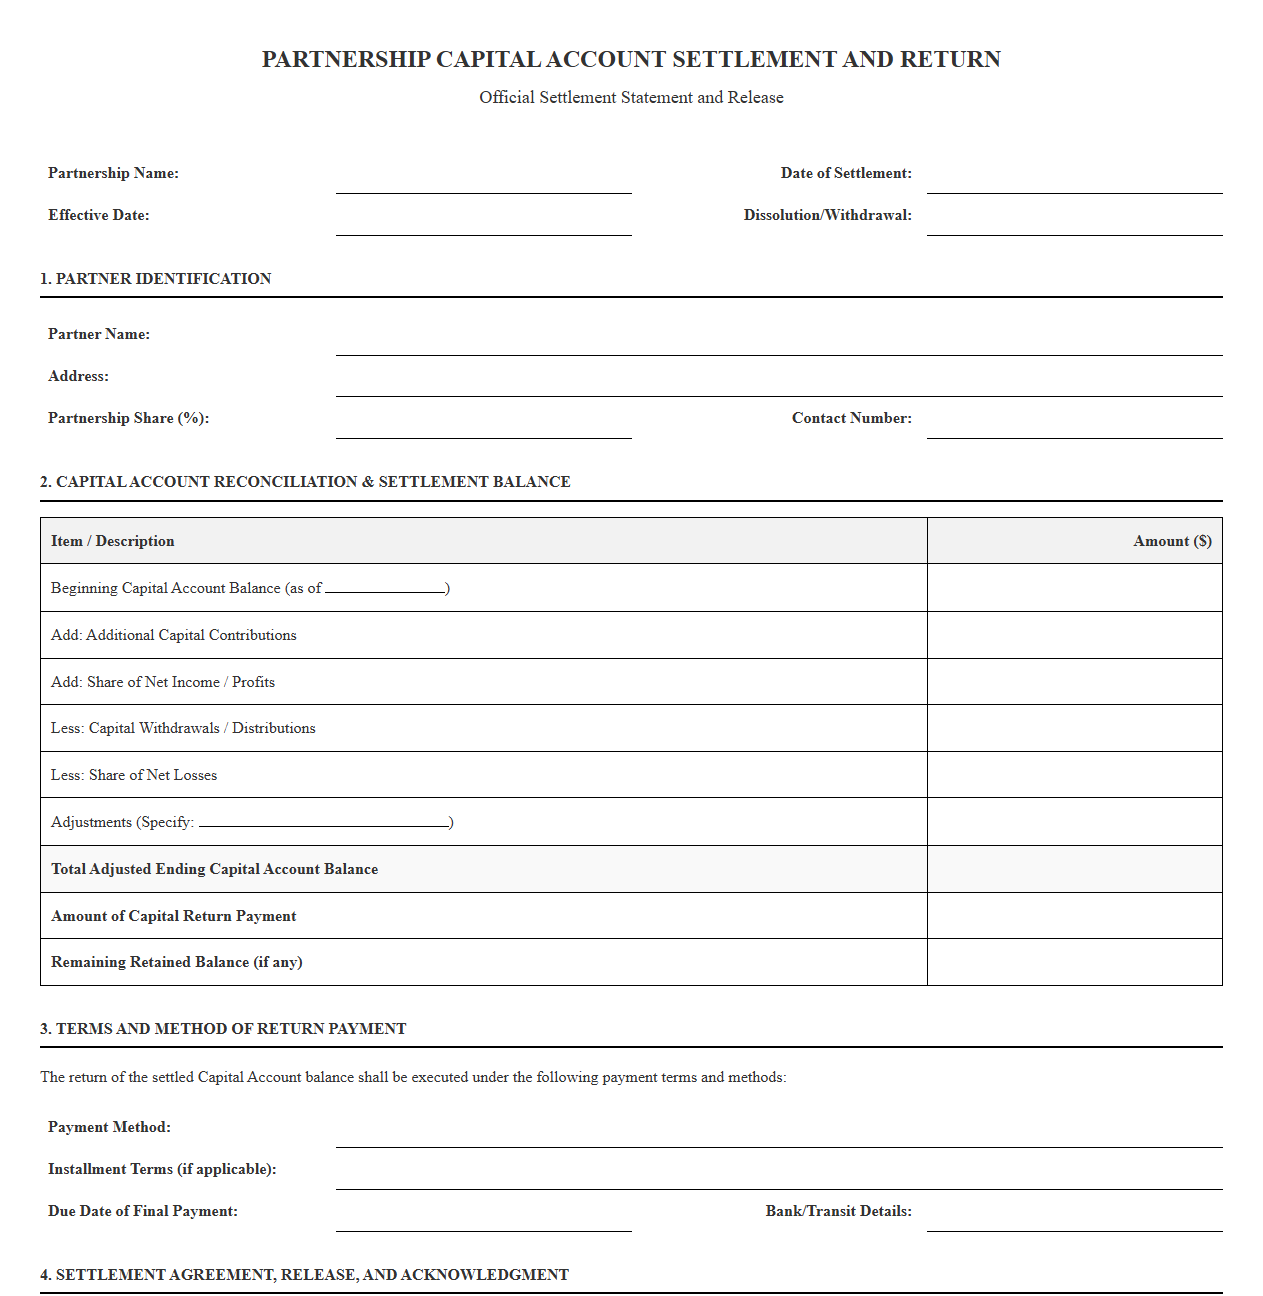
Partnership Capital Account Settlement and Return Template
 Download: .PDF
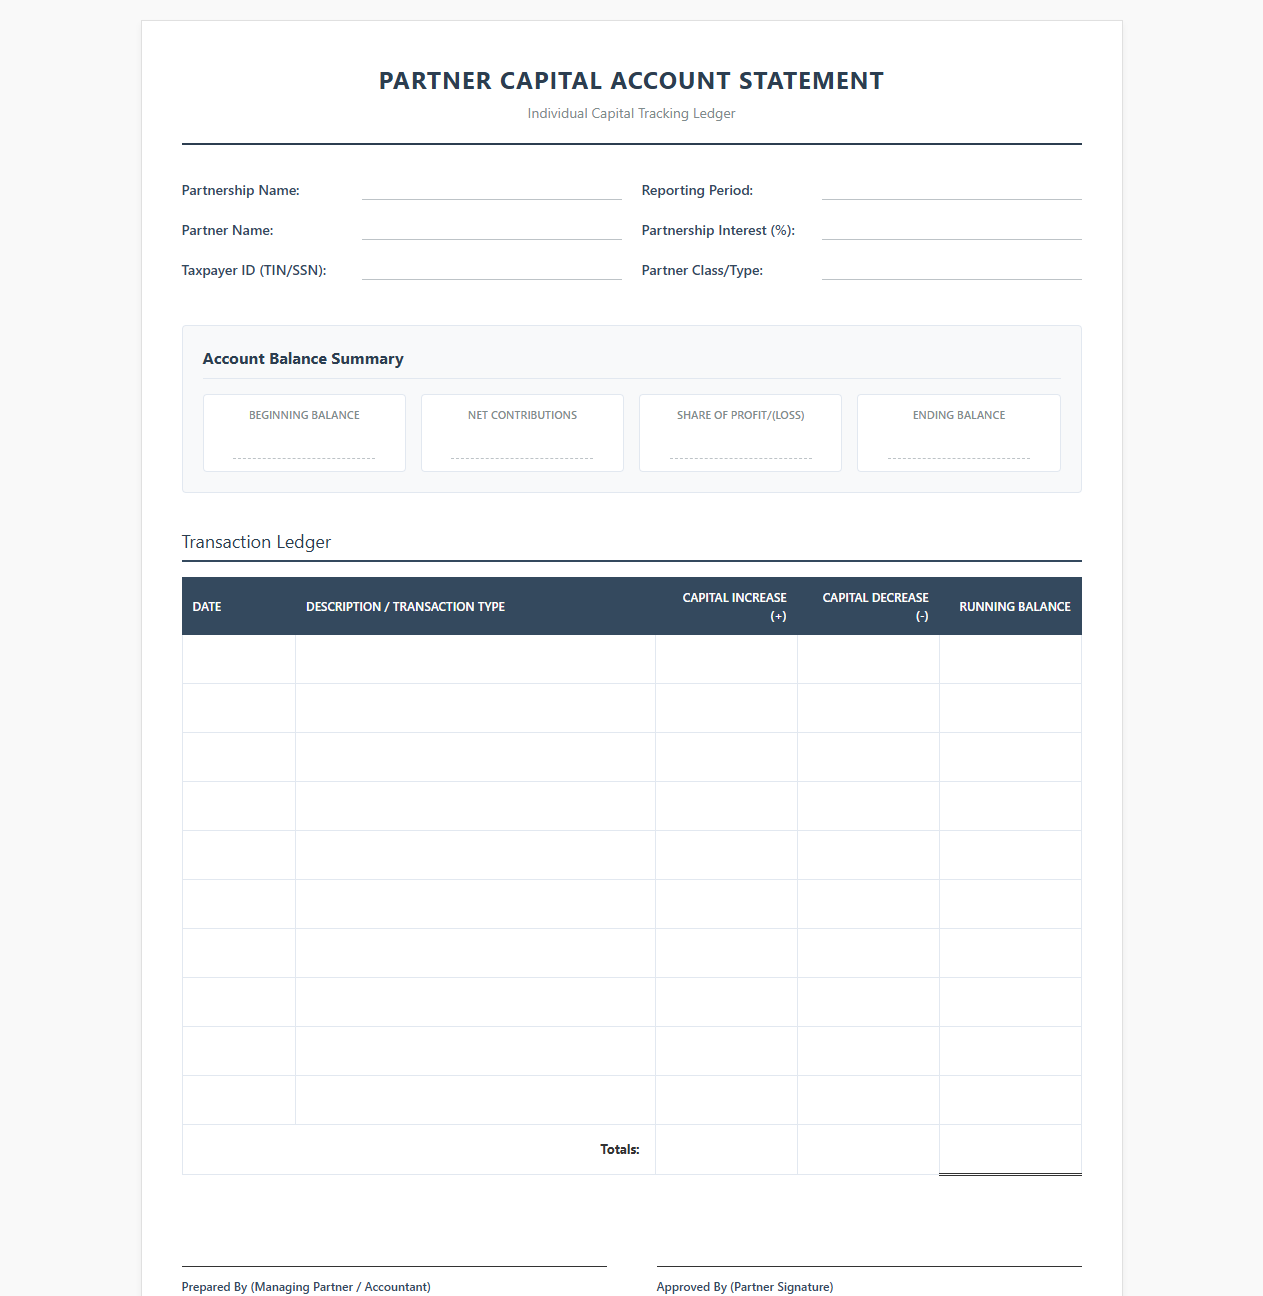
Individual Partner Capital Account Tracking Sheet
 Download: .PDF
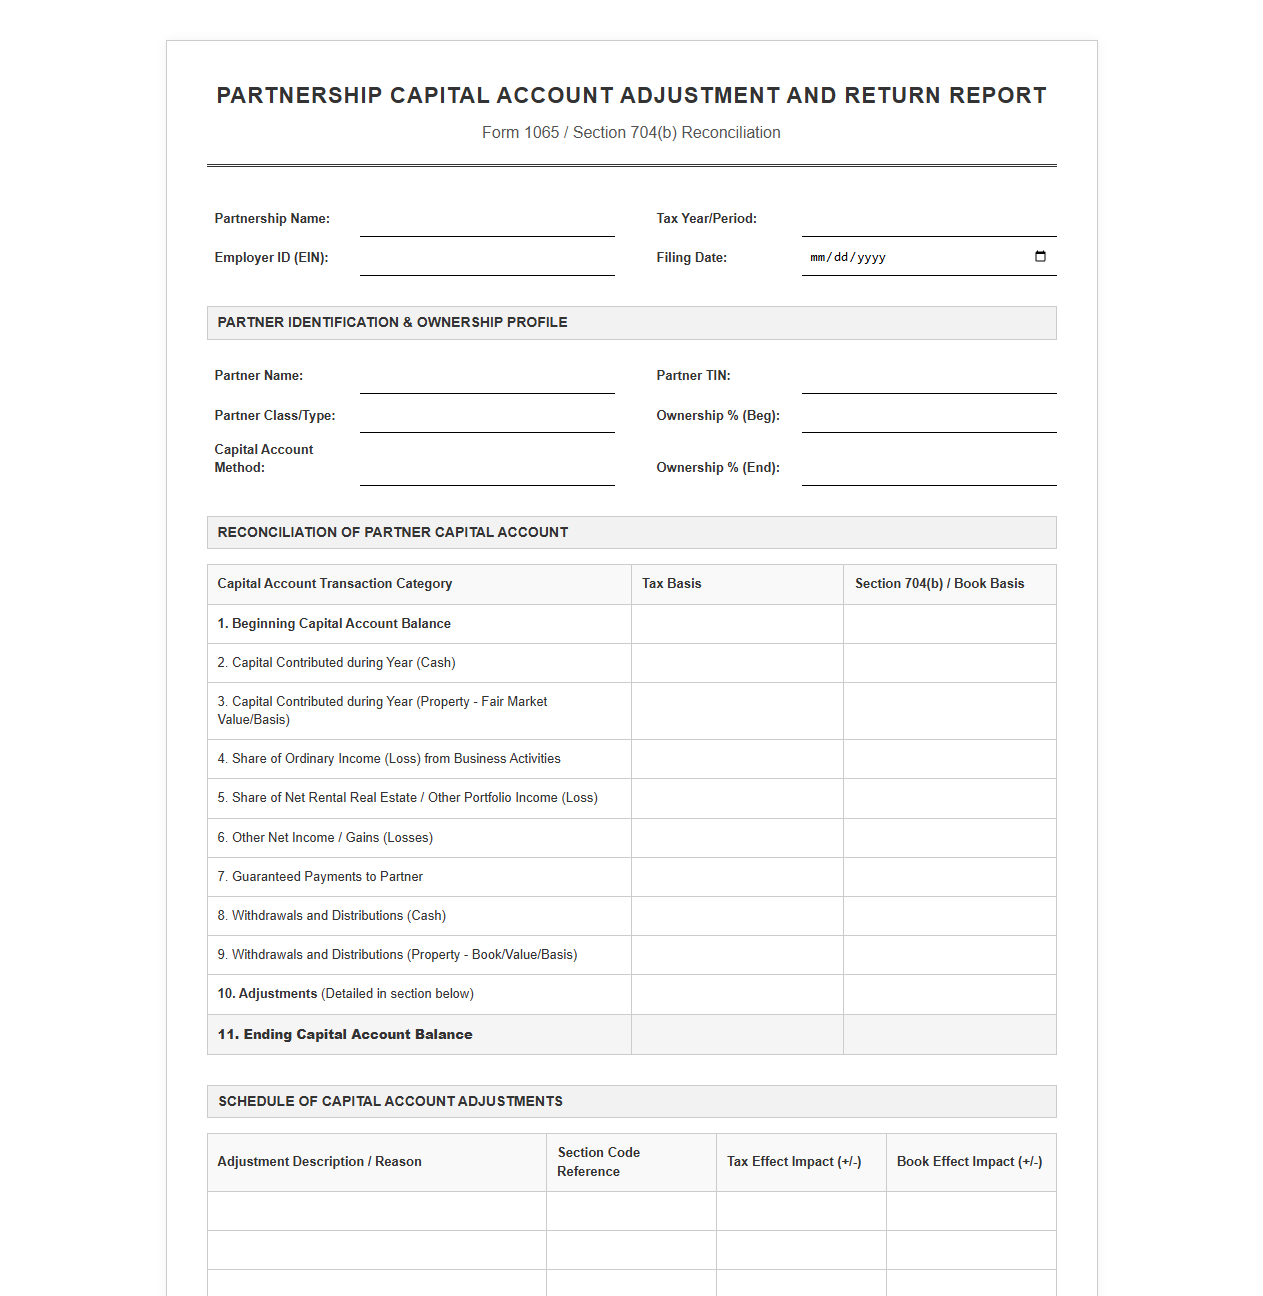
Partnership Capital Account Adjustment and Return Report
 Download: .PDF
Navigating the Maze of Partnership Capital Account Reporting
Partnership taxation is widely regarded as one of the most intricate areas of the tax code. Navigating the labyrinth of partnership capital accounts requires a deep understanding of both financial accounting and evolving regulatory frameworks. Historically, partnerships maintained these accounts using Generally Accepted Accounting Principles (GAAP) or other transactional books. However, the recent, decisive shift mandated by the IRS toward the transactional tax basis method has fundamentally altered the compliance landscape. Tax professionals now face the monumental challenge of reconciling historical book-tax differences, reconstructing historical records, and ensuring that every partner's tax basis capital account is reported with absolute precision.
The Catalyst: Regulatory Mandates and IRS Scrutiny
The days of relying on spreadsheet-based, ad-hoc tracking methods for partner equity are officially over. The driving force behind this shift is the Internal Revenue Service's increased focus on transparency, specifically designed to identify tax shelters and mismatched reporting. By enforcing standardized transactional reporting, the IRS can easily cross-reference partner-level disclosures with partnership-level returns.
"Partnerships must report partner capital accounts on Schedule K-1 using the tax basis method. If a partnership fails to report capital accounts under this method, it may be subject to penalties under Section 6722 for failure to furnish correct payee statements."
This mandate removes any room for ambiguity. Traditional, offline workbooks are simply too fragile to withstand the rigorous audit standards now applied to partnership filings. Firm compliance now demands a structured, repeatable process to avoid costly penalties and audit triggers.
Deconstructing the Core Transactional Complexities
Maintaining accurate capital accounts is highly complex due to the continuous flow of unique financial events. To keep tax basis capital accounts accurate, tax preparers must meticulously track several variables:
- Partner Contributions and Distributions: Differing tax treatments for cash versus appreciated property contributions.
- Section 704(c) Allocations: Tracking the book-to-tax disparities that occur when property with built-in gain or loss is contributed to the partnership.
- Section 754 Elections: Managing step-ups or step-downs in the basis of partnership property under Sections 743(b) and 734(b).
- Asset Revaluations: Accounting for "reverse 704(c)" allocations when new partners enter or existing partners exit the venture.
Empowering Compliance through Structured Return Templates
To mitigate the risks of manual tracking, forward-thinking tax practices are adopting structured return templates. These templates use standardized database schemas to ingest trial balance data, automatically apply tax-specific depreciation schedules, and calculate partner-level allocations according to predetermined partnership agreements.
By standardizing how data is input and processed, firms can transition from reactive troubleshooting to proactive quality control, freeing up valuable billable hours for strategic planning.
Best Practices for Implementing Template Workflows
Transitioning to a structured template system requires a deliberate implementation strategy to avoid disrupting busy-season workflows.
- Standardize the Chart of Accounts: Align the partnership's trial balance with the template's data mapping fields to ensure seamless data ingestion.
- Establish Validation Rules: Build hard-coded checks within your templates to verify that the sum of partner-level capital accounts reconciles to the partnership's Schedule M-2.
- Integrate with Tax Prep Software: Ensure your templates can export clean, structured XML or CSV files that directly populate your tax preparation software.
Proactively Resolving Common Template Pitfalls
Even with advanced templates, certain high-risk areas demand human oversight. One of the most frequent errors occurs during partner transfers. When a partner sells their interest, the transfer of capital must be carefully executed within the template to ensure the buyer inherits the seller's exact capital account balance.
Additionally, mismatched beginning capital balances represent a major red flag for IRS automated matching systems. Before running allocation calculations, always verify that the starting balances in your template match the ending balances from the prior year's filed return. Taking the time to resolve these discrepancies in transfer treatment early prevents systemic errors from compounding throughout the return.
The Horizon of Automated Partnership Tax Reporting
The future of partnership tax compliance lies in end-to-end automation. As API integrations become the industry standard, data will flow seamlessly from accounting software directly into tax templates and filing engines without manual file transfers. Furthermore, artificial intelligence will soon play a vital role in identifying anomalous transactions and suggesting corrective adjustments before a return is ever finalized. By embracing these structured schemas and automated workflows today, tax professionals can turn a complex regulatory hurdle into a highly efficient, value-driven advisory service.
Leave a comment