Organizations facing suspected fraud or partnership disputes often struggle to protect themselves from liability due to vaguely defined engagement terms. As financial crimes grow increasingly complex, establishing a rigorous administrative foundation for investigative work is paramount. Utilizing structured Forensic Accounting Service Agreement Templates grants both practitioners and clients the legal clarity and peace of mind required during high-stakes corporate disputes.
While these templates serve as invaluable frameworks to streamline your workflow during sensitive embezzlement audits or asset recovery investigations, they must be treated as baselines that require customization to satisfy local jurisdictional regulations.
Below, we examine the critical clauses, risk-mitigation strategies, and essential templates designed to secure your next forensic engagement and protect your professional interests.
Forensic Accounting Services Agreement
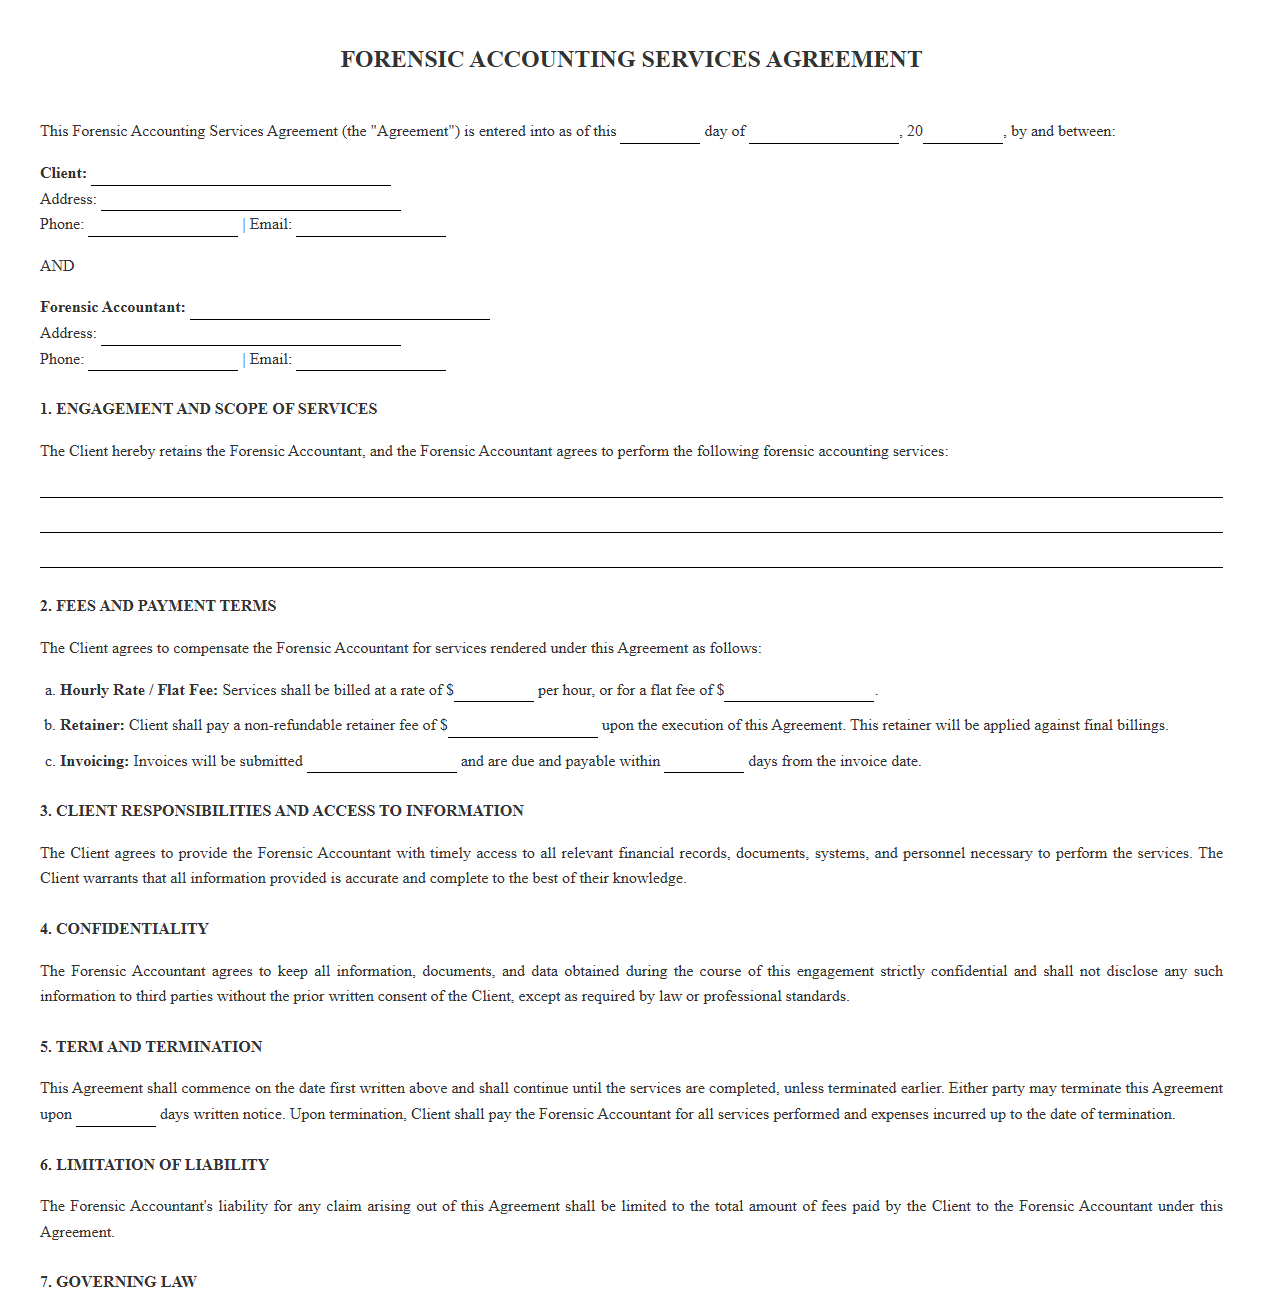 Download: .PDF
Forensic Investigation and Accounting Service Contract
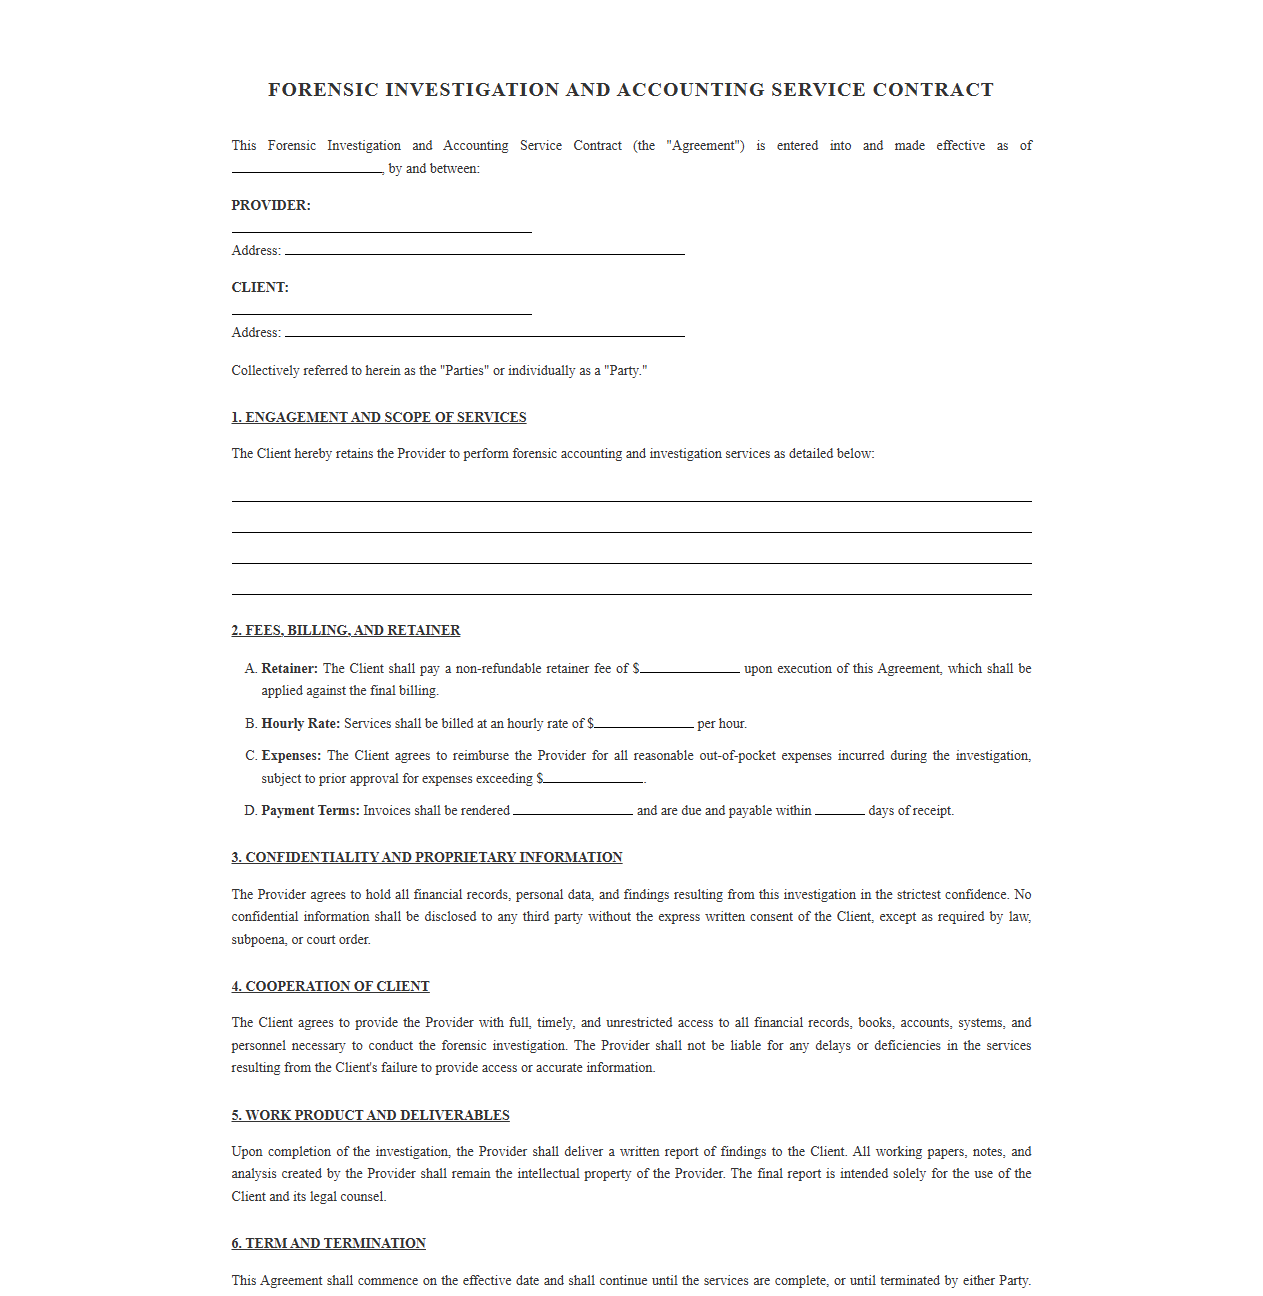 Download: .PDF
Standard Agreement for Forensic Audit Services
 Download: .PDF
Forensic Accountant Engagement Letter Template
 Download: .PDF
Financial Investigation and Forensic Accounting Agreement
 Download: .PDF
Retainer Agreement for Forensic Accounting Services
 Download: .PDF
Litigation Support and Forensic Accounting Contract
 Download: .PDF
Professional Services Agreement for Forensic Accounting
 Download: .PDF
Introduction to Forensic Accounting Agreements in Risk Management
In the high-stakes realm of financial investigations, clarity and mutual understanding serve as the primary defense against legal and operational complications. Robust service agreements establish the baseline for financial risk mitigation, protecting both the investigating firm and the client from misaligned expectations. A meticulously drafted forensic engagement letter acts as a legally binding framework that secures operational alignment from day one.
By defining exact parameters, these agreements govern how sensitive data is managed, how findings are presented, and how potential conflicts are mediated. Setting these ground rules early addresses key concerns regarding professional liability, evidentiary integrity, and regulatory compliance, ensuring the entire investigation is conducted within a secure, legally defensible environment.
Defining the Scope of Forensic Services
A major risk in any financial investigation is scope creep, which can quickly inflate costs and dilute the focus of the inquiry. Defining a precise scope of forensic services prevents unauthorized expansions and ensures that all investigative actions remain legally defensible in court.
- Target Entities and Accounts: Explicitly listing the specific corporate subsidiaries, bank accounts, and ledgers subject to analysis.
- Temporal Boundaries: Defining the exact timeframe of the financial records under investigation (e.g., January 1, 2021, through December 31, 2023) to prevent endless historic digging.
- Investigative Methodologies: Outlining acceptable procedures, such as data mining, custodian interviews, or physical asset verification, to establish clear operational boundaries.
- Deliverable Specifications: Clarifying whether the final output will be a formal written expert report, a digital presentation, or raw data schedule findings suitable for litigation.
Establishing Fee Structures and Payment Terms
Financial clarity is essential for sustaining long-term investigative efforts. Forensic accounting engagements require transparent billing structures, including upfront retainer management and clear rules on handling additional out-of-pocket costs, to align expectations and secure necessary resources.
The table below outlines the primary billing methodologies utilized to structure these engagements, contrasting their ideal applications and financial mechanics:
| Billing Model | Description | Best Suited For |
|---|---|---|
| Hourly Rates | Fees calculated based on the actual hours logged by professional staff at tiered seniority rates. | Complex, unpredictable investigations with fluid parameters or pending litigation. |
| Flat Fee (Fixed Pricing) | A single, predetermined price for the entirety of the defined project scope. | Standardized diagnostic reviews, compliance health checks, or localized asset valuations. |
Protecting Data with Confidentiality and Non-Disclosure Clauses
Forensic audits routinely expose highly sensitive corporate secrets, proprietary algorithms, and personally identifiable information. Securing this data demands absolute confidentiality, enforced by strict non-disclosure terms that outline storage, transmission, and post-investigation destruction standards.
"The Forensic Accountant agrees to maintain the absolute confidentiality of all non-public financial records, corporate databases, and proprietary business information obtained during the course of this investigation. Under no circumstances shall such information be disclosed to third parties without prior written authorization, except as required by a valid judicial subpoena or court order."
Managing Liability and Dispute Resolution
Due to the adversarial nature of financial disputes, forensic accountants often find themselves targeted by opposing legal teams or unsatisfied clients. Structuring limitation of liability clauses and setting clear dispute pathways helps de-escalate conflicts before they result in costly court battles.
When disagreements arise regarding billing, methodology, or report findings, parties should adhere to a structured, multi-step resolution process:
- Good Faith Negotiation: Executives from both parties must meet within ten business days of written notice to attempt an informal, amicable resolution.
- Non-Binding Mediation: If negotiations fail, the dispute is referred to a mutually agreed-upon independent mediator specializing in financial services.
- Binding Arbitration: Should mediation prove unsuccessful, the conflict will be resolved through binding arbitration in accordance with commercial arbitration rules, bypassing public court litigation.
Executing Safe Termination and Exit Protocols
Whether an investigation concludes naturally or is cut short by a change in corporate strategy, a structured exit protocol is required to protect both parties. Clear guidelines dictate how work-in-progress is handled, how final financial settlements are processed, and how sensitive evidence is returned or destroyed.
Either party may terminate the engagement by providing a written notice of at least 30 days. Upon receipt of such notice, the forensic team will immediately halt all non-essential analytical work. The client remains responsible for settling all outstanding balances and work-in-progress fees incurred prior to the termination date. All physical evidence and proprietary data must be securely returned to the client, or destroyed with a verified certificate of destruction issued, within 14 business days following final invoice clearance.
Best Practices for Implementing Template Agreements
Standardized templates provide an excellent operational baseline, but they must never be treated as static documents. Legal and financial leadership must continuously review and tailor these agreements to match changing state laws, new federal accounting regulations, and the unique risk profiles of individual clients.
Regular maintenance ensures that your legal frameworks remain highly resilient, protecting your firm's revenue and reputation across all forensic engagements.
Leave a comment