For accounting and finance professionals, the month-end close often brings the stressful discovery of unresolved balance discrepancies, where even a minor decimal mismatch can stall reporting cycles for days. Before rushing to force adjustment entries, it is critical to recognize how today's fragmented, multi-channel payment streams complicate modern bookkeeping. Establishing a standardized reconciliation framework grants organizations absolute balance sheet integrity and immediate audit-readiness.
However, templates alone cannot replace sound financial hygiene; their success relies on consistent transaction-matching workflows. Whether you are untangling complex bank-to-ledger mismatches or reconciling aged accrued liabilities, structured documentation serves as your primary line of defense against material misstatements.
In this article, we provide essential, customizable general ledger reconciliation templates and demonstrate how to strategically implement them to streamline your close process and permanently eliminate variance errors.
Monthly General Ledger Reconciliation Sheet
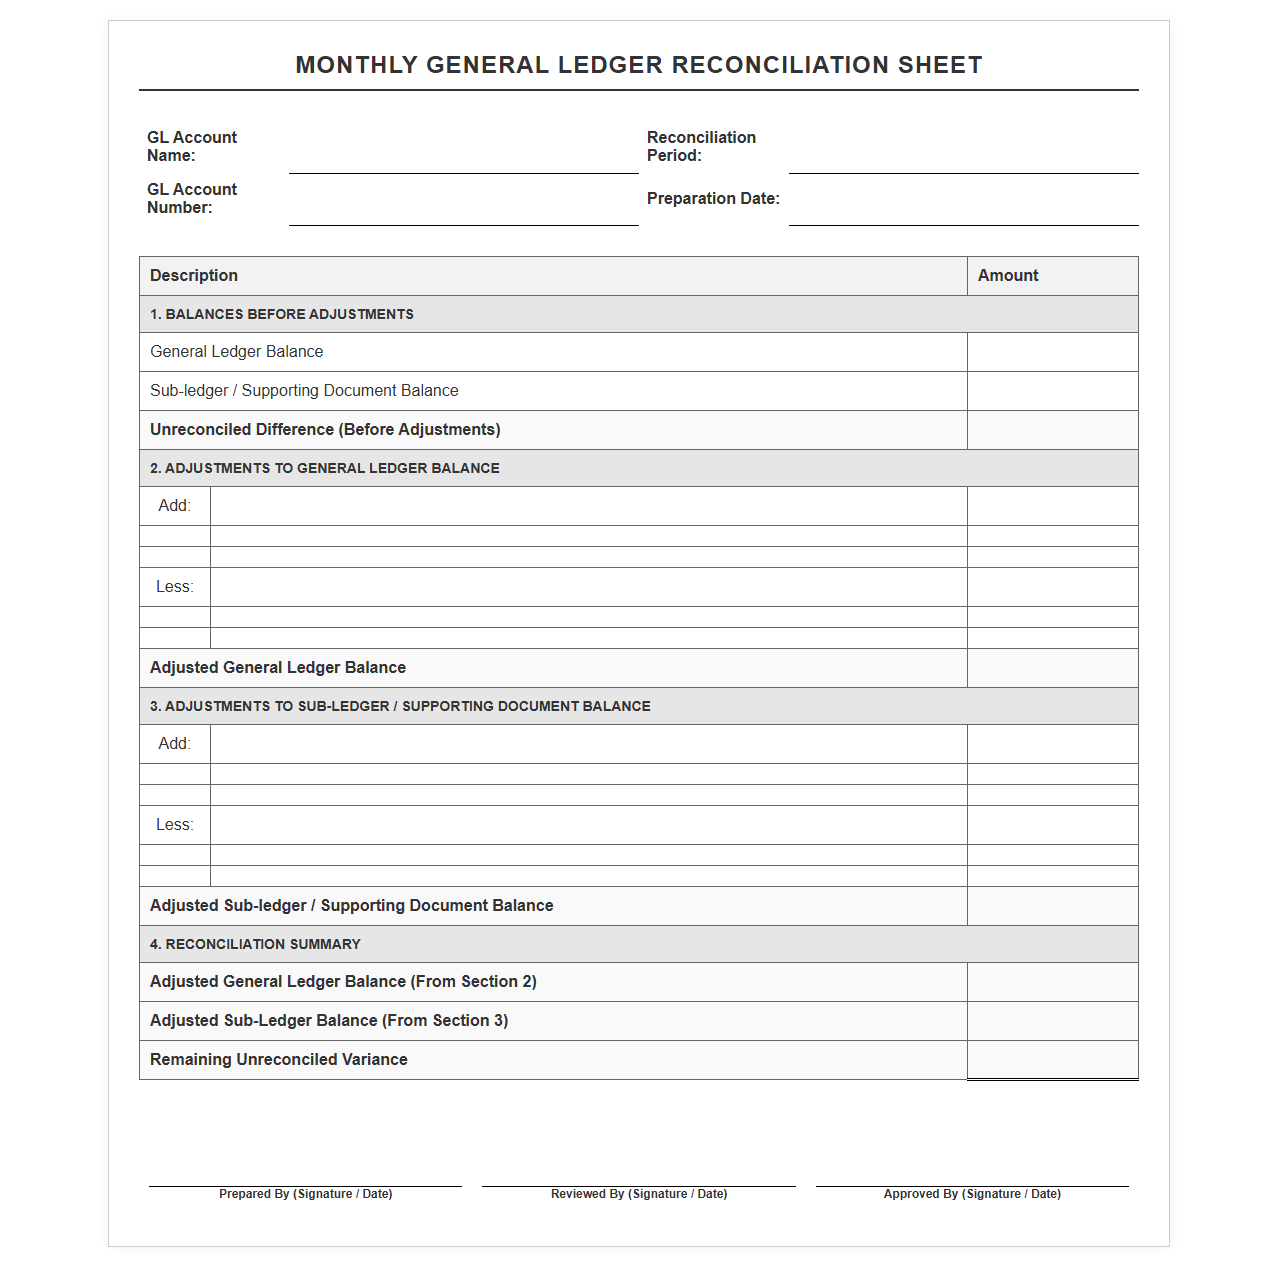 Download: .PDF
Automated General Ledger Reconciliation Template
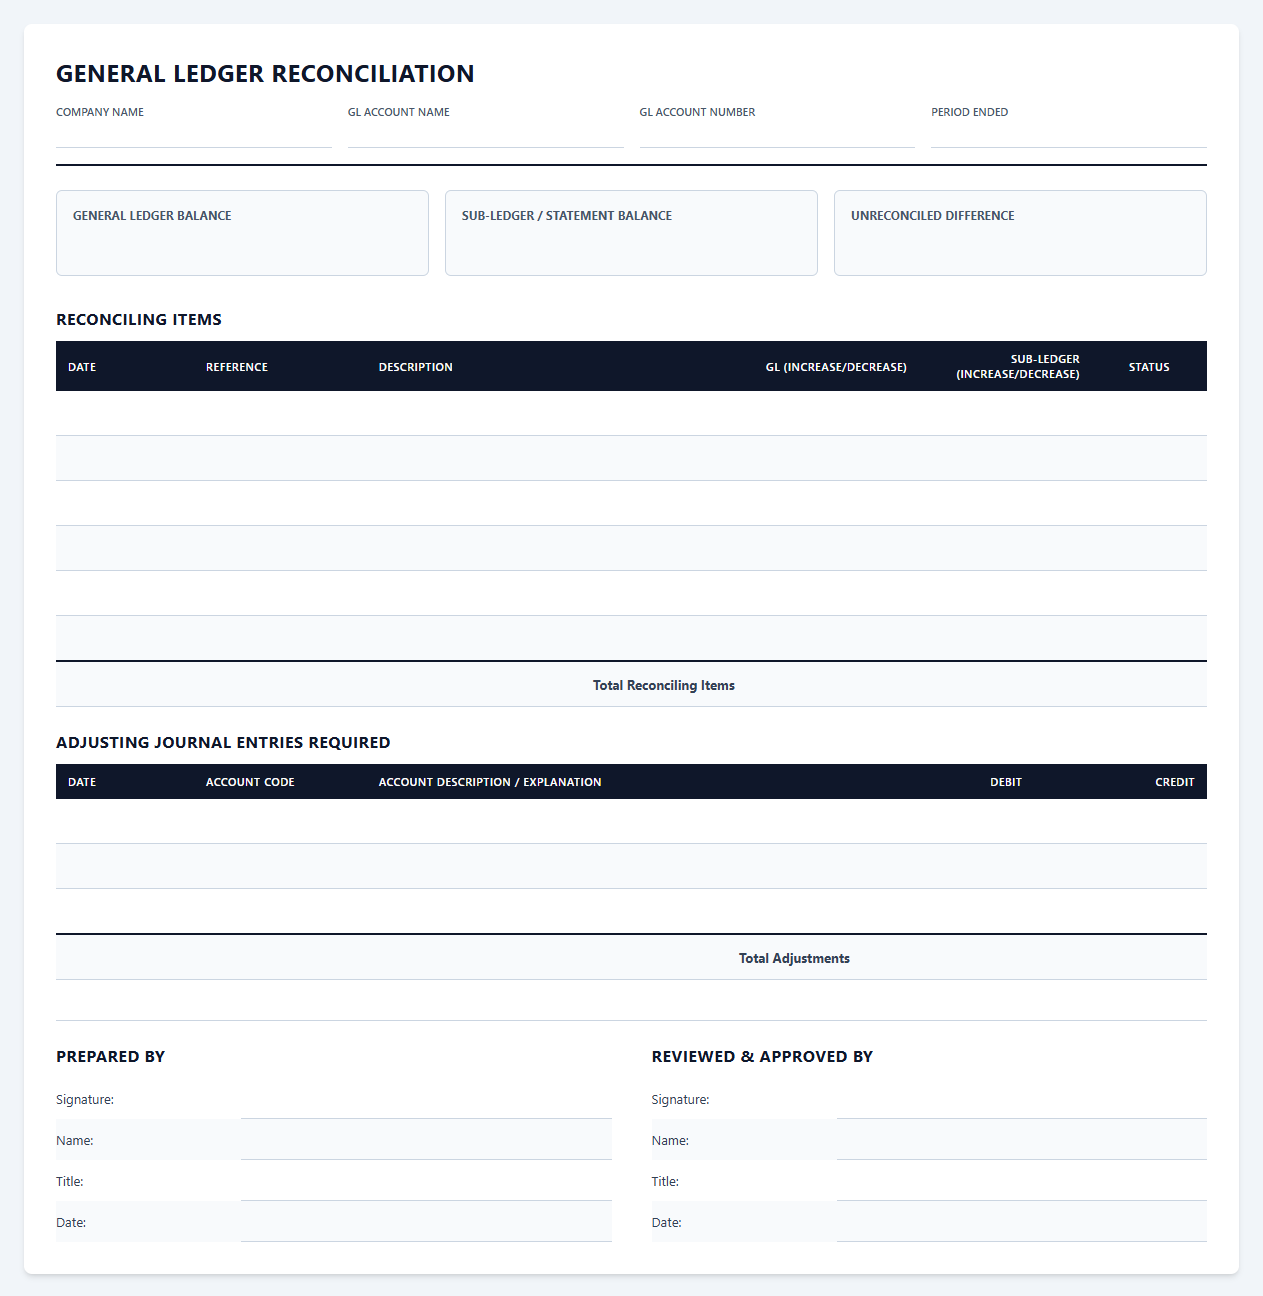 Download: .PDF
General Ledger Account Reconciliation Worksheet
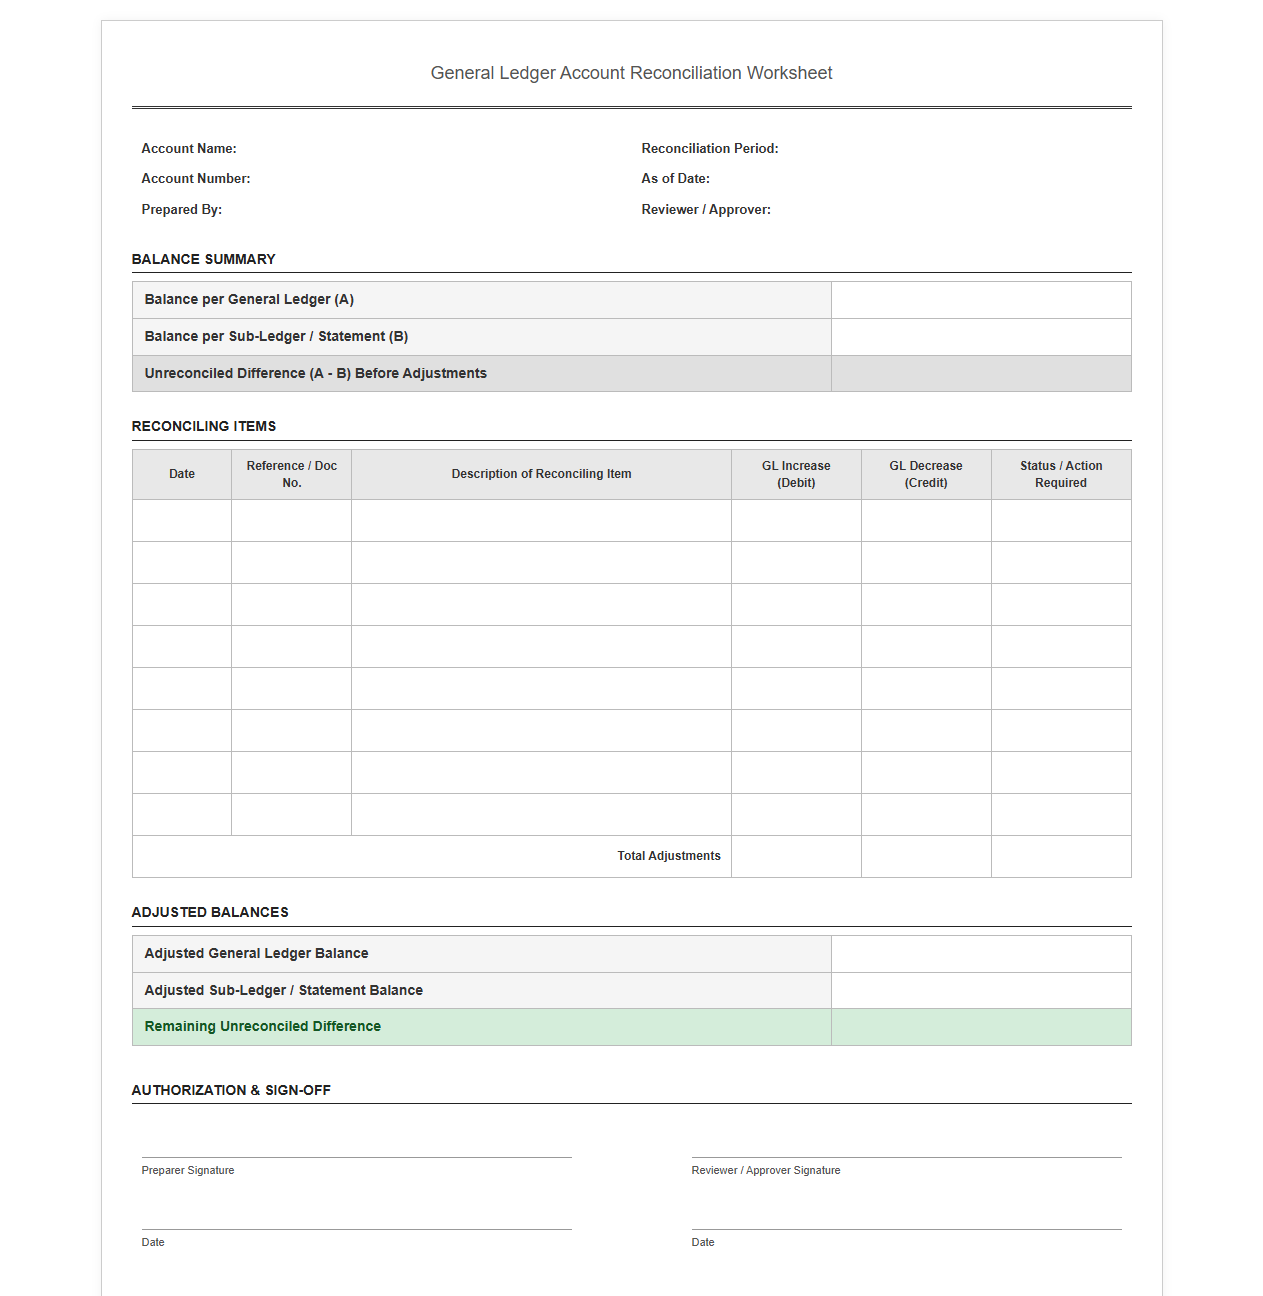 Download: .PDF
Double-Entry General Ledger Balance Sheet Template
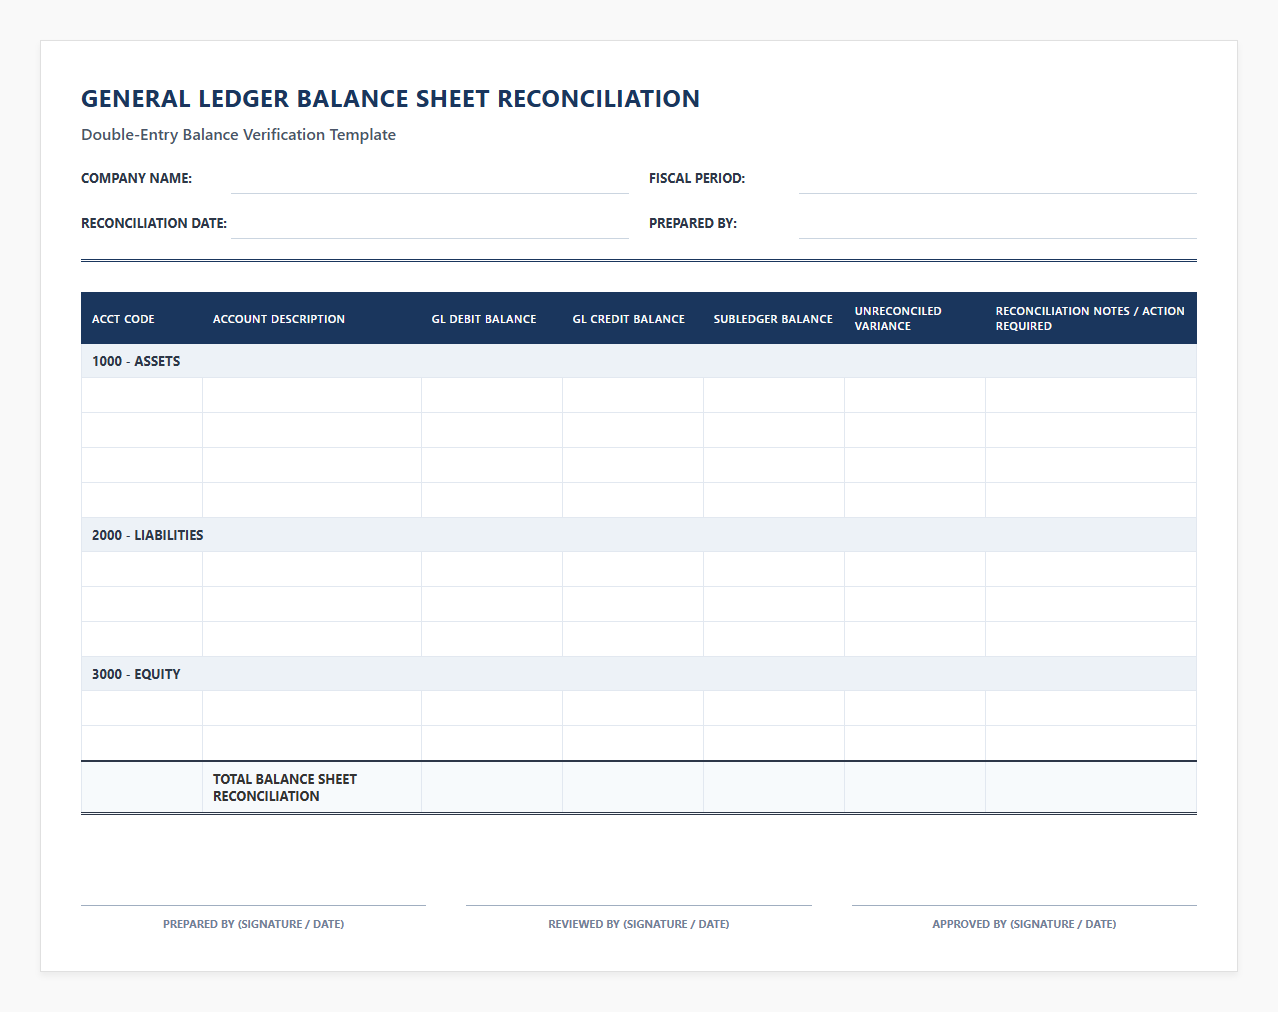 Download: .PDF
Year-End General Ledger Reconciliation Ledger
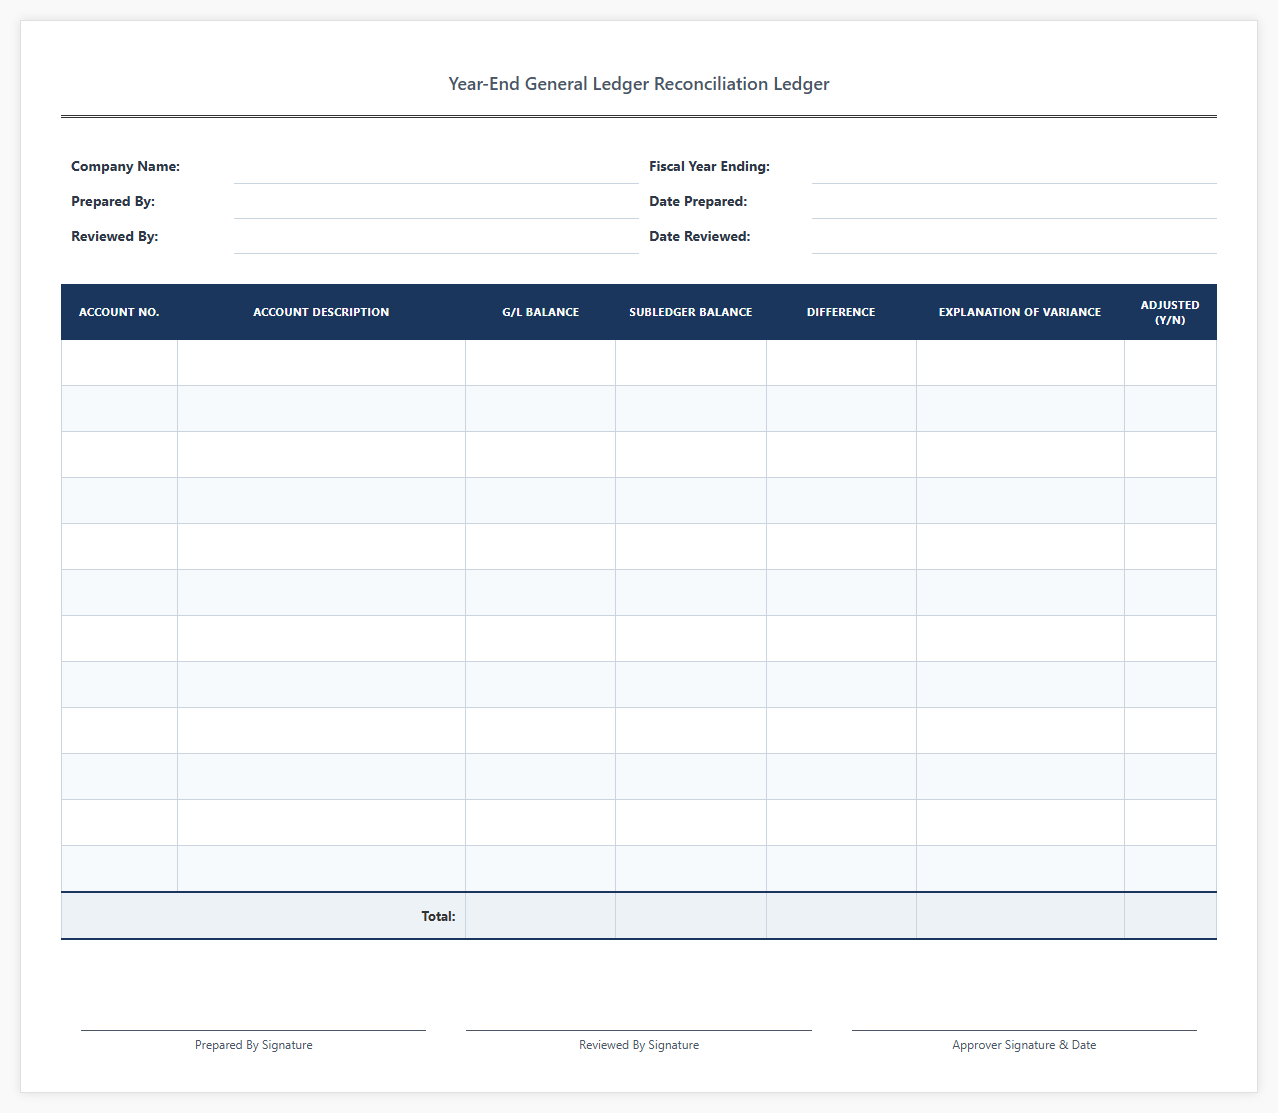 Download: .PDF
Multi-Currency General Ledger Reconciliation Template
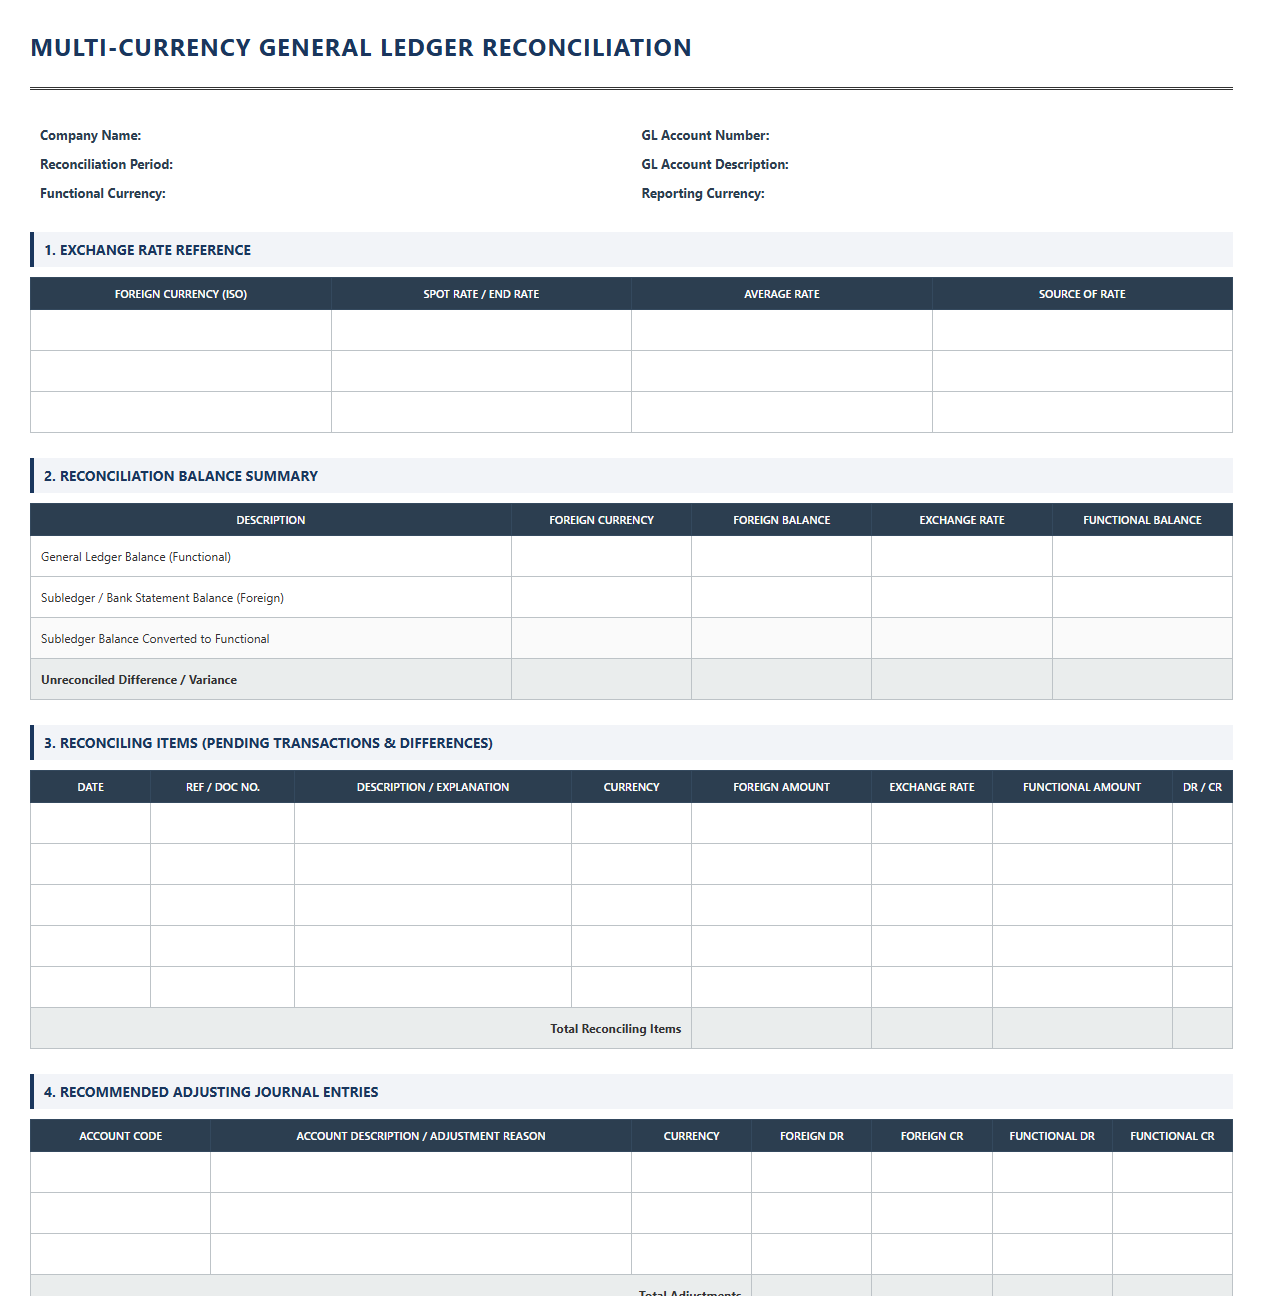 Download: .PDF
Weekly General Ledger Reconciliation Log
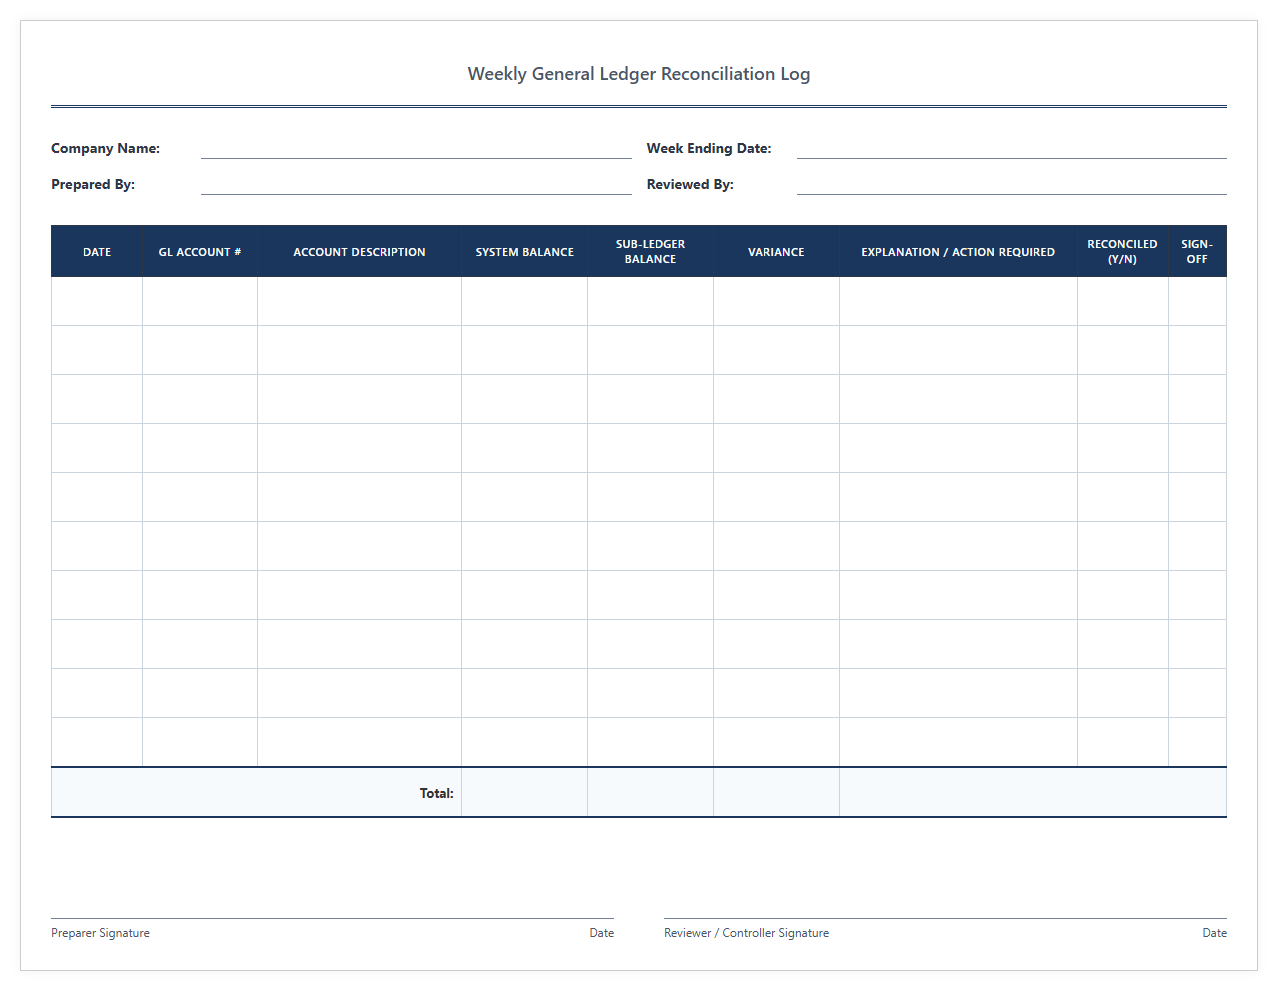 Download: .PDF
General Ledger Reconciliation Statement Template
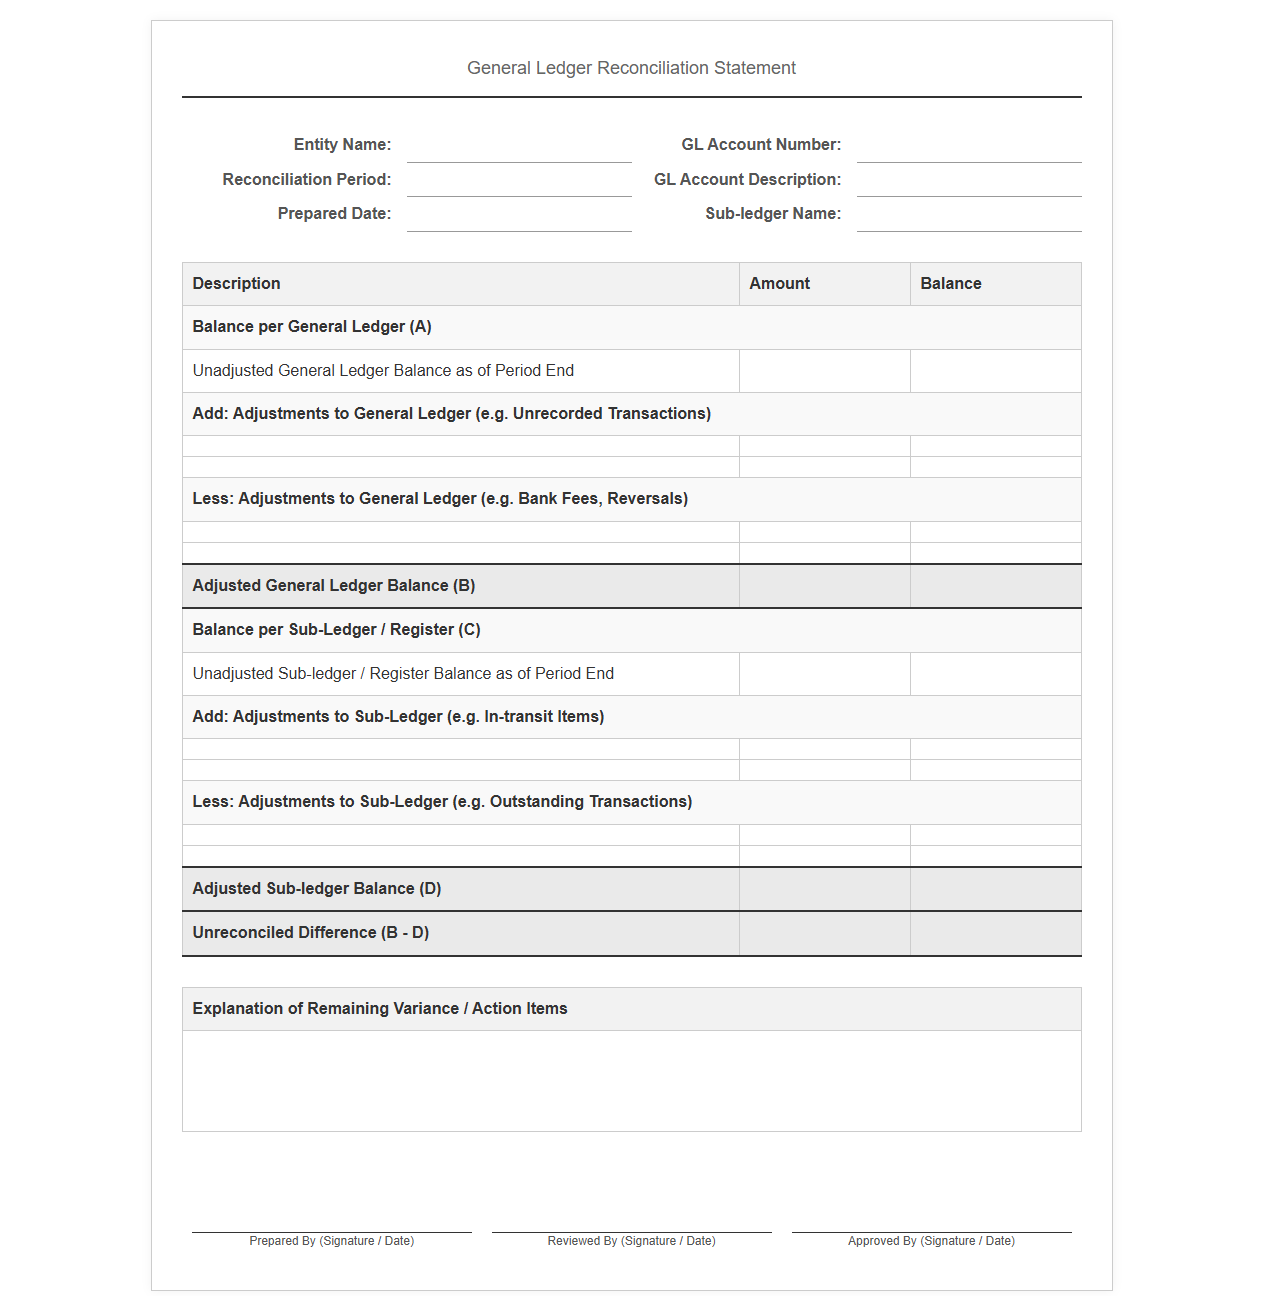 Download: .PDF
Standard General Ledger Reconciliation Audit Sheet
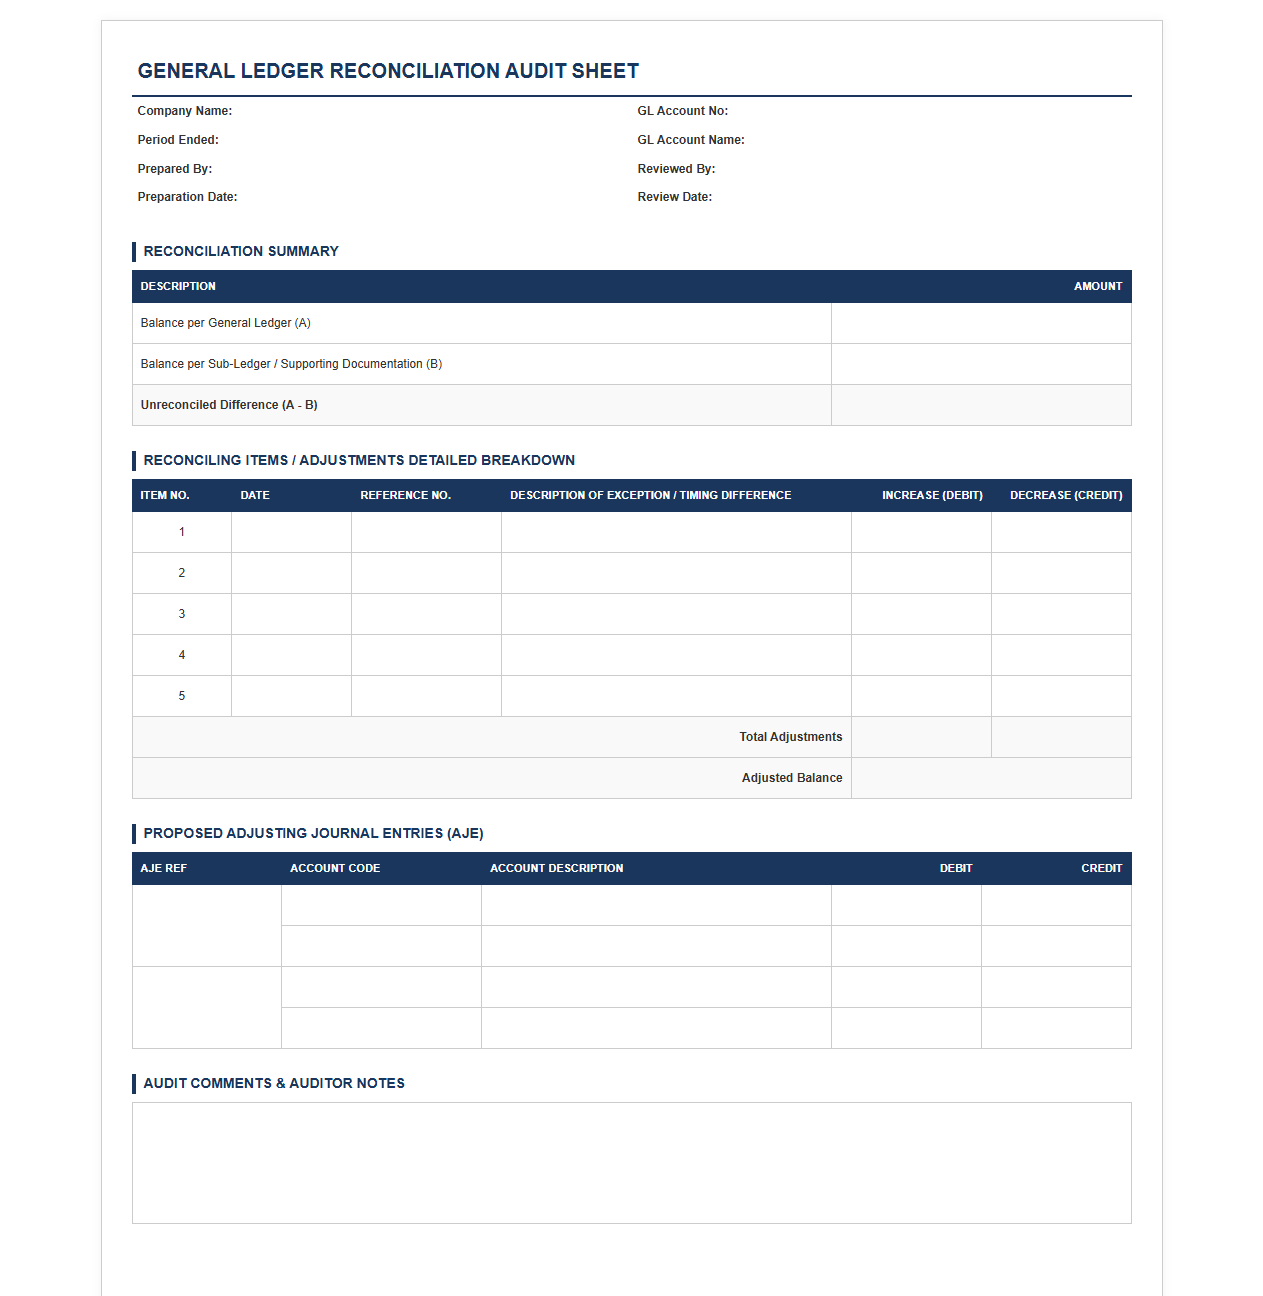 Download: .PDF
Daily General Ledger Reconciliation Tracker
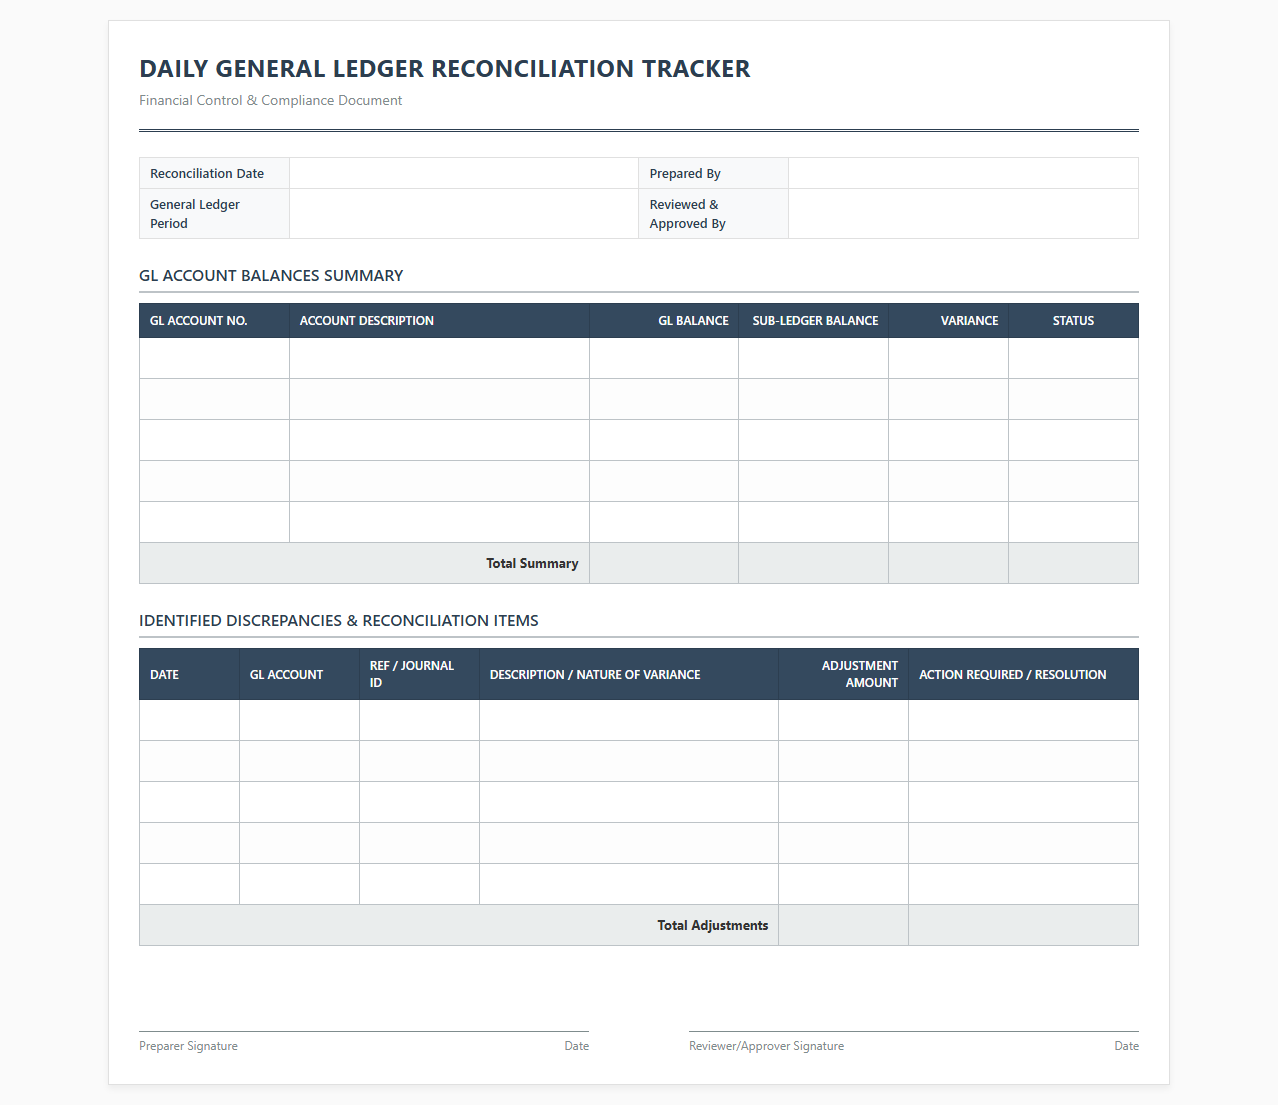 Download: .PDF
Introduction to General Ledger Reconciliation
General ledger reconciliation is the cornerstone of corporate financial integrity. This systematic process compares the general ledger against independent sources, such as bank statements, sub-ledgers, and physical inventory counts, to verify that every financial transaction is recorded accurately. Maintaining a rigorous reconciliation schedule is critical for ensuring compliance with accounting frameworks like GAAP and IFRS, safeguarding organizational assets, and preventing devastating financial errors that can distort a company's financial health.
Without structured reconciliation protocols, minor clerical errors can snowball into major reporting discrepancies. Organizations that prioritize this process can proactively identify discrepancies, secure stakeholder trust, and establish a strong foundation for strategic decision-making based on flawless financial data.
Common Causes of Ledger Balance Discrepancies
Ledger discrepancies can stem from various operational and manual errors. Recognizing the root causes of these imbalances is essential for swift remediation. Typical drivers of balance discrepancies include:
- Timing differences, which occur when transactions are recorded in one sub-ledger but have not yet cleared the corresponding system.
- Transposition errors, resulting from manually swapping adjacent digits, such as writing 89 instead of 98.
- Double-postings, which involve recording the exact same journal entry or invoice twice, artificially inflating balances.
- Unauthorized transactions, which represent fraudulent activity or unapproved expenditures that bypass standard purchase control workflows.
Core Components of a Standard Reconciliation Template
A standardized general ledger reconciliation template provides the structure necessary to document balances, adjustments, and explanations clearly. This ensures consistency across different departments and entities.
| Field Category | Field Name | Description |
|---|---|---|
| Account Metadata | Account Number & Name | Unique identifiers for the general ledger account under review. |
| Uncleared Transactions | Outstanding Deposits / Checks | Transactions that have been initiated but not yet finalized by external parties. |
| Variance Calculations | Unreconciled Difference | The mathematically computed difference between the ledger balance and the adjusted source balance. |
Step-by-Step Investigation Workflow for Variances
When a variance is discovered between a sub-ledger and the general ledger, accounting teams must follow a systematic investigation process to identify the source of the deviation:
- Verify the mathematical accuracy of the ledger balances and confirm that the correct date ranges were applied to the reports.
- Compare individual transaction line items in the sub-ledger against the corresponding general ledger entries to isolate unmatched amounts.
- Search specifically for transposition errors and duplicate amounts that match the exact value of the variance.
- Consult operational teams to confirm if timing issues, such as goods in transit, are delaying system updates.
- Formulate the required adjustment to correct the verified error and submit it for supervisory approval.
Standardizing the Discrepancy Log and Resolution Template
To prevent outstanding variances from falling through the cracks, organizations should maintain a centralized discrepancy log. This register tracks active investigations and ensures clear ownership of unresolved items.
Effective discrepancy tracking requires capturing the date of discovery, the total outstanding amount, and precise aging categories (e.g., 30, 60, or 90+ days) to flag high-risk legacy items.
Each entry in the log must be assigned to a specific team member who is responsible for executing the corrective action and documenting the resolution path within the template. Clear ownership eliminates ambiguity and speeds up the reconciliation cycle.
Documenting Adjusting Journal Entries and Approvals
When a variance is confirmed, correcting the ledger requires a formal adjusting journal entry. Best practices mandate that no adjustments are made without comprehensive documentation and strict adherence to internal controls.
For every adjustment, the accountant must create a clear description, such as Debit: 10100 Cash / Credit: 12100 Accounts Receivable, to reflect the correction accurately. This entry must be backed by verifiable supporting evidence, including bank notices, invoices, or system logs.
To preserve a secure audit trail, the adjusting entry must receive a formal sign-off from authorized management before posting, ensuring that segregation of duties is maintained at all times.
Best Practices for Maintaining Audit-Ready Ledgers
Establishing an audit-ready general ledger requires moving away from reactive end-of-month rushes and toward a culture of continuous monitoring. Implementing modern financial automation software can drastically reduce human error by automatically matching high-volume transactions, leaving accountants free to investigate complex variances.
To secure long-term financial accuracy, organizations must design robust internal controls that mandate daily or weekly reconciliation cycles for high-risk accounts. Consistent oversight ensures that records remain clean, compliant, and prepared for external audit scrutiny at any given moment.
Leave a comment