For corporate controllers and inventory managers, accounting for stock devaluation is a persistent source of operational friction, frequently marred by subjective estimates and inconsistent ledger entries. Before addressing template design, organizations must first establish a firm grounding in standard GAAP and IFRS impairment frameworks.
Transitioning to specialized ledger templates grants accounting teams immediate audit-readiness while reducing manual reconciliation cycles. However, as a crucial stipulation, these templates must be treated as structural compliance frameworks rather than substitutes for active market valuation. For instance, when applying the Lower of Cost or Market (LCM) rule to slow-moving consumer electronics, the template standardizes the calculations, but local managers must still input verified net realizable values.
This article outlines the essential architecture of specialized devaluation ledgers, provides step-by-step deployment strategies, and explores automated workflows designed to streamline your next audit cycle.
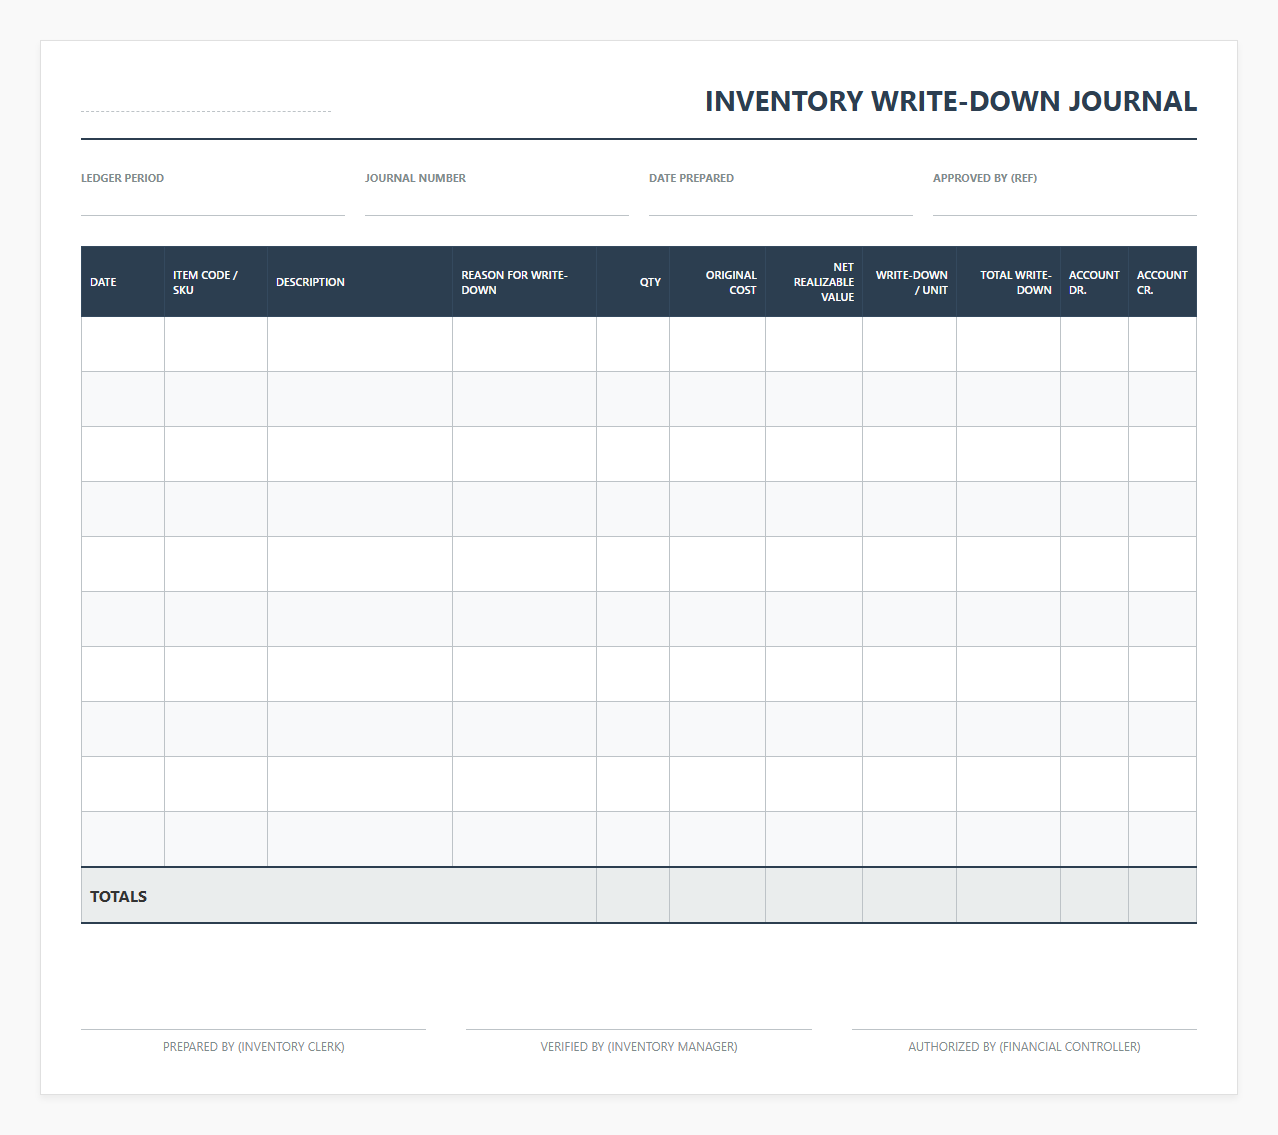
Inventory Write-Down Journal Ledger
 Download: .PDF
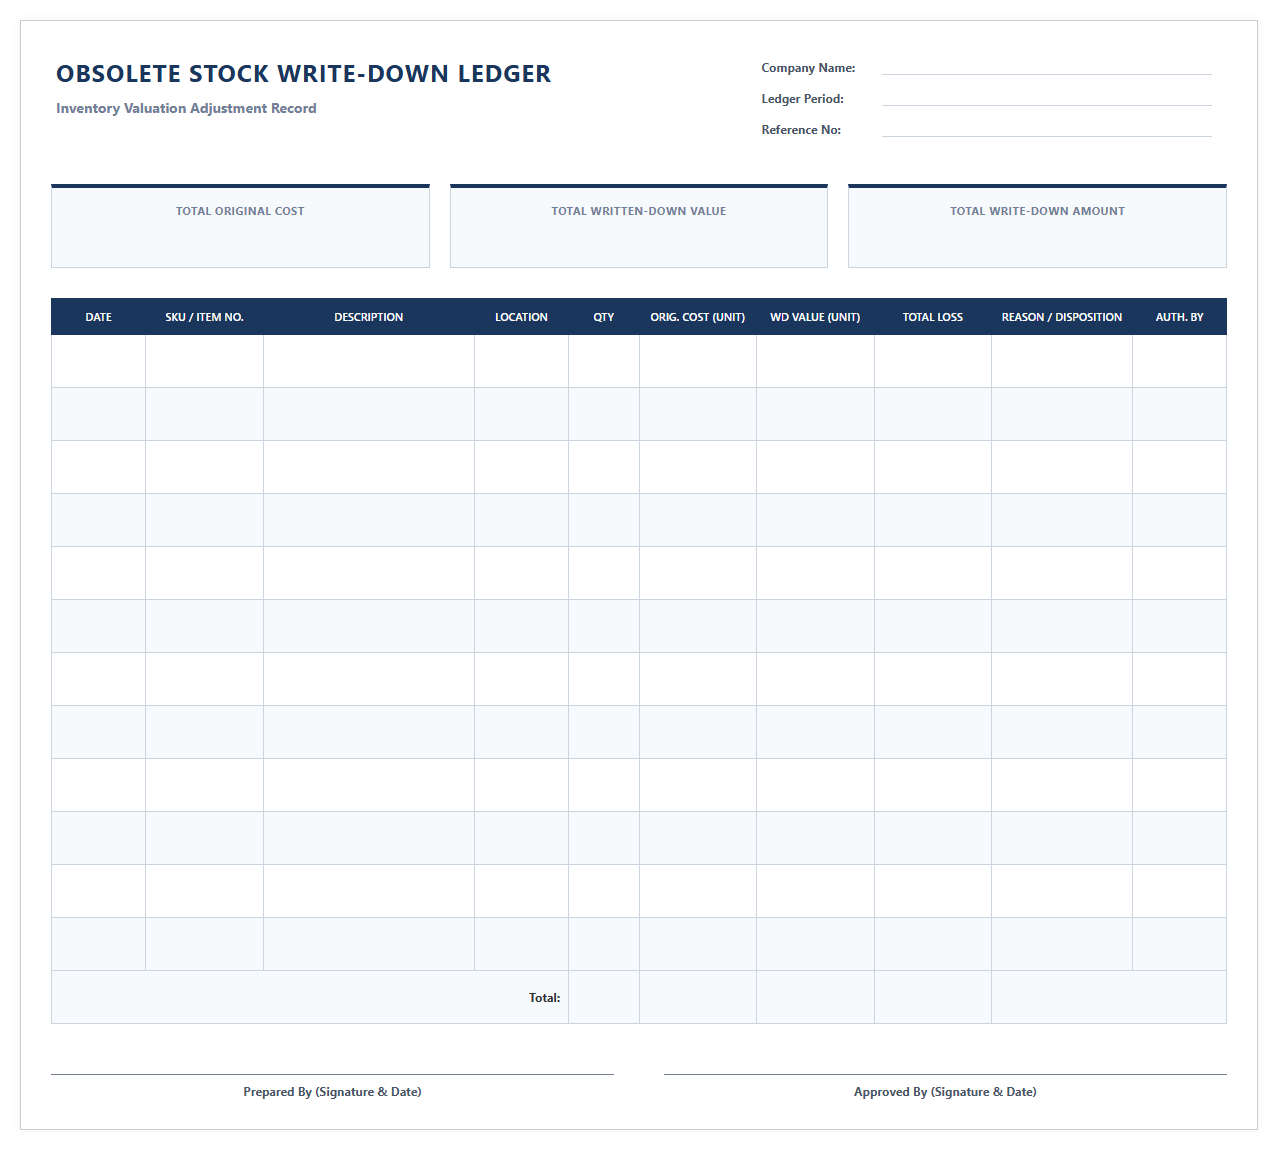
Obsolete Stock Write-Down Ledger Sheet
 Download: .PDF
Damaged Goods Write-Down Ledger Template
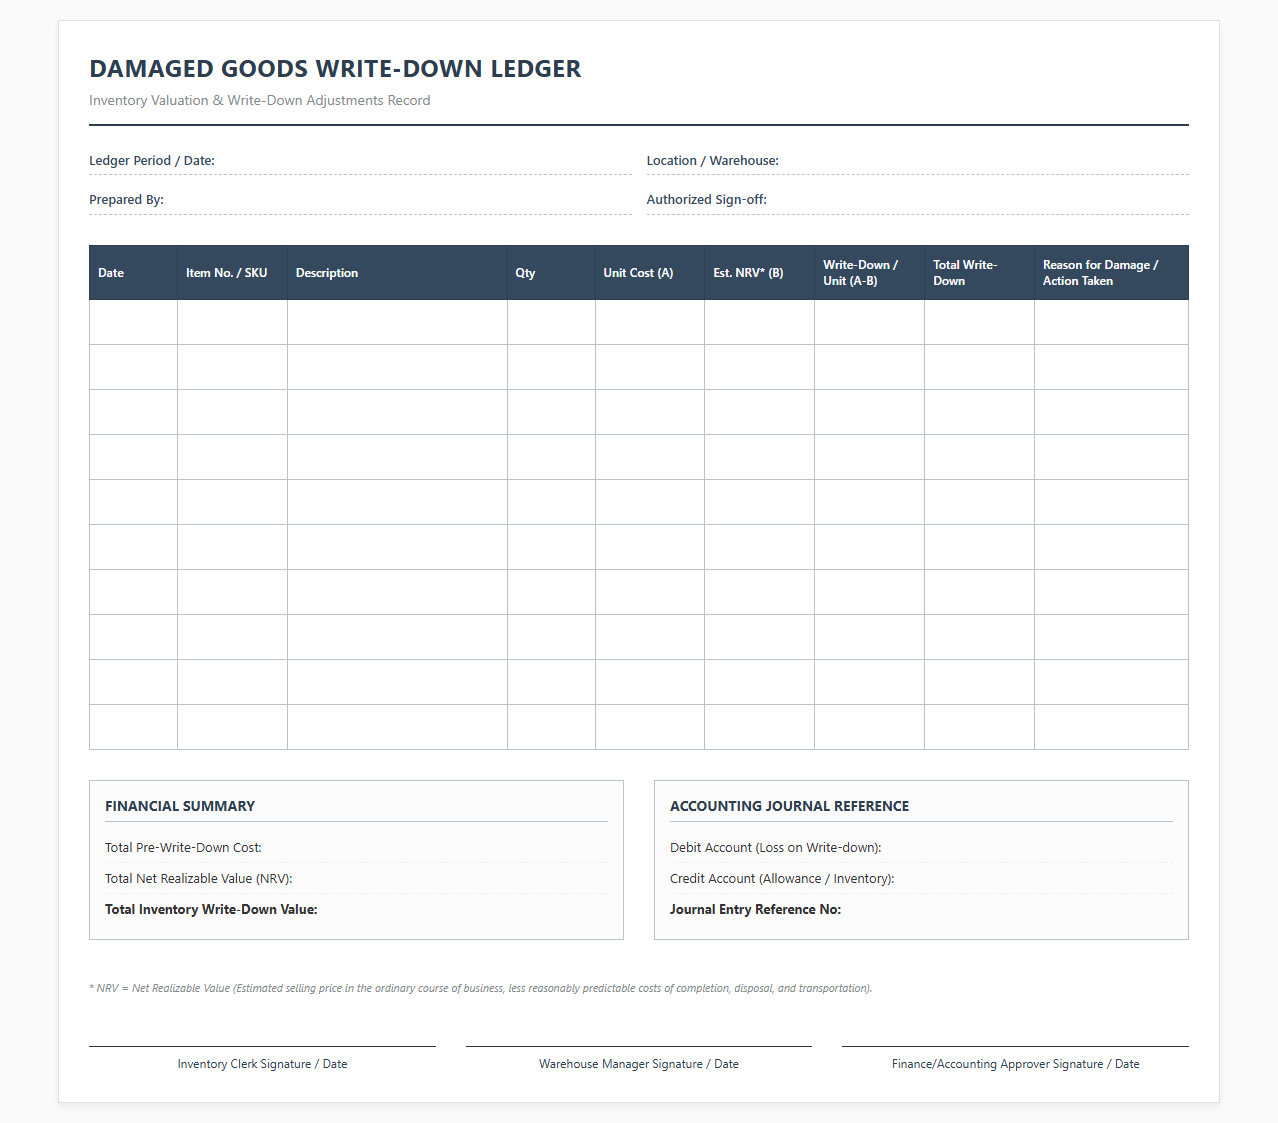 Download: .PDF
Inventory Devaluation and Write-Down Register
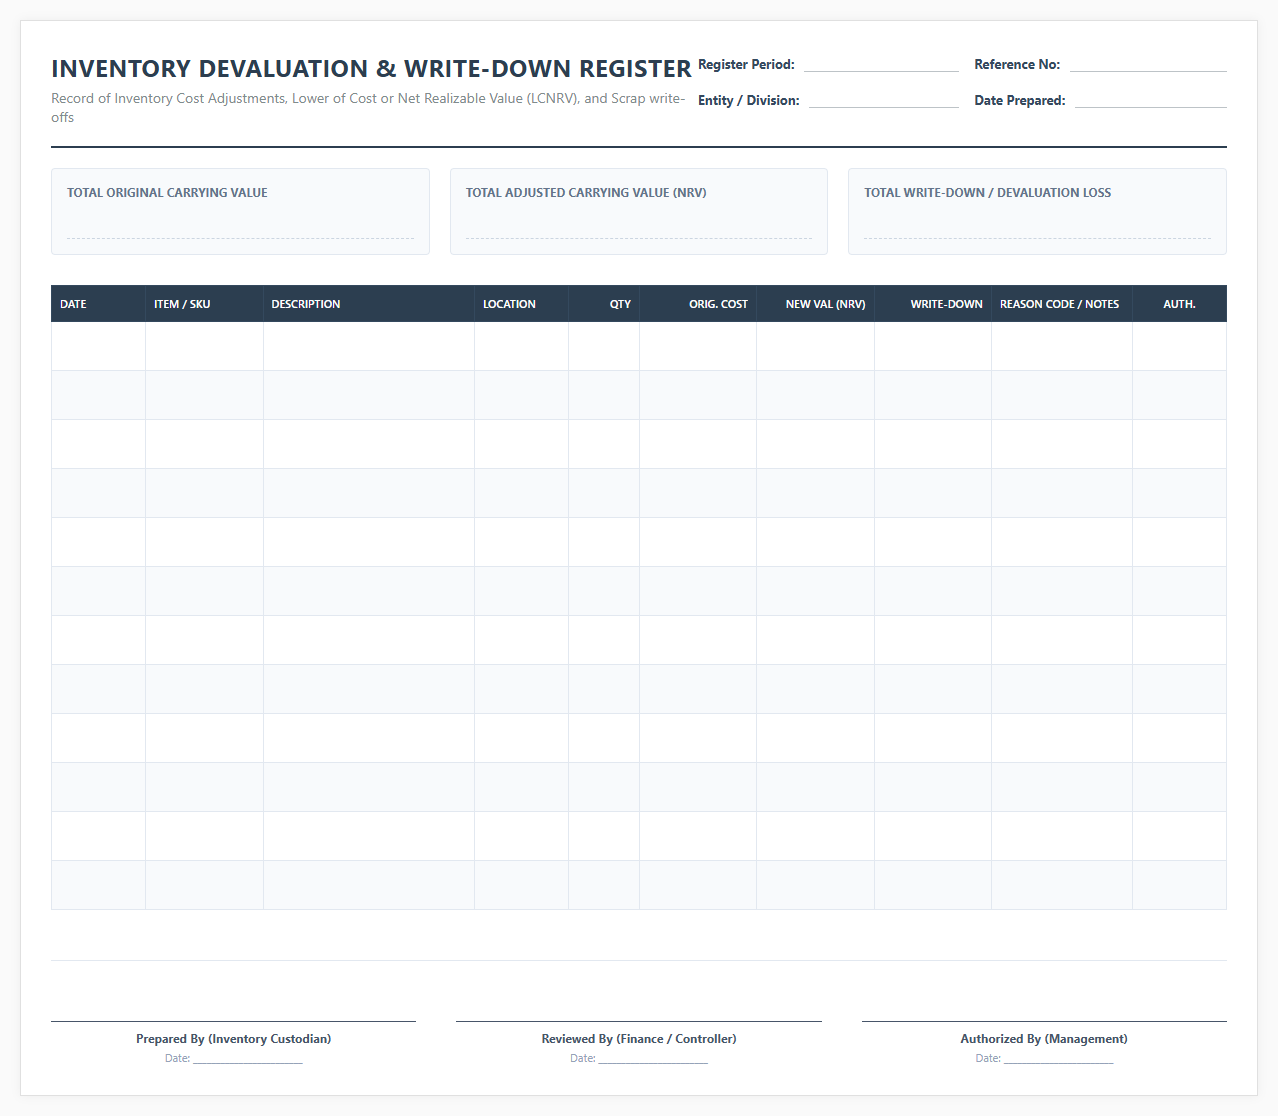 Download: .PDF
Lower of Cost or Market Inventory Ledger
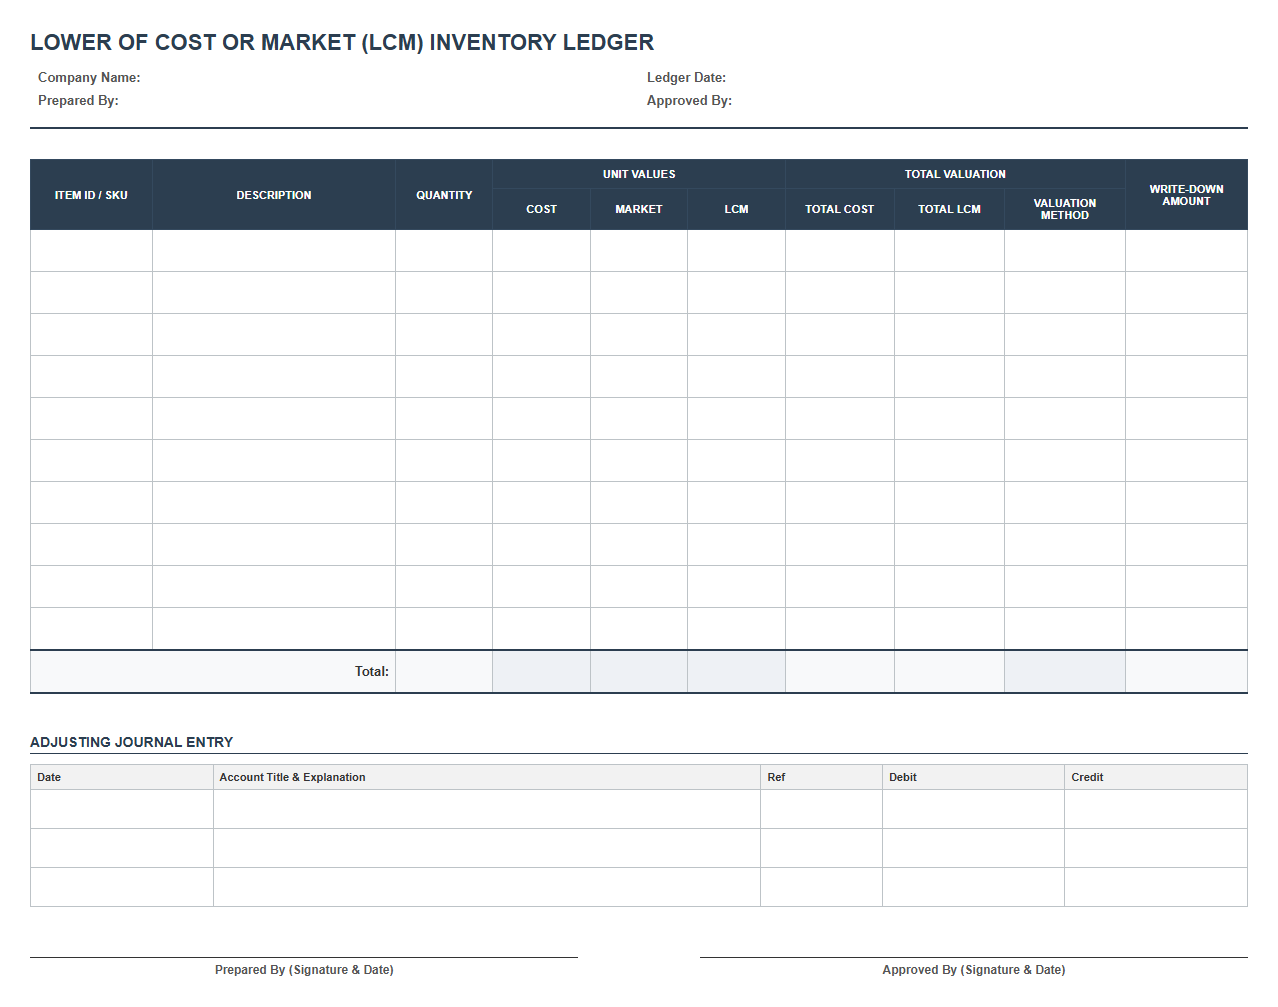 Download: .PDF
Monthly Inventory Impairment Write-Down Log
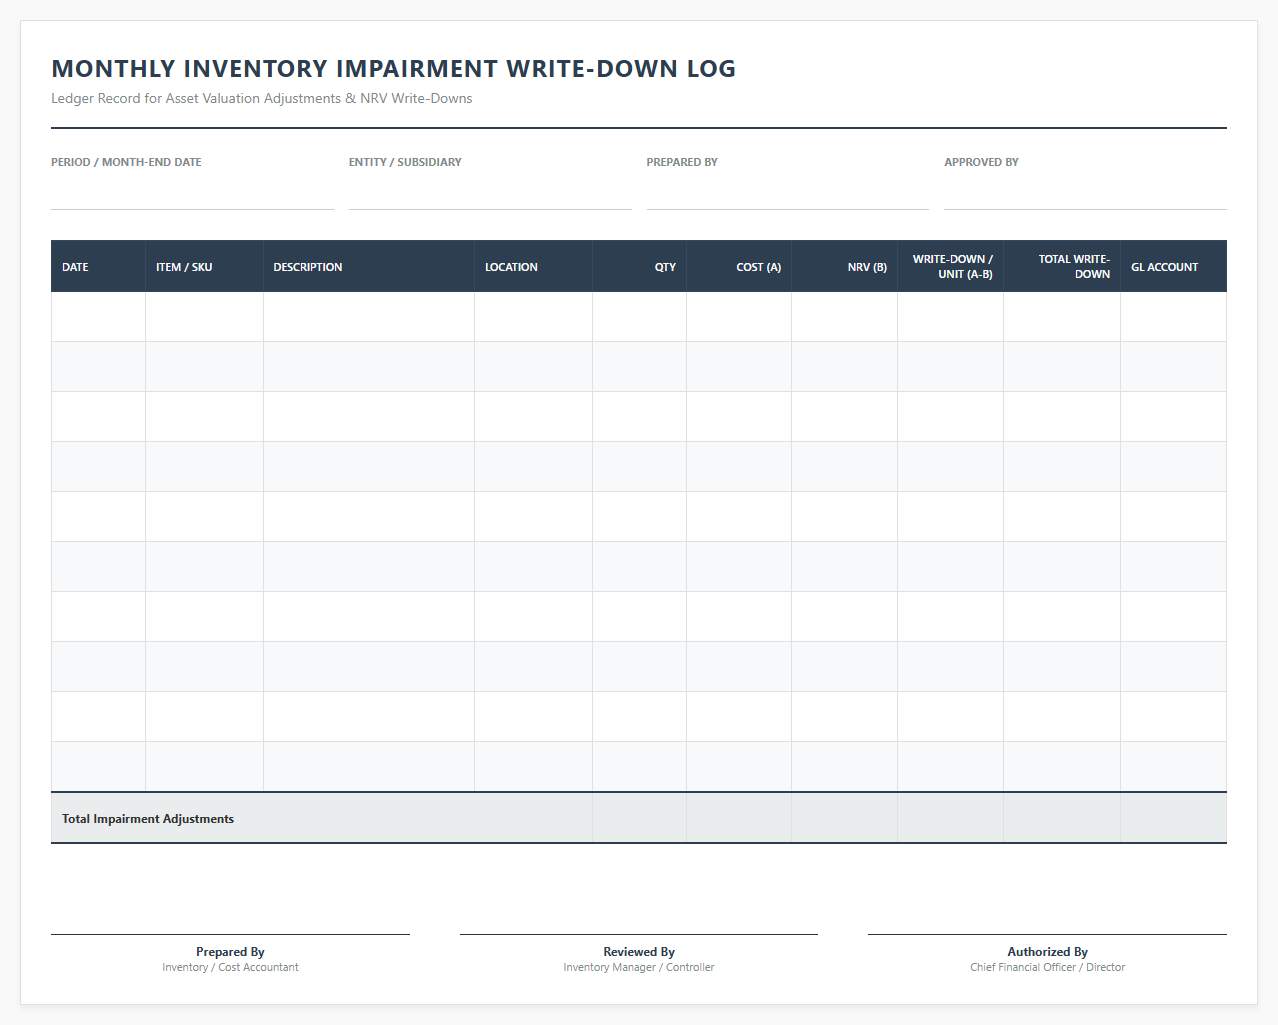 Download: .PDF
Year-End Inventory Write-Down Ledger Book
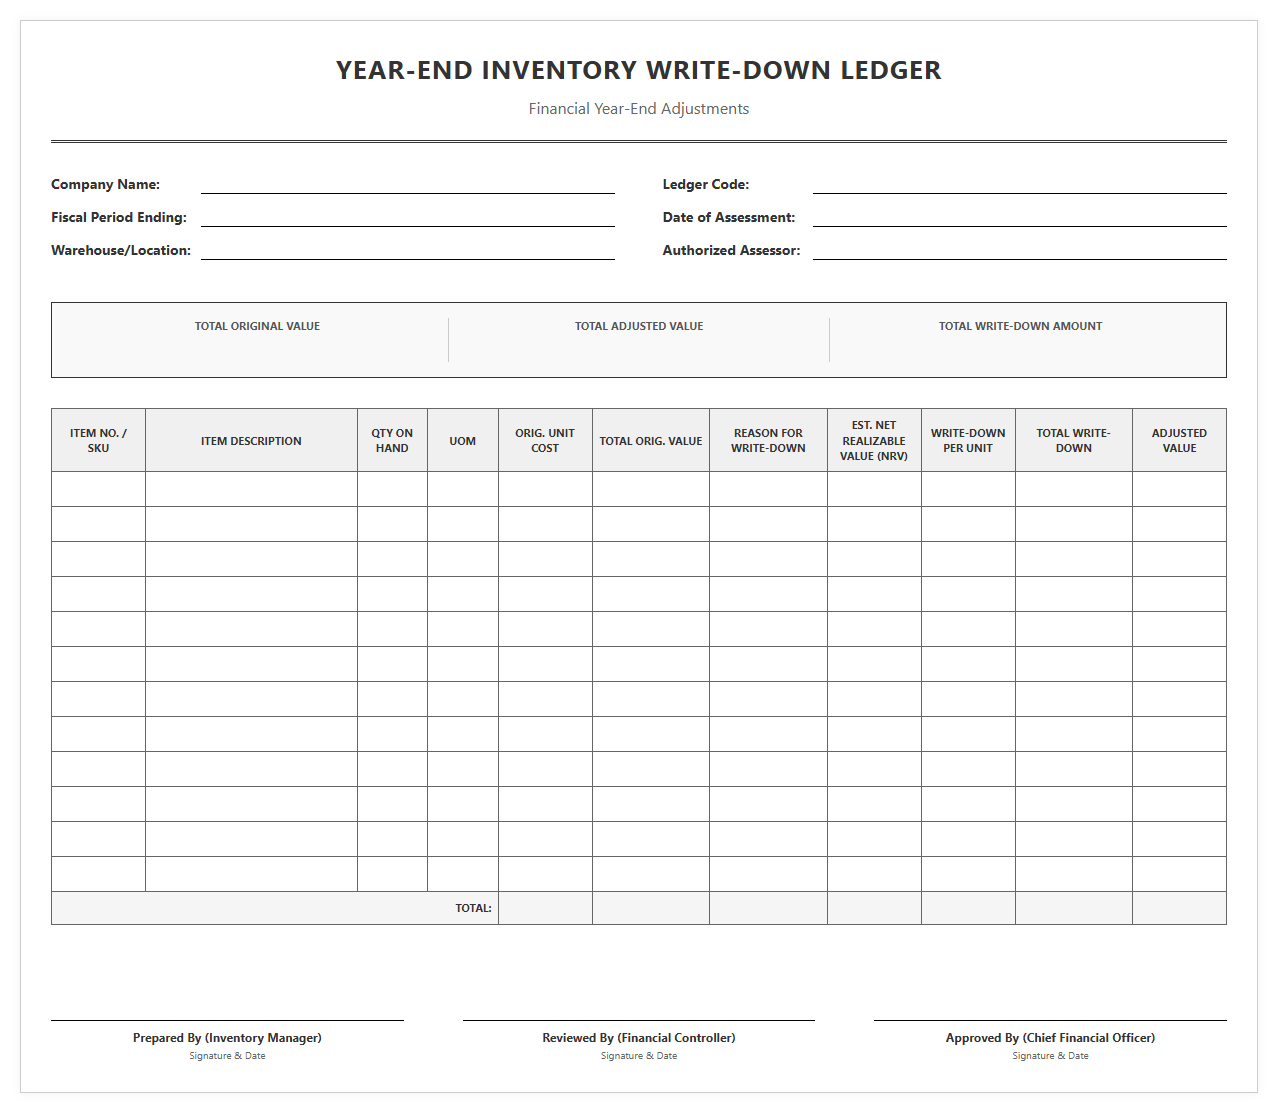 Download: .PDF
Excess and Obsolete Inventory Write-Down Ledger
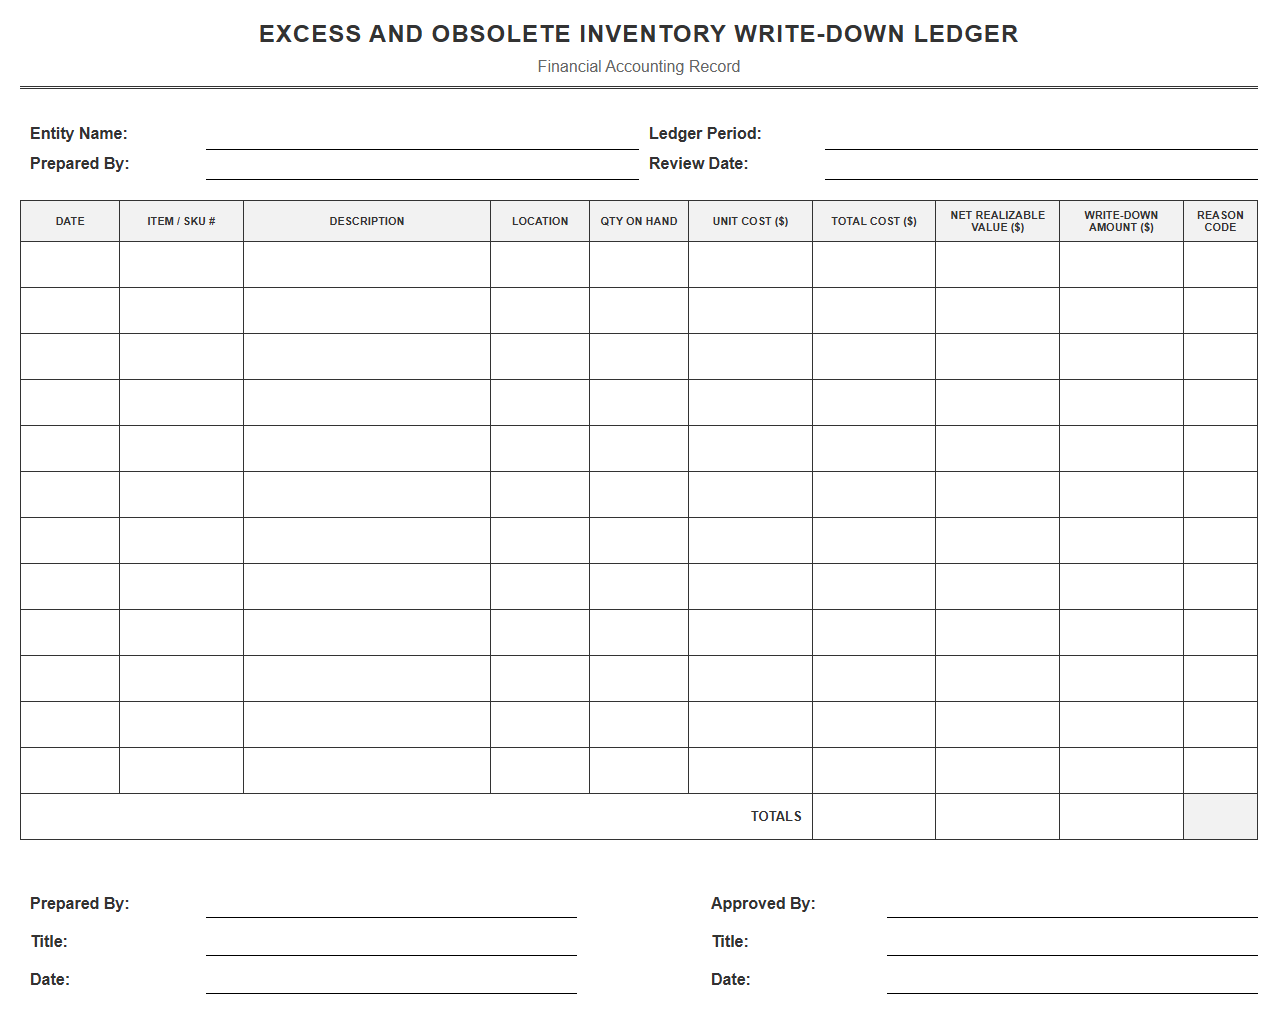 Download: .PDF
Retail Stock Devaluation Ledger Template
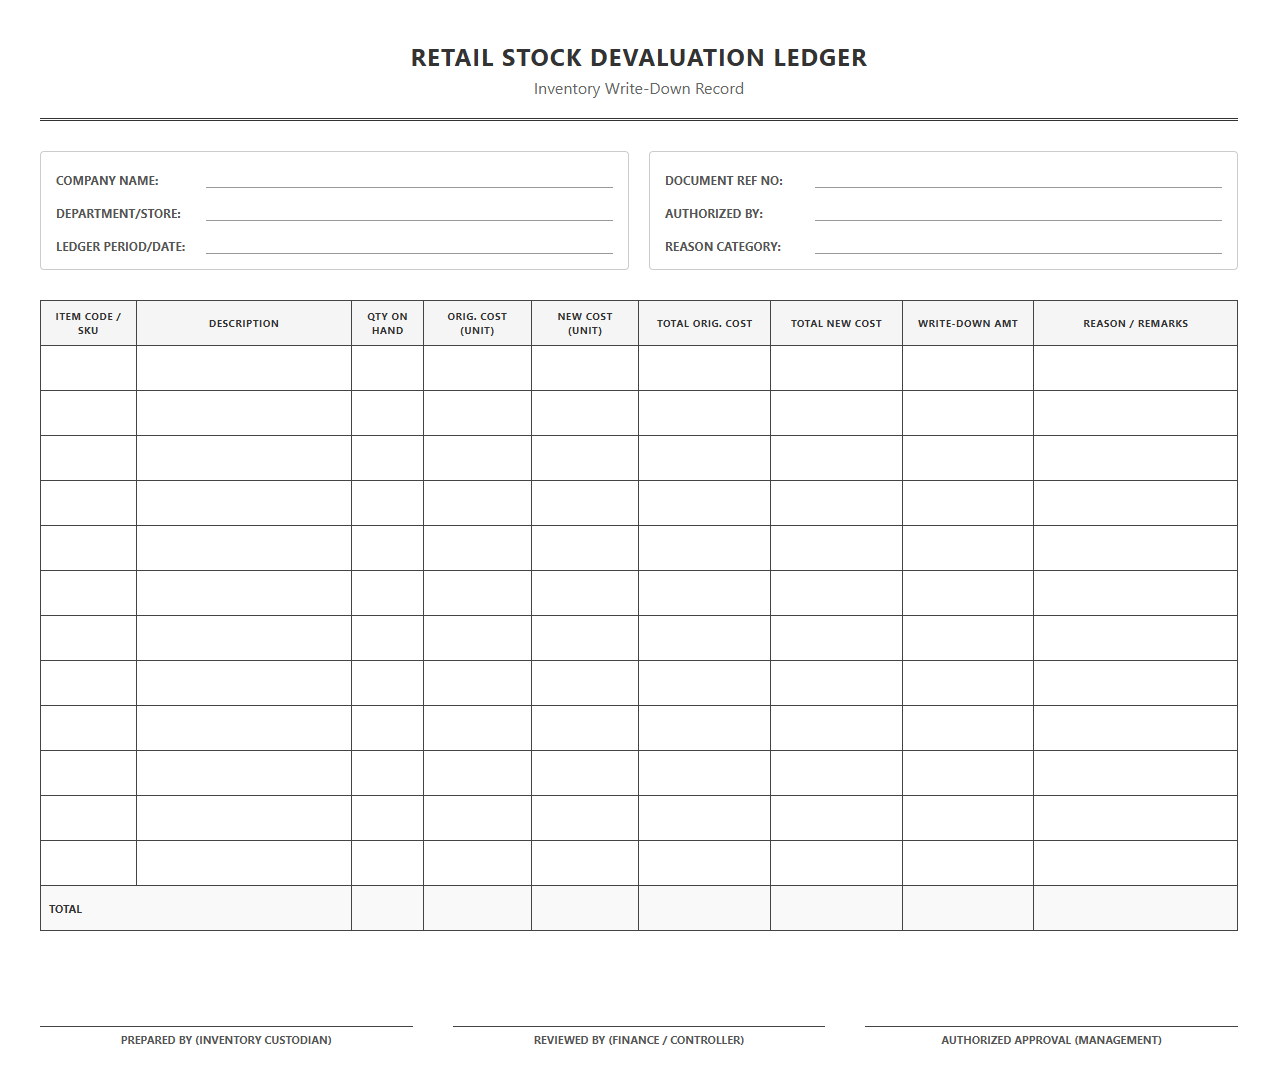 Download: .PDF
The Imperative of Standardizing Inventory Devaluation
In the modern financial landscape, maintaining an accurate balance sheet is critical for operational viability and investor trust. When inventory loses value due to damage, obsolescence, or shifting market demand, businesses must adjust their asset valuations immediately. Without a standardized approach to stock devaluation, organizations risk introducing severe financial discrepancies into their reporting. Specialized ledger templates serve as a defense against these inconsistencies, establishing a uniform, repeatable process that ensures every write-down is recorded with absolute precision.
Regulatory Frameworks and the LCM Rule
Understanding GAAP and IFRS Mandates
Financial authorities require businesses to adhere to strict accounting standards when reporting inventory assets. Under US GAAP, companies must apply the Lower of Cost or Market (LCM) rule. This standard dictates that inventory must be recorded at whichever value is lower: its original cost or its current market replacement rate.
Applying Net Realizable Value (NRV)
For businesses operating under IFRS, and in certain GAAP scenarios, the emphasis shifts to Net Realizable Value (NRV). NRV represents the estimated selling price in the ordinary course of business, minus reasonably predictable costs of completion, disposal, and transportation. When the NRV falls below the historical cost, an immediate write-down is mandatory to prevent asset overstatement.
Core Components of a Specialized Devaluation Ledger
To withstand rigorous auditing processes, a devaluation ledger must capture highly granular data. Standardizing these fields ensures consistency across departments and fiscal periods. Every compliant template should include specific key columns to document the lifecycle of devalued assets:
- SKU/Item Identifier: The unique code linking the entry to the physical inventory.
- Original Cost Basis: The initial purchase price or production cost of the inventory.
- Current Market Value/NRV: The calculated lower value based on market assessments.
- Devaluation Reason Code: Standardized markers such as damage, obsolescence, or spoilage.
- Write-Down Amount: The total financial adjustment calculated per unit and in aggregate.
- Authorization Signature: Digital or physical sign-off from the responsible financial officer.
Step-by-Step Workflow for Stock Write-Down Execution
Executing an inventory write-down requires a systematic operational workflow to ensure that physical reality matches financial reporting. Following a structured sequence minimizes the risk of unauthorized adjustments.
- Identify slow-moving, damaged, or obsolete inventory through regular physical counts and warehouse audits.
- Determine the current market value or Net Realizable Value for the flagged items.
- Apply the chosen accounting standard (LCM or NRV) to calculate the exact reduction in value.
- Fill out the standardized devaluation ledger template with all required supporting data.
- Secure administrative approval from the management or finance team.
- Post the journal entry, debiting the Cost of Goods Sold (COGS) or a loss account, and crediting the Inventory or Allowance for Obsolescence account.
Ledger Template Integration and ERP Automation
While manual spreadsheets are a useful starting point, manual data entry remains a primary source of accounting errors. Integrating standardized devaluation templates into Enterprise Resource Planning (ERP) systems automates these complex calculations. By configuring specific business rules, the ERP can flag aging stock automatically based on historical turnover rates.
For example, using formulas like =IF(Days_In_Storage > 180, Original_Cost * 0.5, Original_Cost) directly within linked spreadsheets or ERP scripting engines ensures that devaluation schedules are applied uniformly. This automation reduces human touchpoints, accelerates closing cycles, and guarantees that calculations remain error-free.
Tax Compliance and Audit Trail Preservation
Navigating Tax Deductibility
Tax authorities often scrutinize inventory write-downs closely. In many jurisdictions, a book write-down is not automatically tax-deductible unless the inventory is physically disposed of or offered for sale at a reduced price within a specific timeframe. Failing to align accounting write-downs with tax regulations can lead to costly penalties during tax audits.
By utilizing standardized ledger templates, companies preserve a complete, defensible audit trail. These templates contain the precise historical evidence, authorization logs, and calculation methodologies that tax examiners require to validate deduction claims.
Continuous Optimization of Devaluation Protocols
Establishing a devaluation process is not a one-time project. Markets fluctuate, supply chains shift, and product lifecycles shorten, meaning that valuation policies must remain dynamic. Regularly reviewing ledger templates and adjusting obsolescence thresholds ensures that your financial strategies reflect current economic realities.
By analyzing patterns within your devaluation ledgers, management can identify systemic purchasing or production inefficiencies. Correcting these underlying operational issues helps minimize future write-downs, protecting your profit margins and maintaining a healthier balance sheet over the long term.
Leave a comment