For accounting professionals and S Corporation stakeholders, year-end tax preparation often triggers administrative gridlock. Reconciling inconsistent client data to align with stringent tax return requirements remains a tedious, error-prone struggle. Before addressing this annual bottleneck, it is crucial to recognize how evolving IRS reporting guidelines have dramatically narrowed the margin for error.
Implementing standardized financial statement templates resolves this tension, granting firm partners the administrative leverage to reclaim billable hours and minimize compliance risks. While these templates do not replace strategic CPA oversight, they establish an indispensable baseline of data integrity. By utilizing structured formats for the Balance Sheet, Schedule L, and Schedule M-1 reconciliations, firms gain concrete proof of mathematical consistency across all filings.
This article outlines the core components of effective S Corp templates, practical integration strategies for your tech stack, and best practices for accelerating your reporting workflow.
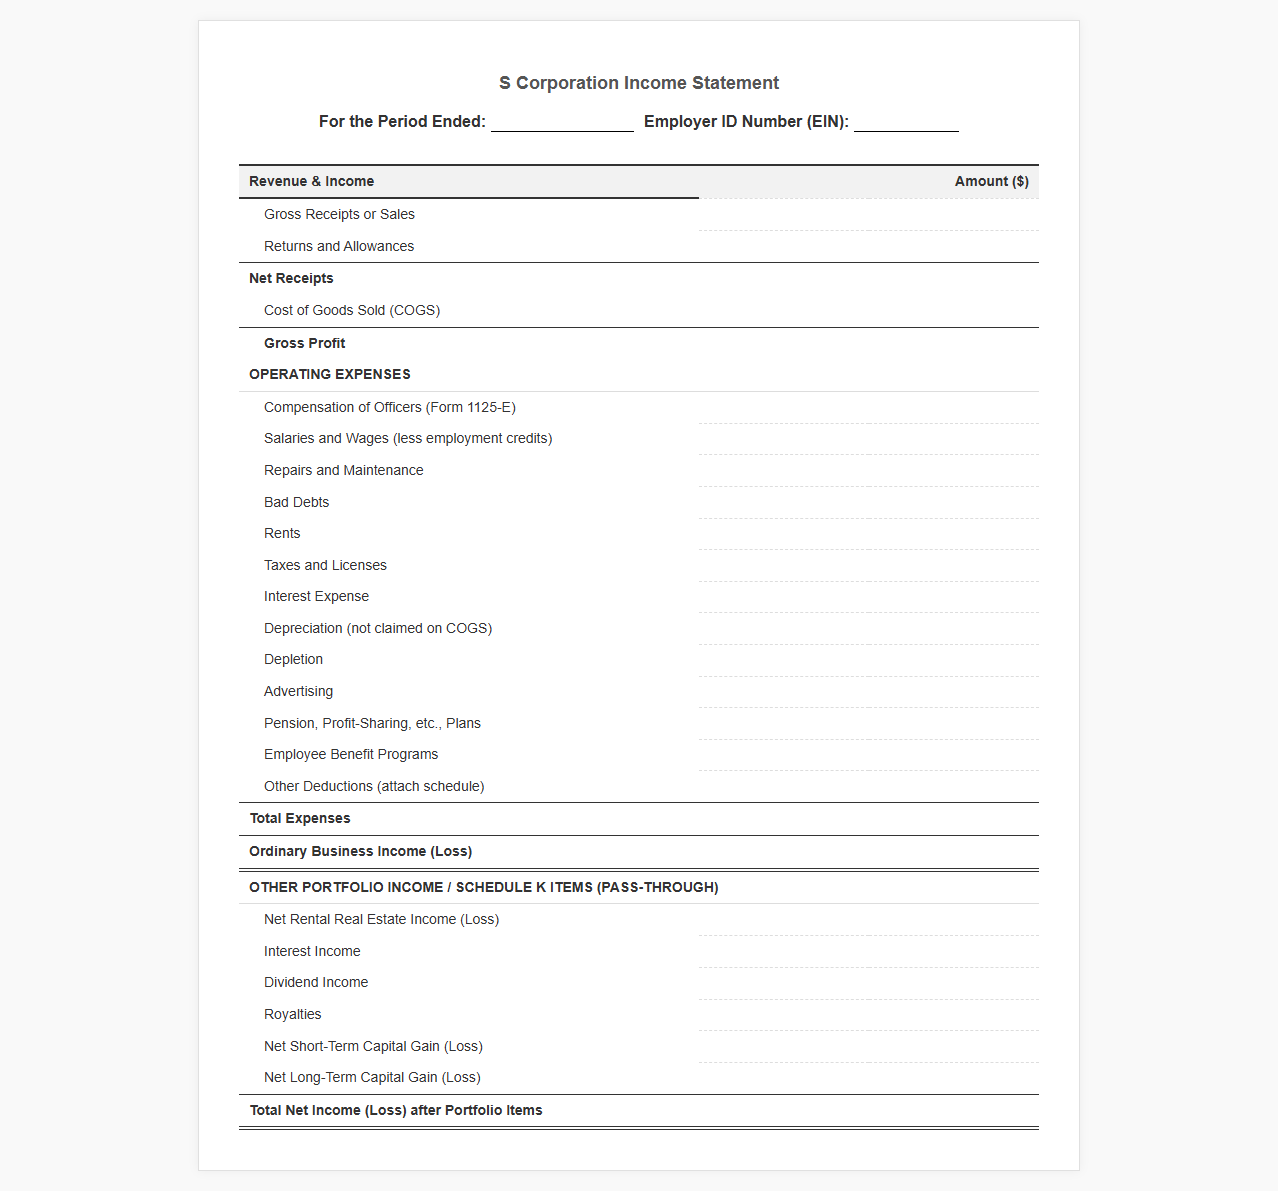
S Corporation Income Statement Template
 Download: .PDF
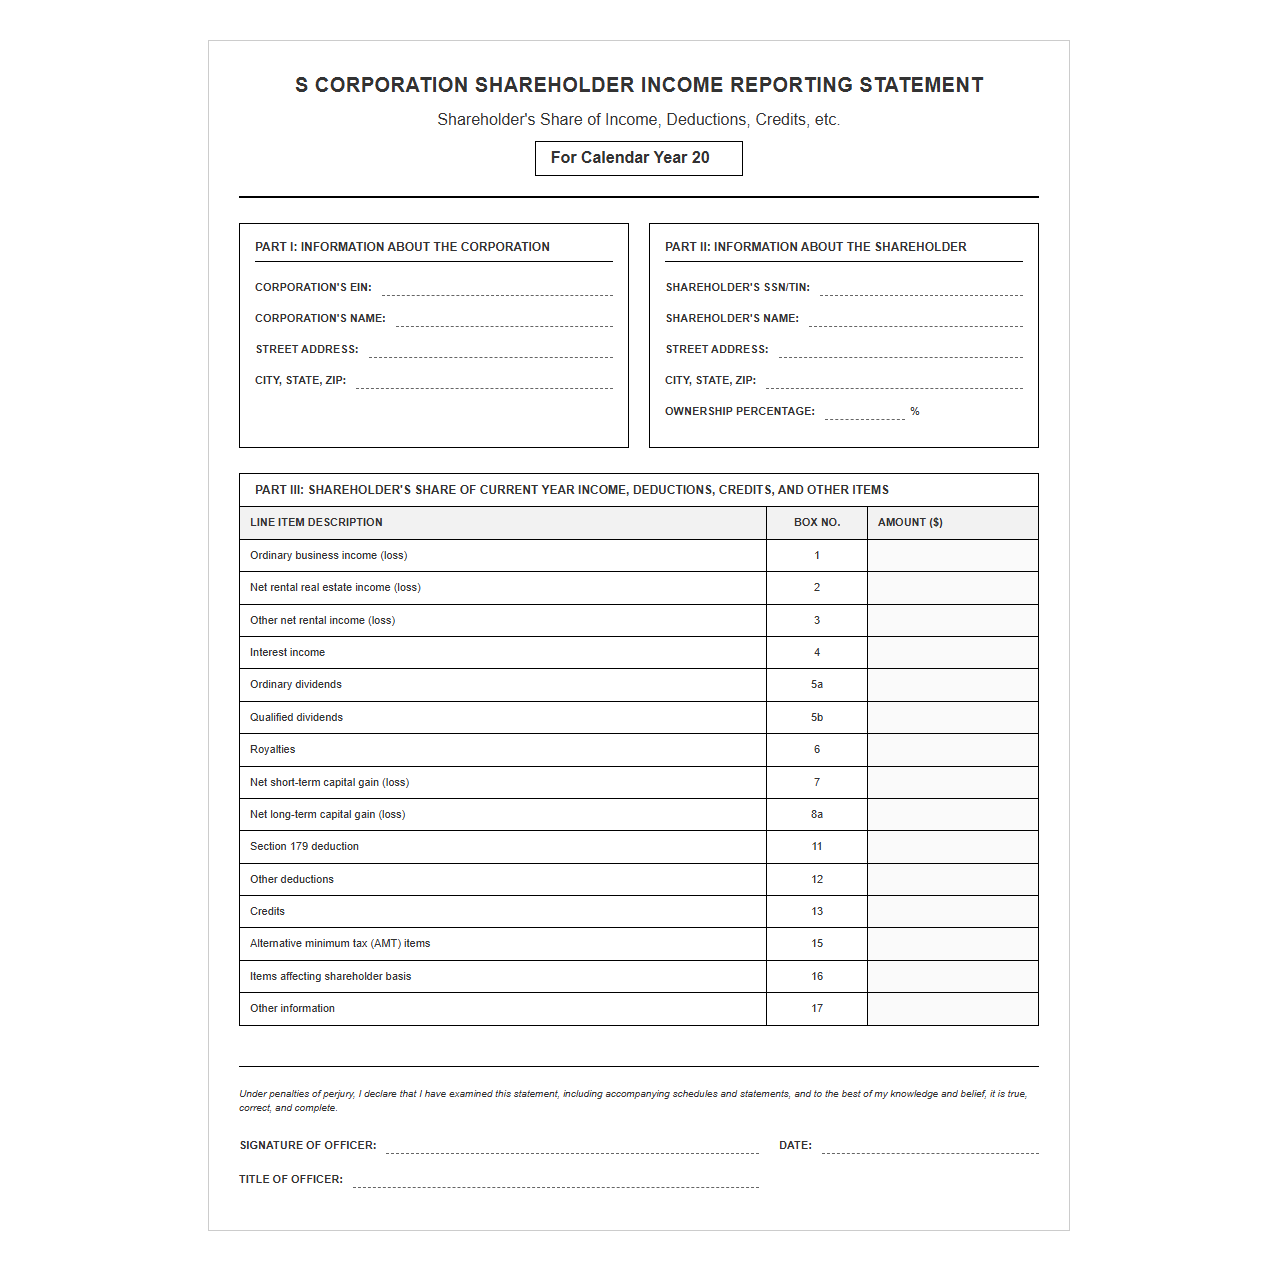
S Corp Shareholder Income Reporting Statement
 Download: .PDF
S Corporation Revenue and Income Statement Template
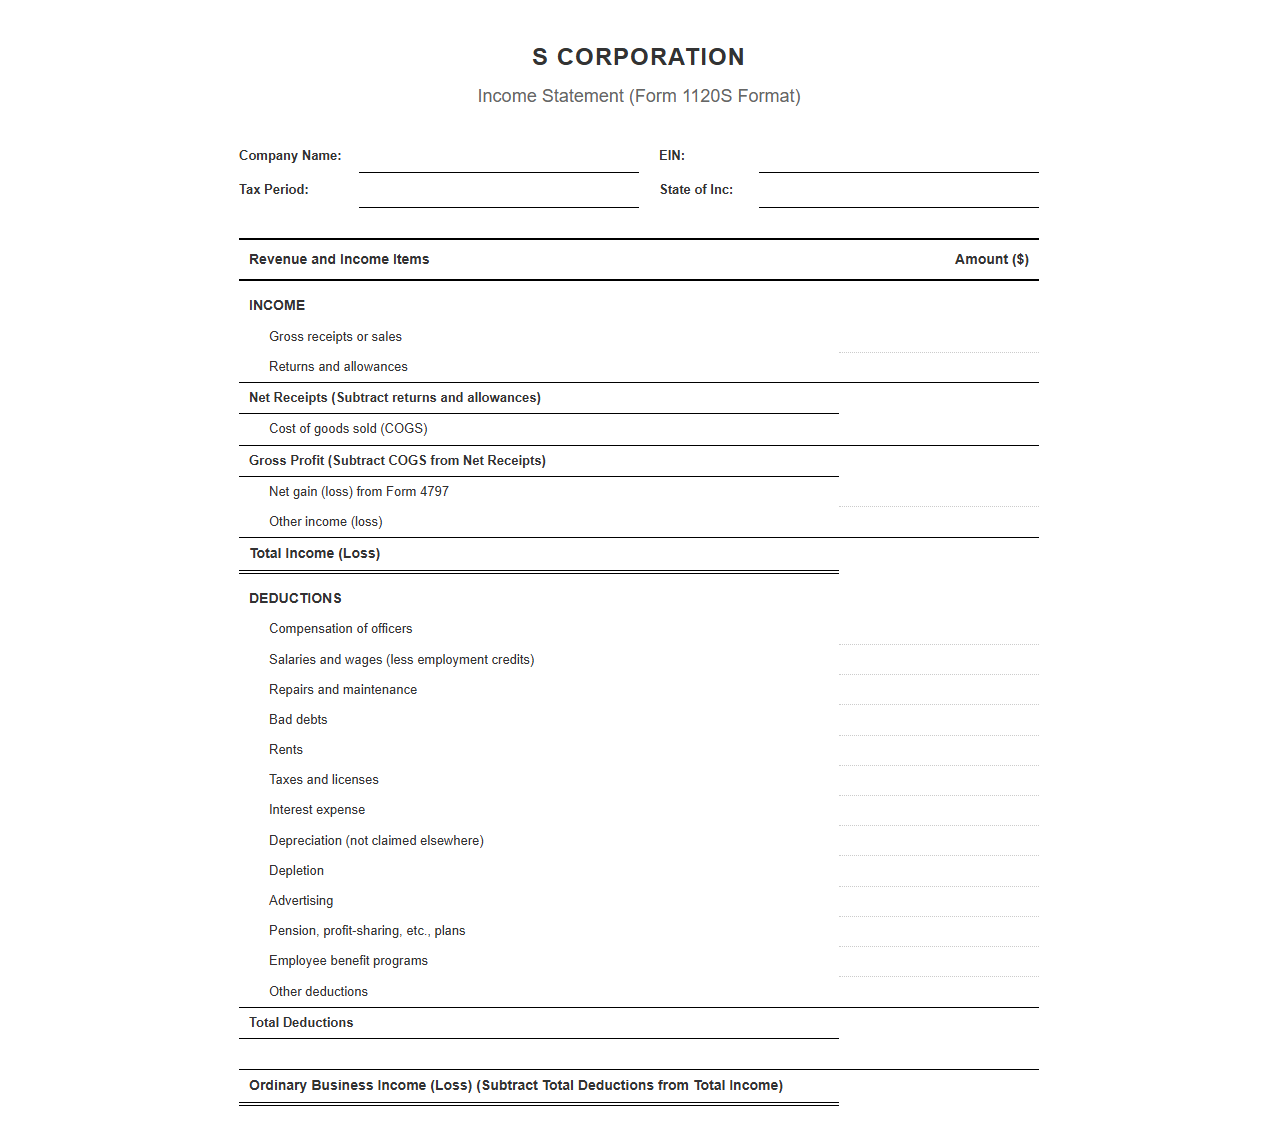 Download: .PDF
S Corp Annual Income Declaration Template
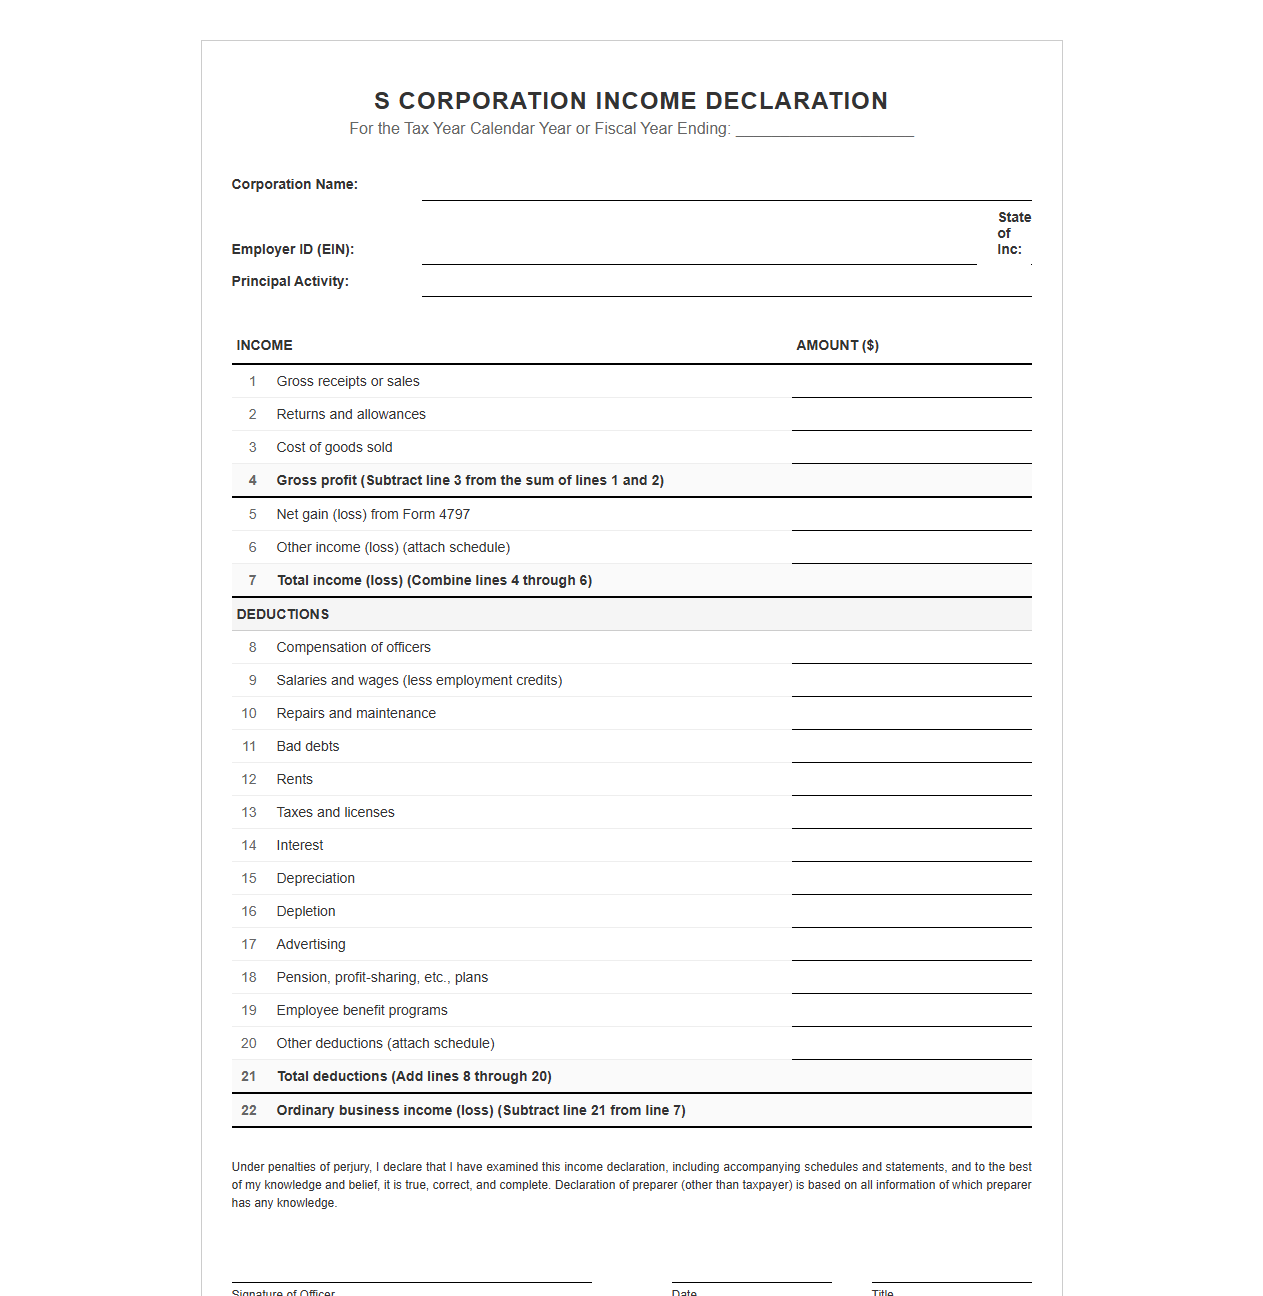 Download: .PDF
Template for S Corporation Income and Expenses
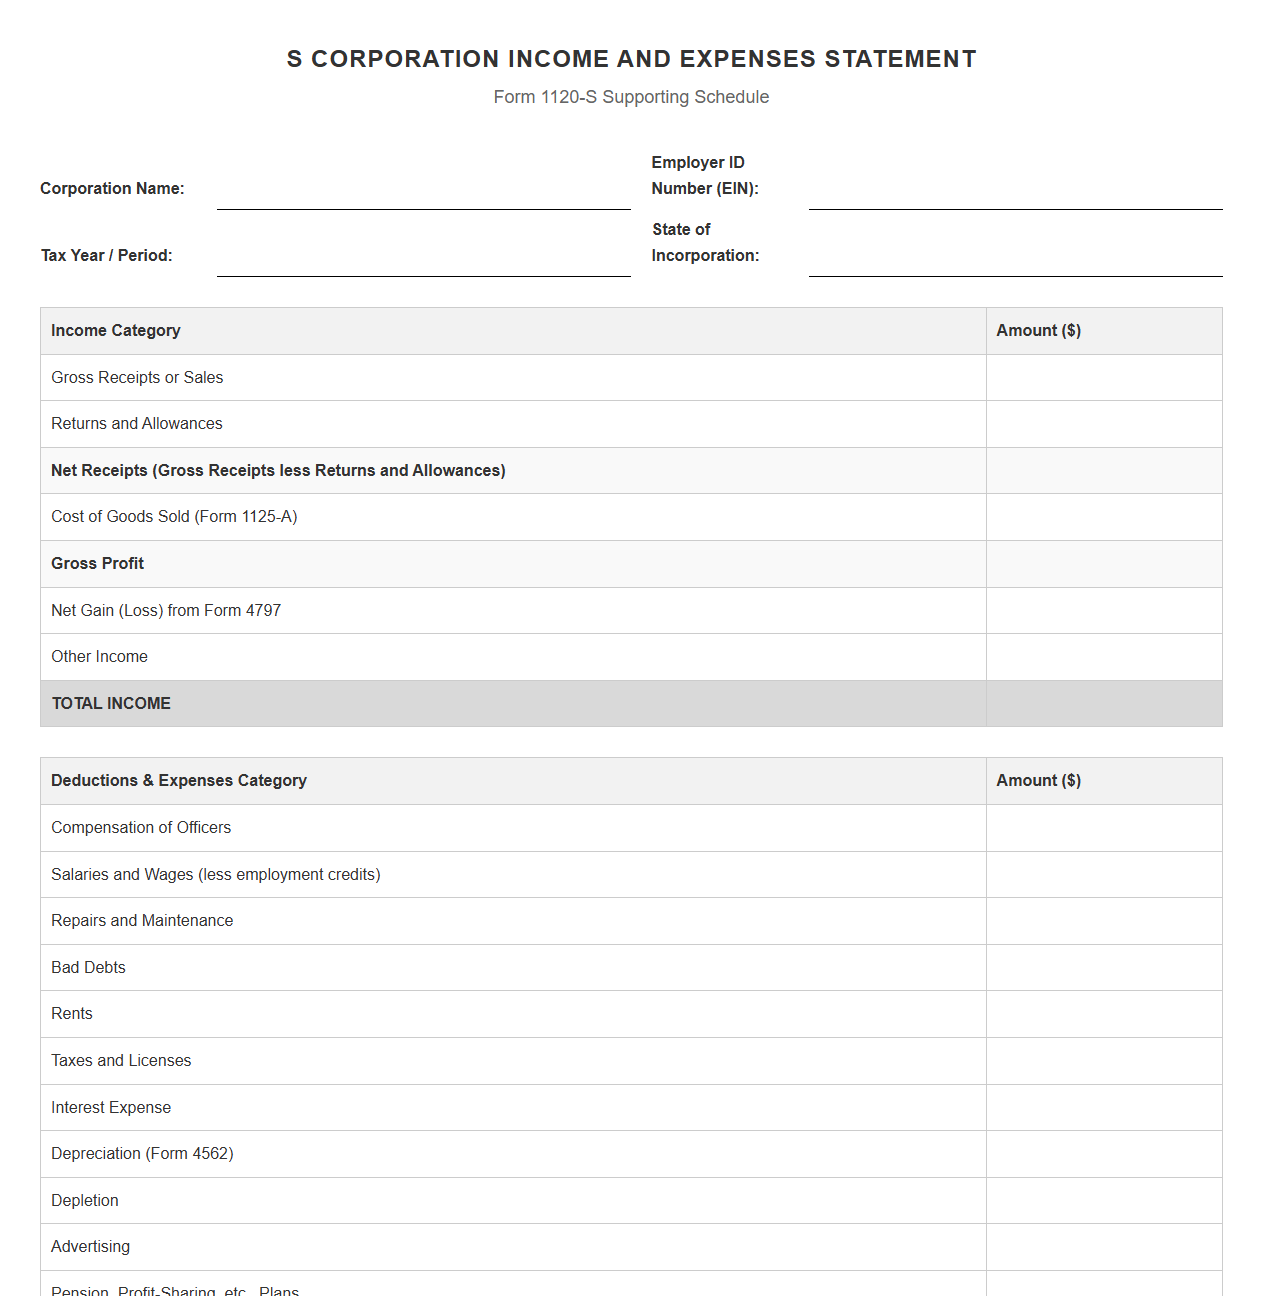 Download: .PDF
S Corporation Net Income Statement Form
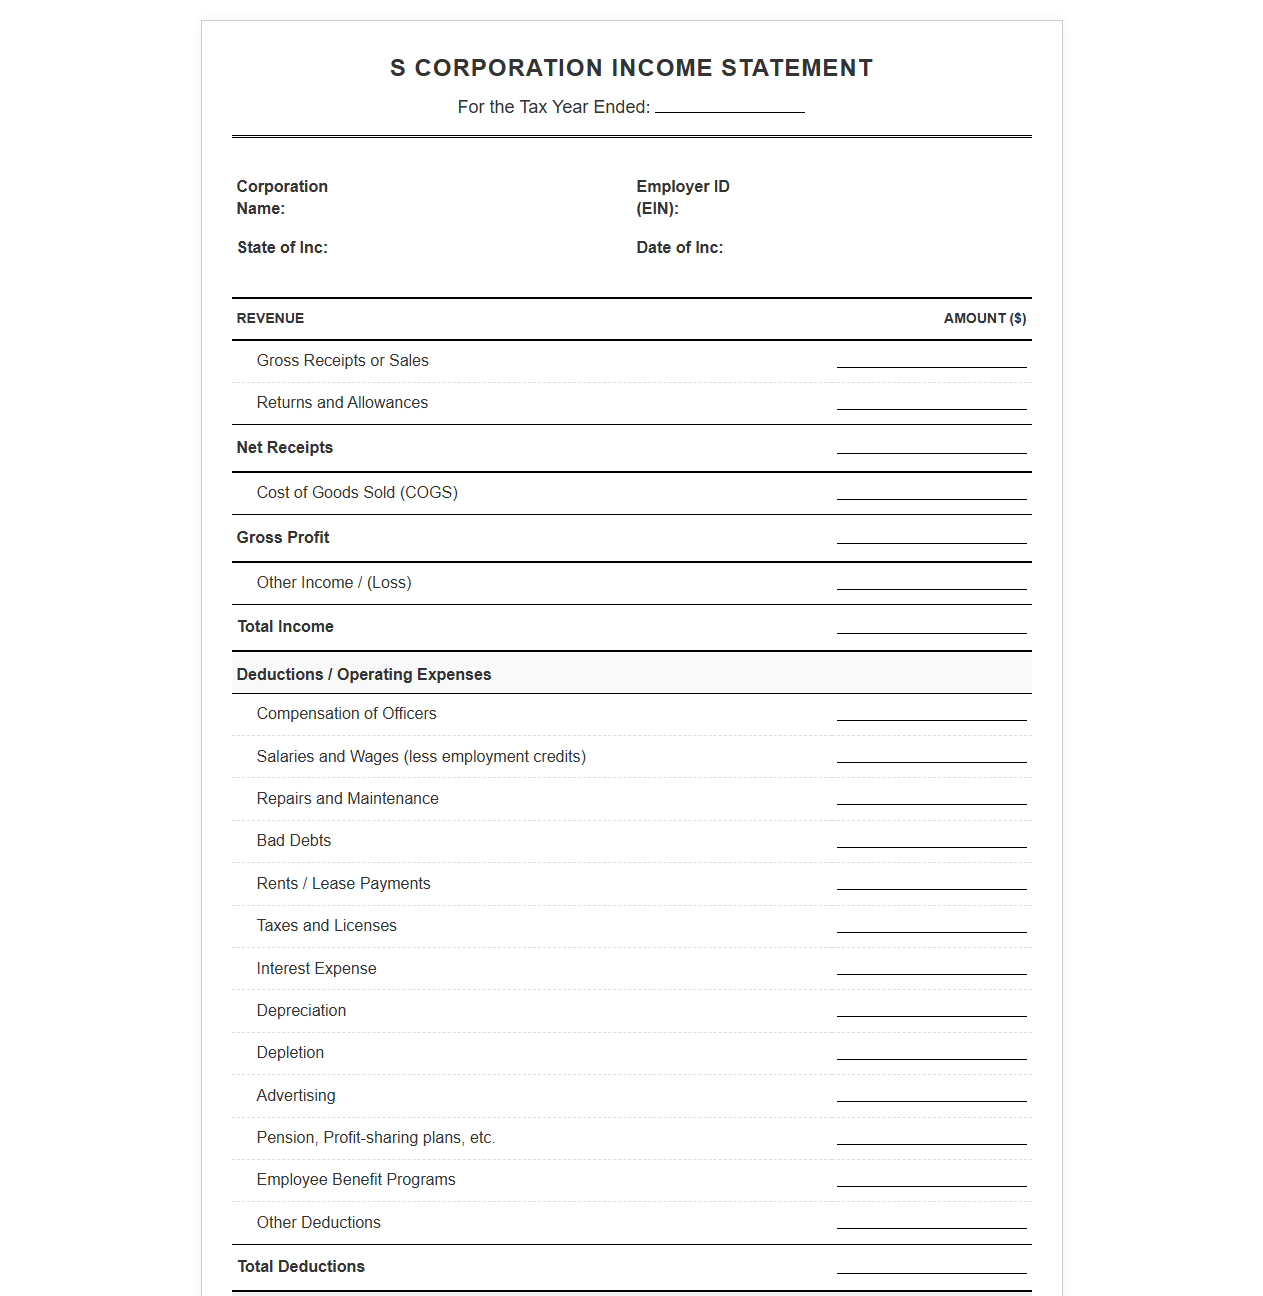 Download: .PDF
Shareholder Distributive Share Income Statement Template
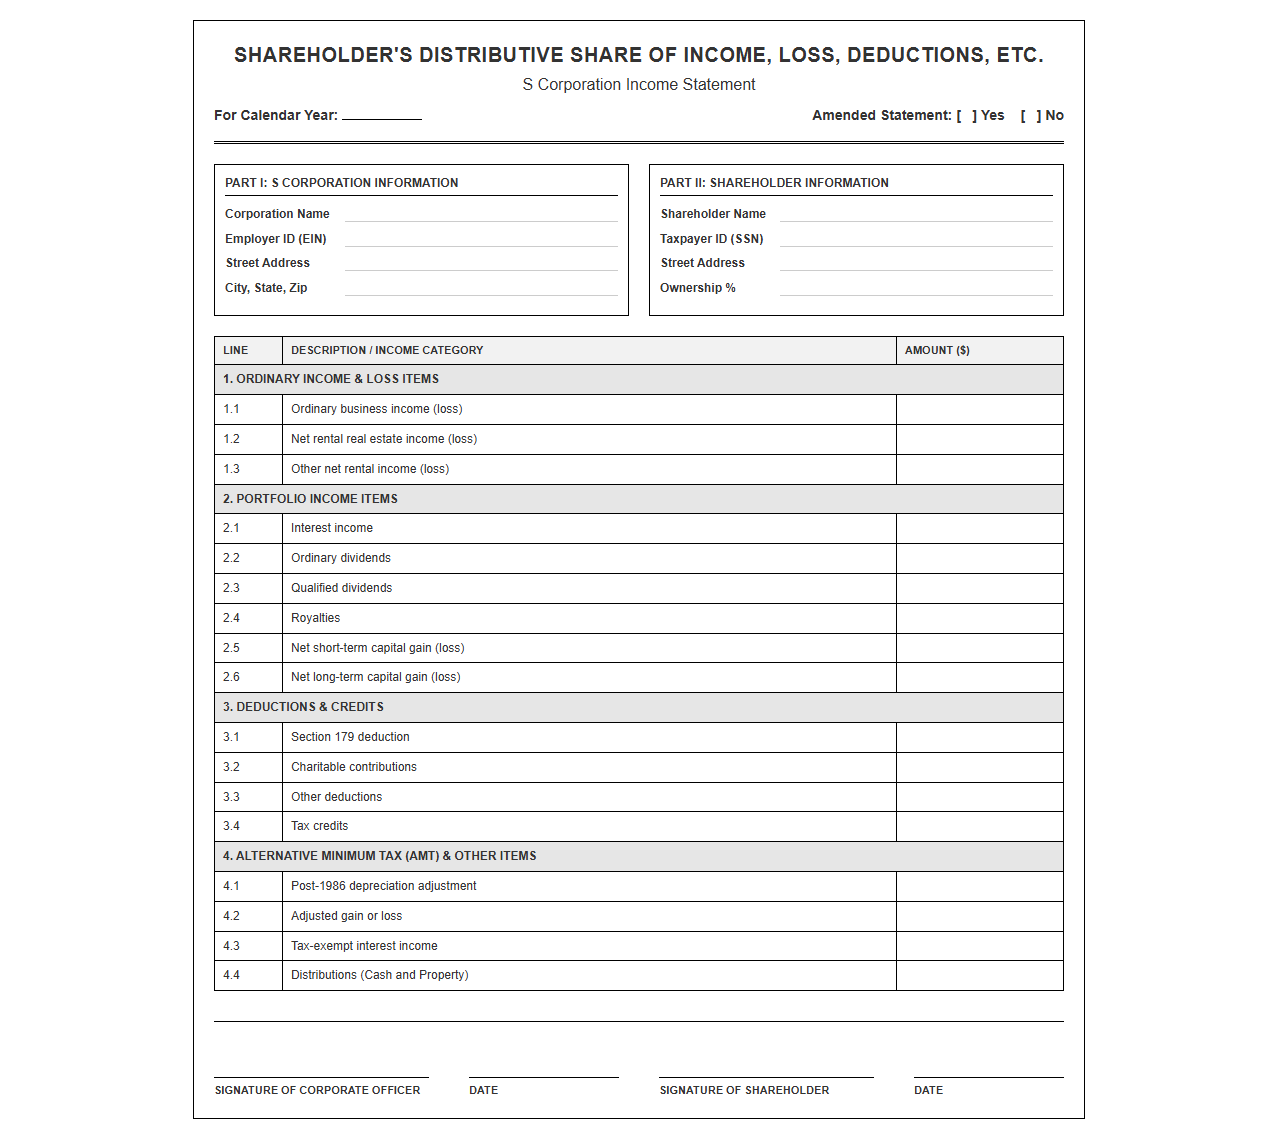 Download: .PDF
S Corp Income Tax Return Statement Template
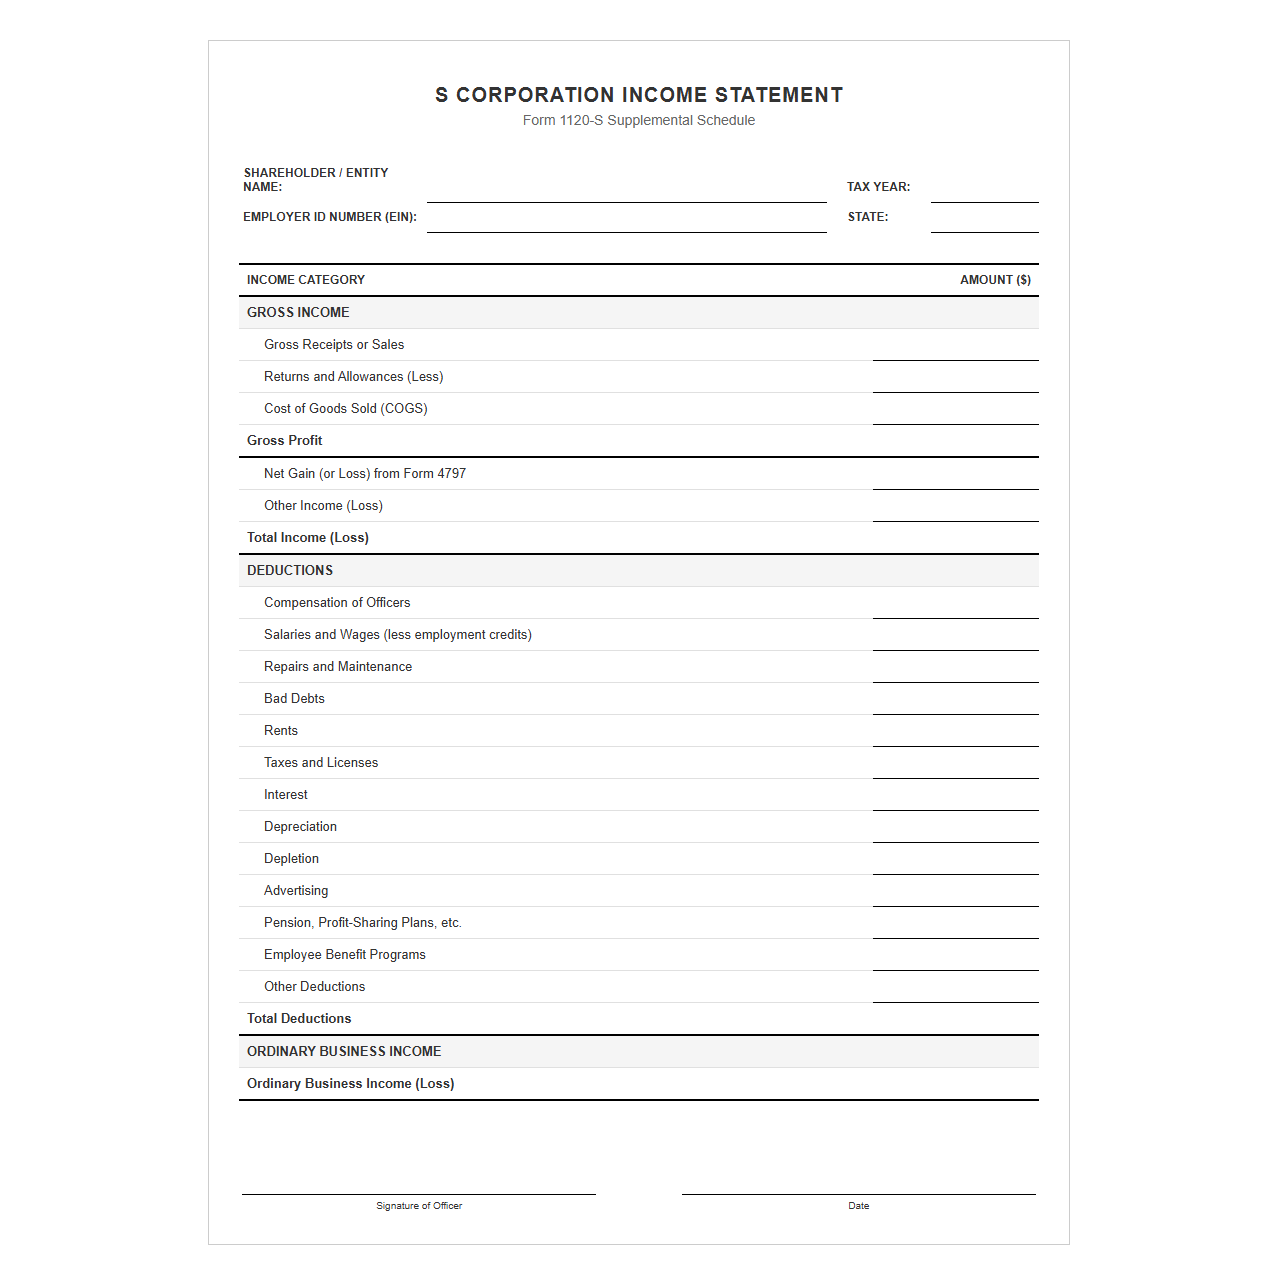 Download: .PDF
S Corporation Financial Income Summary Template
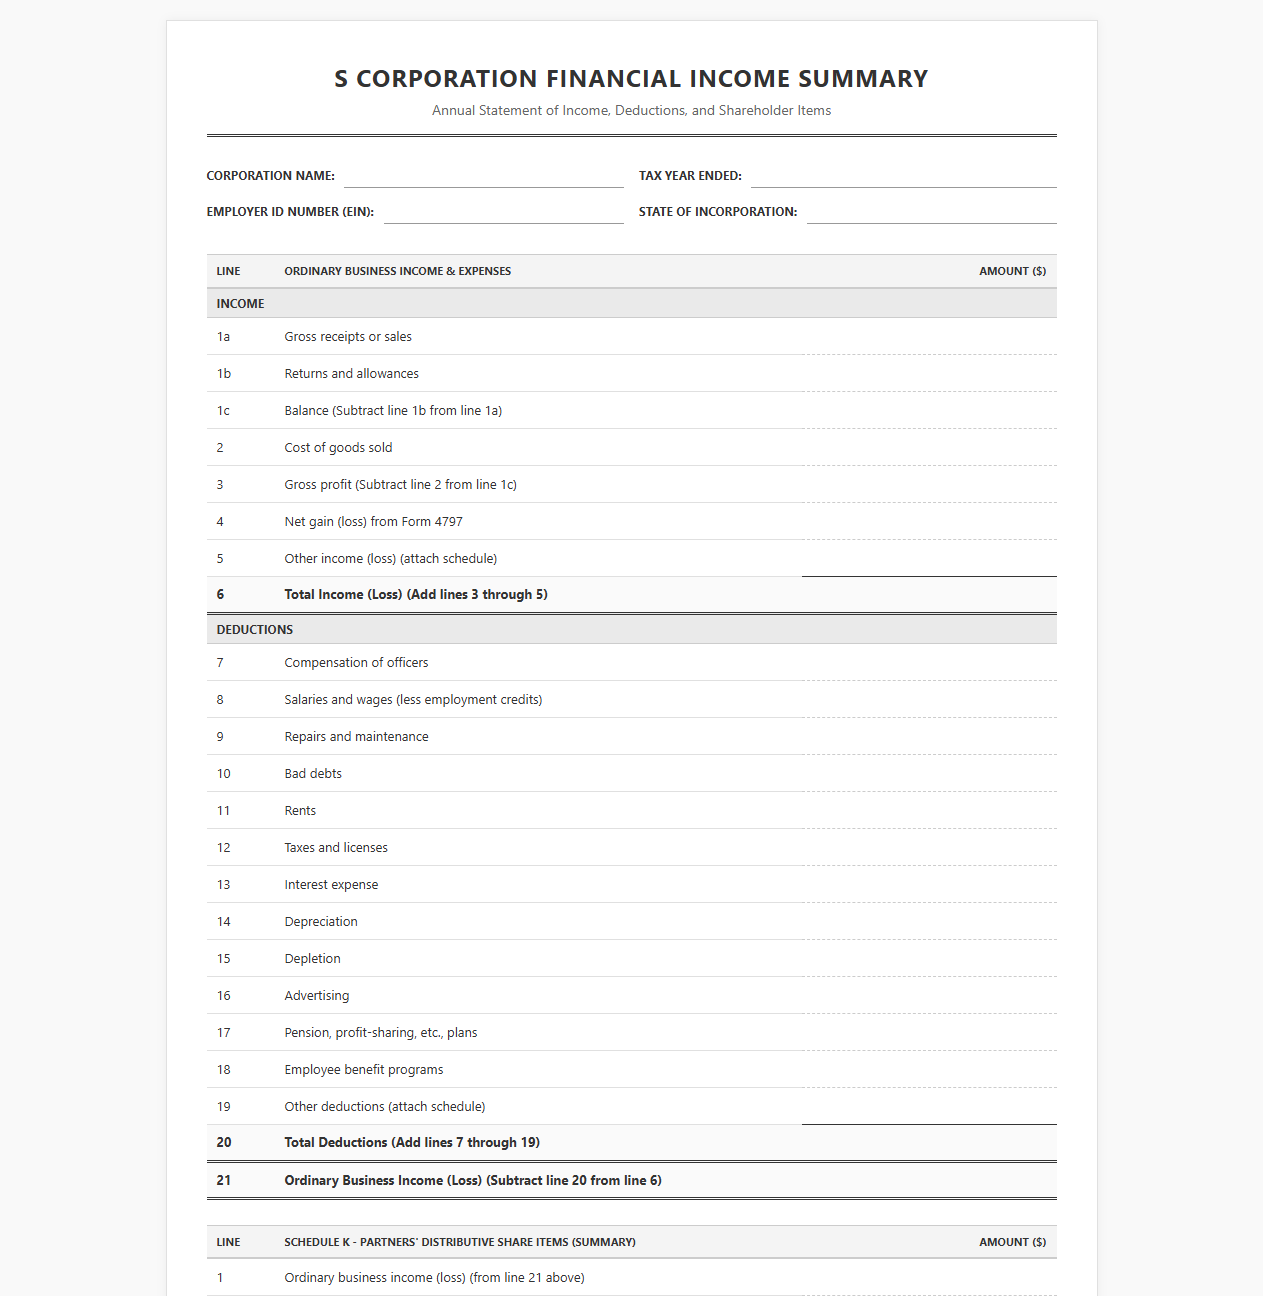 Download: .PDF
The Complexity of S Corporation Income Reporting
S Corporations offer significant tax advantages, but they also introduce a unique layer of financial complexity. Unlike traditional corporations, S Corps utilize a pass-through taxation model. This means the business itself does not pay federal income tax; instead, profits, losses, deductions, and credits flow directly through to the shareholders' individual tax returns. While this avoids double taxation, it places a massive administrative burden on the business owners to maintain pristine records.
When financial data is disorganized, the consequences are immediate and severe. Inaccurate bookkeeping leads to costly filing errors, missed deductions, and an increased risk of IRS audits. Without a structured system, tracking the exact flow of income and distributions becomes nearly impossible, turning annual tax preparation into a stressful and expensive ordeal.
The Benefits of Standardizing Financial Statements
Implementing standardized financial templates transforms the chaotic tax season into a highly manageable, predictable routine. By establishing a uniform format for recording daily transactions, S Corporations can experience several critical advantages:
- Streamlined Workflow: Standardized templates reduce the time spent on manual data entry and classification, ensuring that transactions are recorded consistently every single month.
- Improved Accuracy: Built-in formulas and structured categories minimize human error, reducing the likelihood of mathematical discrepancies or misallocated funds.
- Seamless CPA Collaboration: CPAs require clean, structured data to file Form 1120-S. Standardized reports allow external tax professionals to quickly extract necessary figures, resulting in lower preparation fees and faster filing turnarounds.
Core Components of an S Corp Financial Template
A robust, standardized financial template tailored for an S Corporation must track specific variables that regular LLCs or sole proprietorships might overlook. To ensure comprehensive reporting, the template must include the following core elements:
- The Balance Sheet: This tracks the company's assets, liabilities, and equity at any given point, which is essential for proving the financial health of the business to lenders and the IRS.
- The Income Statement (Profit and Loss): This details the revenue generated and the expenses incurred, grouping them into distinct categories that match tax-deductible classifications.
- Shareholder Basis Tracking: Crucial for S Corps, this component monitors each owner's stock and debt basis, determining the taxability of distributions and the deductibility of pass-through losses.
Aligning Templates with Schedule K-1 Requirements
The bridge between an S Corporation's internal bookkeeping and its tax filing is the IRS Schedule K-1 (Form 1120-S). Every shareholder receives a K-1 detailing their specific share of income, deductions, and credits. To ensure flawless reporting, the categories within your internal income statement should map directly to the corresponding lines on the K-1 form.
| Income Statement Line Item | Form 1120-S / Schedule K-1 Destination | Tax Impact / Treatment |
|---|---|---|
Ordinary Business Income |
Schedule K-1, Box 1 | Passes through as ordinary income to shareholder tax returns. |
Net Rental Real Estate Income |
Schedule K-1, Box 2 | Subject to passive activity loss limitation rules. |
Interest Income |
Schedule K-1, Box 4 | Reported as portfolio income on Schedule B of the individual return. |
Section 179 Expense |
Schedule K-1, Box 11 | Passed through for immediate equipment depreciation deduction. |
Step-by-Step Guide to Implementing Standardized Templates
Transitioning from unorganized books to a structured, template-based system requires a methodical approach. Follow these steps to establish a reliable foundation for your S Corp accounting:
- Reconcile Past Accounts: Before transferring data, ensure all bank accounts, credit cards, and loan balances for the current fiscal year are fully reconciled against bank statements.
- Map the Chart of Accounts: Customize your template's chart of accounts to reflect the exact line items required on Form 1120-S and Schedule K-1.
- Migrate Historical Data: Input your reconciled historical financial data into the new template, ensuring that every transaction aligns with the newly defined categories.
- Establish Monthly Review Routines: Set aside time at the end of every month to input fresh data, run automated reconciliation checks, and review the balance sheet.
- Share Access with Your CPA: Grant your tax professional read-only access to the standardized template throughout the year to catch and correct anomalies early.
Common Pitfalls in S Corp Reporting and How Templates Prevent Them
One of the most frequent accounting mistakes made by S Corporations is the misclassification of shareholder payments. Business owners often confuse reasonable compensation with shareholder distributions, leading to severe tax penalties. IRS guidelines dictate that active shareholders must receive a reasonable salary subject to payroll taxes before taking non-dividend distributions.
"Failure to separate shareholder wages from distributions is a primary target for IRS auditors. Without clear boundaries, the agency can recharacterize distributions as wages, resulting in back taxes, interest, and steep penalties on unpaid employment taxes."
Standardized templates eliminate this risk by establishing strict, separate categories for W-2 officer compensation and shareholder distributions. By hardcoding these constraints into the template structure, business owners are prevented from accidentally co-mingling these distinct financial flows.
Achieving Long-Term Efficiency and Tax Readiness
Continuous financial standardization is more than a tool for filing annual taxes; it is an essential strategy for business growth and operational security. Maintaining clean, standardized financial templates year-round ensures that the business is always prepared to present accurate records during audits or when applying for corporate financing. S Corp owners can confidently transition their focus from administrative damage control to proactive business scaling by utilizing structured systems. To optimize your tax workflow today, you can download specialized tools and find additional guidance on the Internal Revenue Service (IRS) official portal.
Leave a comment