Managing fluctuating inventory costs is a constant struggle for finance teams, where manual calculation errors frequently distort profit margins and compromise tax reporting. Before deploying any software solution, organizations must first establish a logical framework to align physical stock movement with cost flow assumptions. Standardizing this process through structured ledger templates grants your business unmatched balance sheet accuracy and audit readiness.
However, users must recognize that these templates are not self-sustaining; their utility relies entirely on disciplined, real-time data entry of incoming stock batches. For instance, tracking a batch of lithium-ion batteries purchased at $120 per unit before transitioning to a subsequent lot priced at $135 requires flawless chronological sequencing to preserve FIFO integrity.
This guide provides an in-depth look at implementing FIFO inventory valuation ledger templates, outlining essential design structures, step-by-step calculation workflows, and best practices for maintaining precise cost flow tracking.
FIFO Inventory Valuation Ledger Template
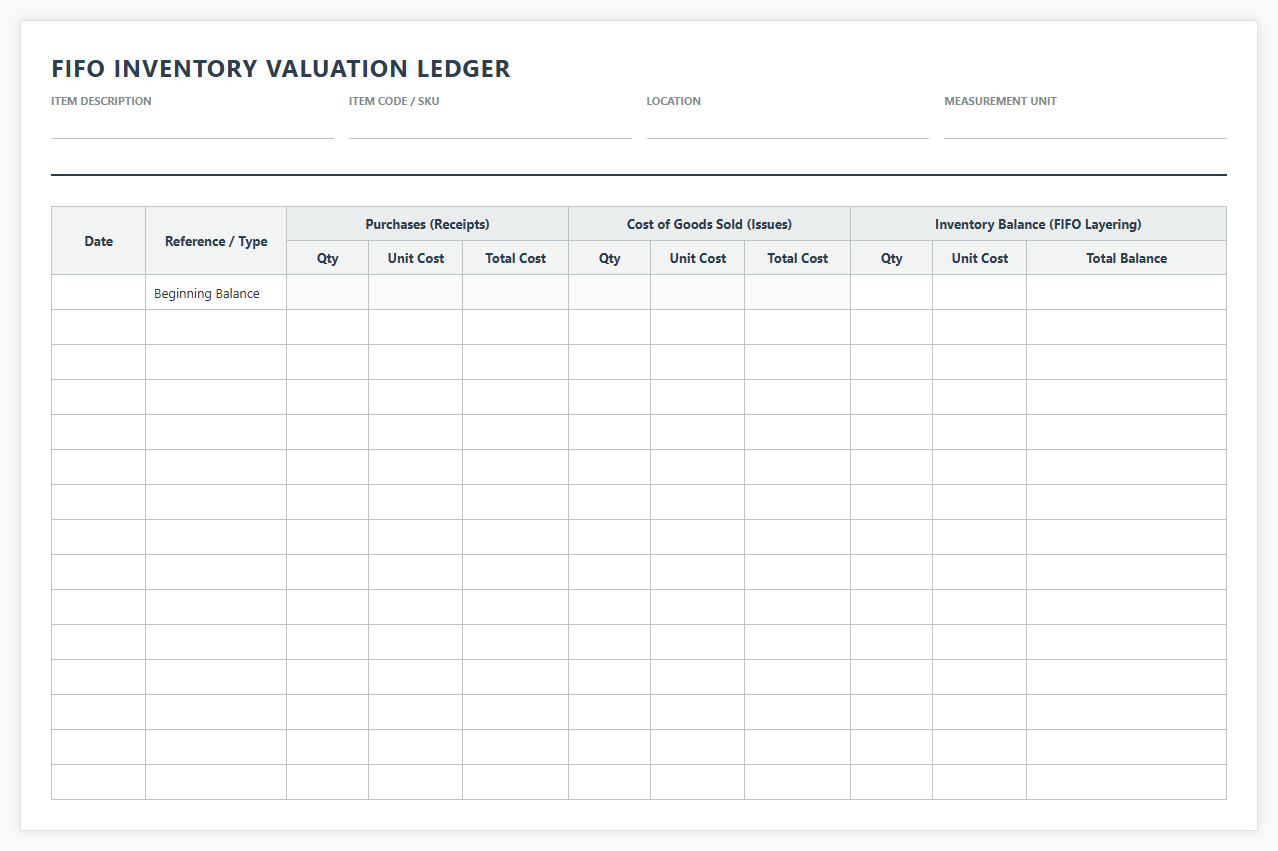 Download: .PDF
First-In First-Out Stock Valuation Ledger
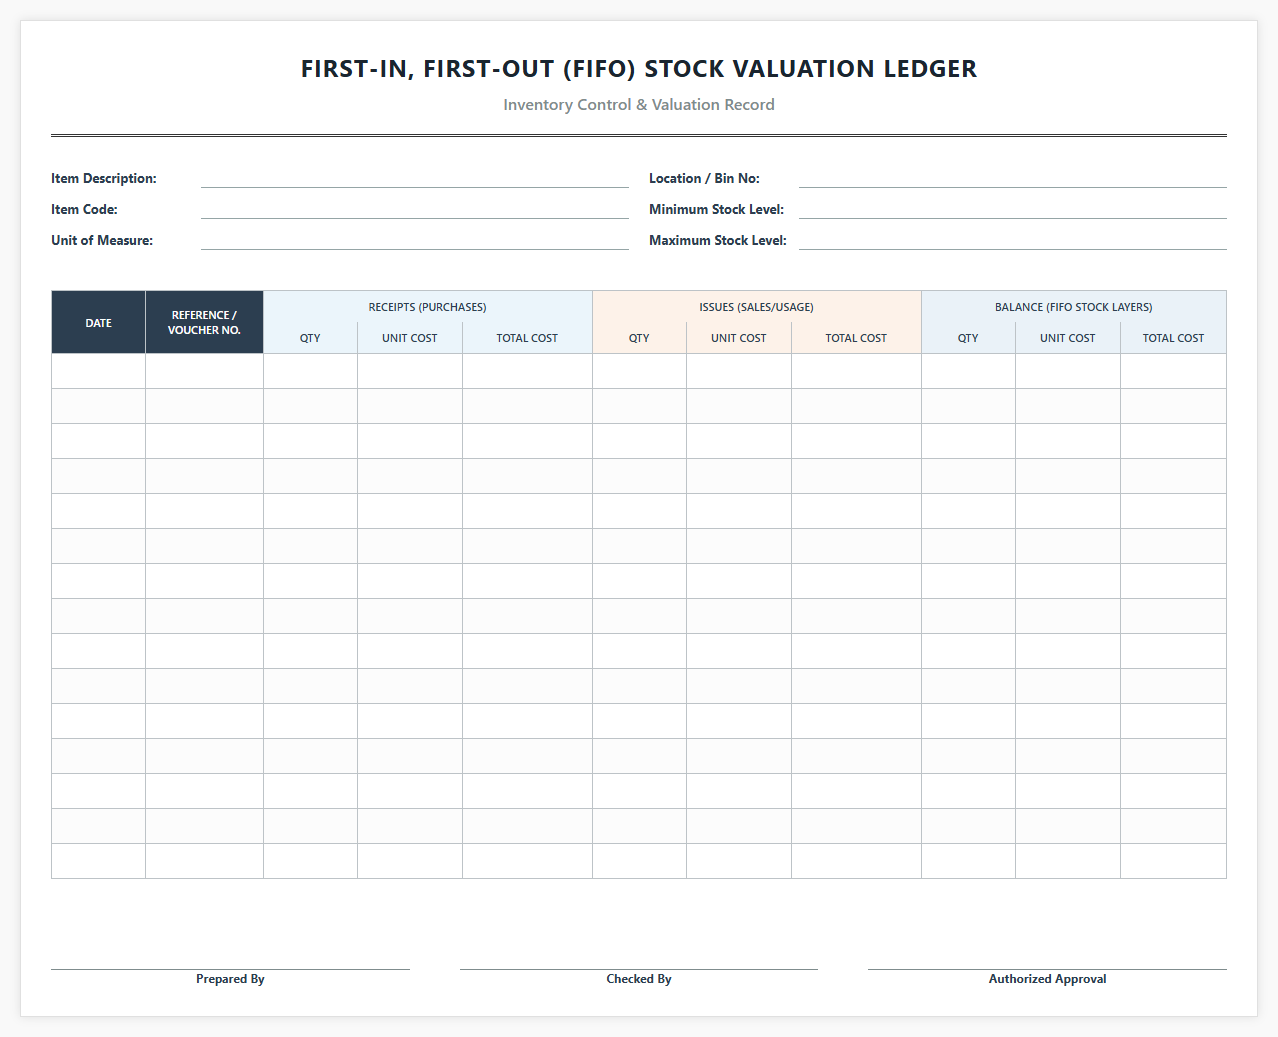 Download: .PDF
FIFO Inventory Accounting Ledger Sheet
 Download: .PDF
FIFO Stock Ledger for Inventory Valuation
 Download: .PDF
Inventory Valuation Sheet using FIFO Method
 Download: .PDF
FIFO Method Inventory Tracking Ledger
 Download: .PDF
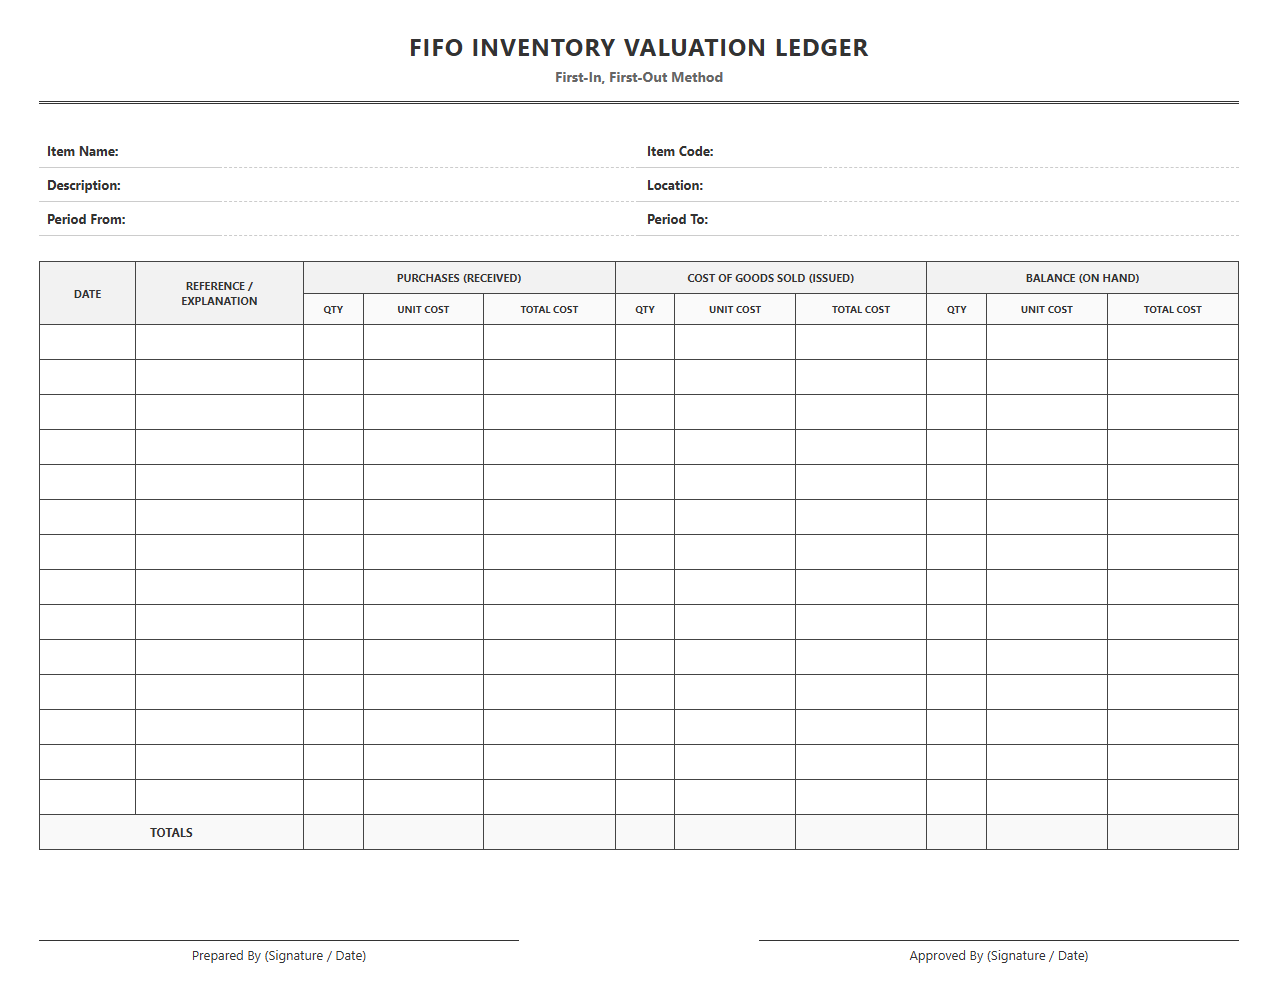
First-In First-Out Inventory Valuation Template
 Download: .PDF
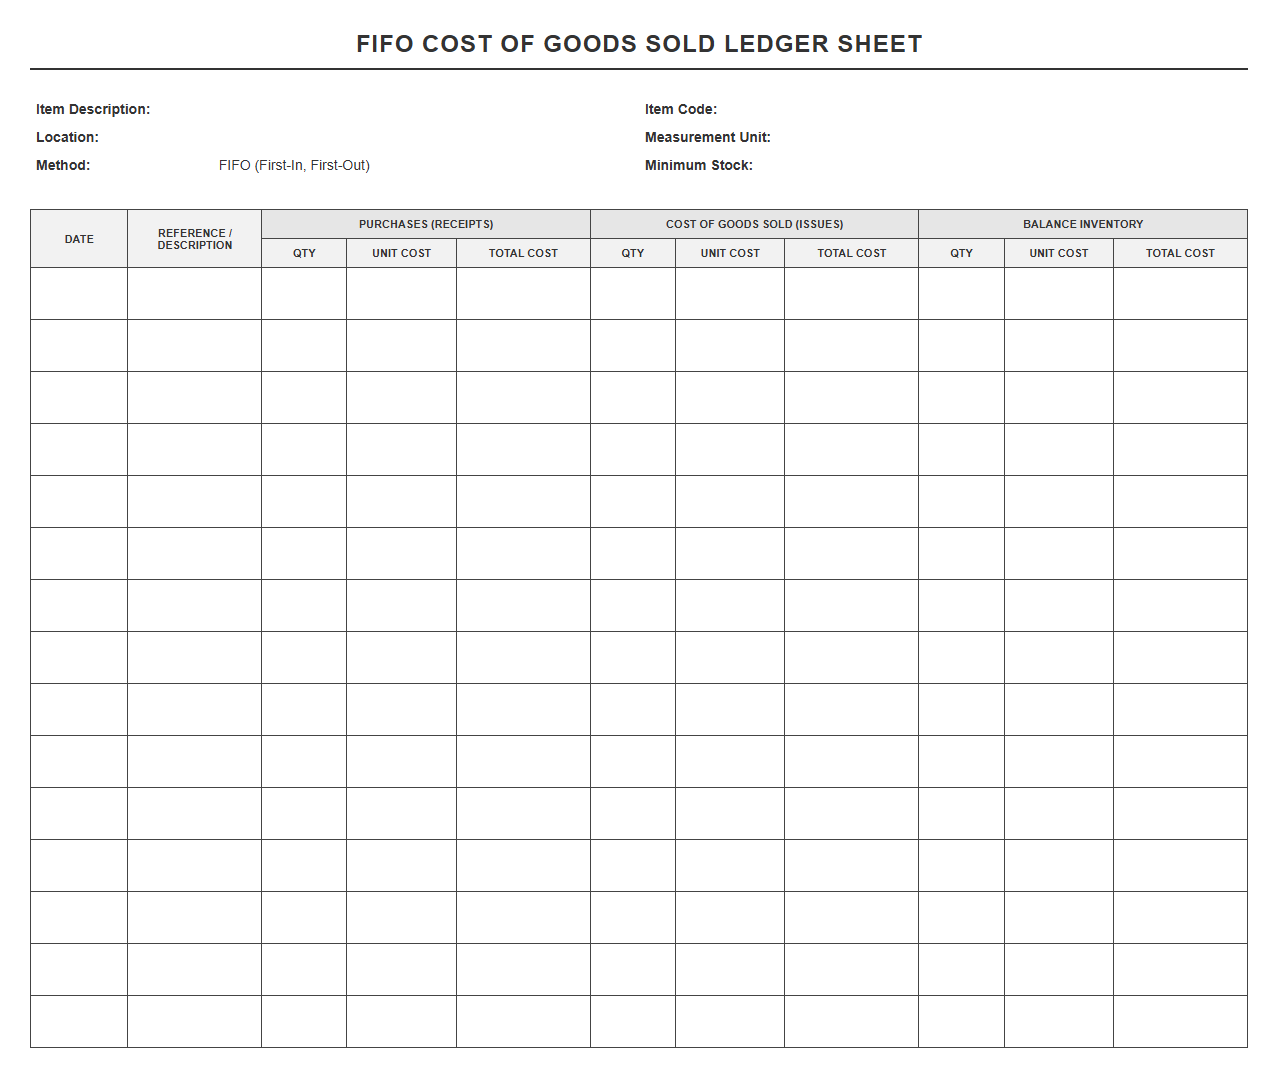
FIFO Cost of Goods Sold Ledger Sheet
 Download: .PDF
Demystifying FIFO Inventory Valuation
In the realm of inventory management, the First-In, First-Out (FIFO) method stands as a foundational pillar. The core principle of FIFO is straightforward: the oldest stock acquired is assumed to be sold first. Consequently, the cost of your earliest purchases is matched against current revenue, while the newest, most recently purchased inventory remains on the balance sheet.
This systematic approach is crucial for maintaining accurate financial reporting, especially during inflationary periods, as it prevents the undervaluation of remaining assets. Furthermore, tax authorities worldwide favor FIFO because its structured logic provides a clear, verifiable trail that ensures strict tax compliance and prevents arbitrary income manipulation.
Core Components of a FIFO Ledger Template
To build a functional FIFO inventory ledger, you must establish a clear data structure. Every transaction must be tracked with granular detail to ensure that cost layers are properly recorded and depleted over time.
A robust FIFO template requires several essential columns and data fields:
- Date: The exact timestamp of the transaction to maintain strict chronological order.
- Transaction Type: A label specifying whether the entry is a "Purchase" (inflow) or a "Sale" (outflow).
- Quantity: The number of units added to or removed from the warehouse.
- Unit Cost: The specific acquisition cost per unit for that specific batch.
- Total Value: The calculated financial value of the transaction, representing quantity multiplied by unit cost.
Designing the Inventory Inflow and Outflow Logs
To maintain structural integrity, the ledger must cleanly distinguish between stock additions and stock depletions. Placing these entries in a unified, chronologically sorted log allows you to trace the sequential movement of goods without losing visibility of individual cost layers.
| Date | Type | Qty In | Cost In | Qty Out | Cost Out | Balance Qty |
|---|---|---|---|---|---|---|
| 2026-01-01 | Purchase | 100 | 10.00 | - | - | 100 |
| 2026-01-05 | Purchase | 50 | 12.00 | - | - | 150 |
| 2026-01-10 | Sale | - | - | 120 | 10.33 | 30 |
Mapping the Cost Flow Logic
The core mechanic of FIFO involves matching sales against the oldest available inventory batches. When a sale occurs, the template must systematically evaluate and deplete your inventory layers in order of acquisition.
- Identify the total number of units sold in the current transaction.
- Locate the oldest active inventory batch containing unsold units by checking the
Datefield. - Deduct the sold units from this oldest batch. If the sale quantity is less than or equal to the batch quantity, apply the batch's unit cost to the sale.
- If the sale quantity exceeds the oldest batch size, deplete that batch entirely to
0and apply the remaining sales volume to the next chronological inventory layer. - Repeat this sequential depletion process until the entire sales transaction is fully accounted for.
This disciplined logic ensures that older, lower-cost layers are cleared out before newer, higher-cost layers are touched.
Calculating Ending Inventory and Cost of Goods Sold (COGS)
With your cost flow logic mapped, you can easily compute the two most vital figures for your financial statements: the value of your remaining inventory and the total cost of the goods you sold.
Cost of Goods Sold (COGS) Formula:
COGS = Sum of (Units Sold from Batch * Unit Cost of Batch)
Ending Inventory Formula:
Ending Inventory = Sum of (Remaining Units in Batch * Unit Cost of Batch)
To verify these calculations in your ledger, you can use the accounting equation where the sum of COGS and Ending Inventory must equal the total cost of beginning inventory plus purchases. Pressing Ctrl + F9 in your spreadsheet software can refresh these calculated fields to ensure real-time balance sheet accuracy.
Step-by-Step Spreadsheet Implementation
Translating this logic into Microsoft Excel or Google Sheets requires a structured approach to cell formatting and basic formula design.
A1: Date | B1: Transaction Type | C1: Quantity | D1: Unit Cost | E1: Total Cost
A2: 2026-01-01 | B2: Purchase | C2: 100 | D2: 10.00 | E2: =C2*D2
Follow these steps to complete the implementation:
- Format the "Date" column as "YYYY-MM-DD" to prevent chronological sorting errors.
- Format "Unit Cost" and "Total Cost" columns as Currency with two decimal places.
- Use conditional formatting to highlight rows where current stock levels fall below safety thresholds.
- Apply a formula like
=SUMIF(B:B, "Purchase", C:C) - SUMIF(B:B, "Sale", C:C)to quickly calculate total remaining inventory units.
Best Practices for Ledger Maintenance and Auditing
A FIFO ledger is only as reliable as the data entered into it. Regular upkeep prevents discrepancies from compounding over time, ensuring your books are always ready for scrutiny. Physical inventory counts should be performed monthly or quarterly to reconcile actual warehouse stock with the numbers recorded in your digital ledger.
When handling customer returns, ensure the returned items are placed back into the correct chronological inventory layer. For year-end tax audits, keep detailed purchase invoices alongside your ledger, as auditors will verify that the unit costs listed in your oldest remaining batches match historical physical records. Maintaining this level of diligence keeps your business financially transparent and compliant.
Leave a comment