Many enterprise leaders consistently struggle with unpredictable financial advisory costs and insidious scope creep that quietly erode trust with their external financial partners. Historically, businesses relied on reactive, hourly billing models, but navigating modern market volatility requires a transition toward highly structured, proactive partnerships.
Transitioning to a strategic retainer model grants organizations absolute budget predictability and continuous access to high-level advisory. However, an essential educational stipulation must be established: a successful retainer is not a blank check for unlimited ad-hoc tasks, but rather a structured commitment to specific deliverables. For example, explicitly embedding monthly cash flow forecasting and biannual tax optimization audits into the agreement ensures tangible, high-value outcomes rather than vague administrative support.
Below, we outline the proven frameworks and negotiation strategies necessary to structure these agreements, ensuring long-term financial alignment and mutual operational success.
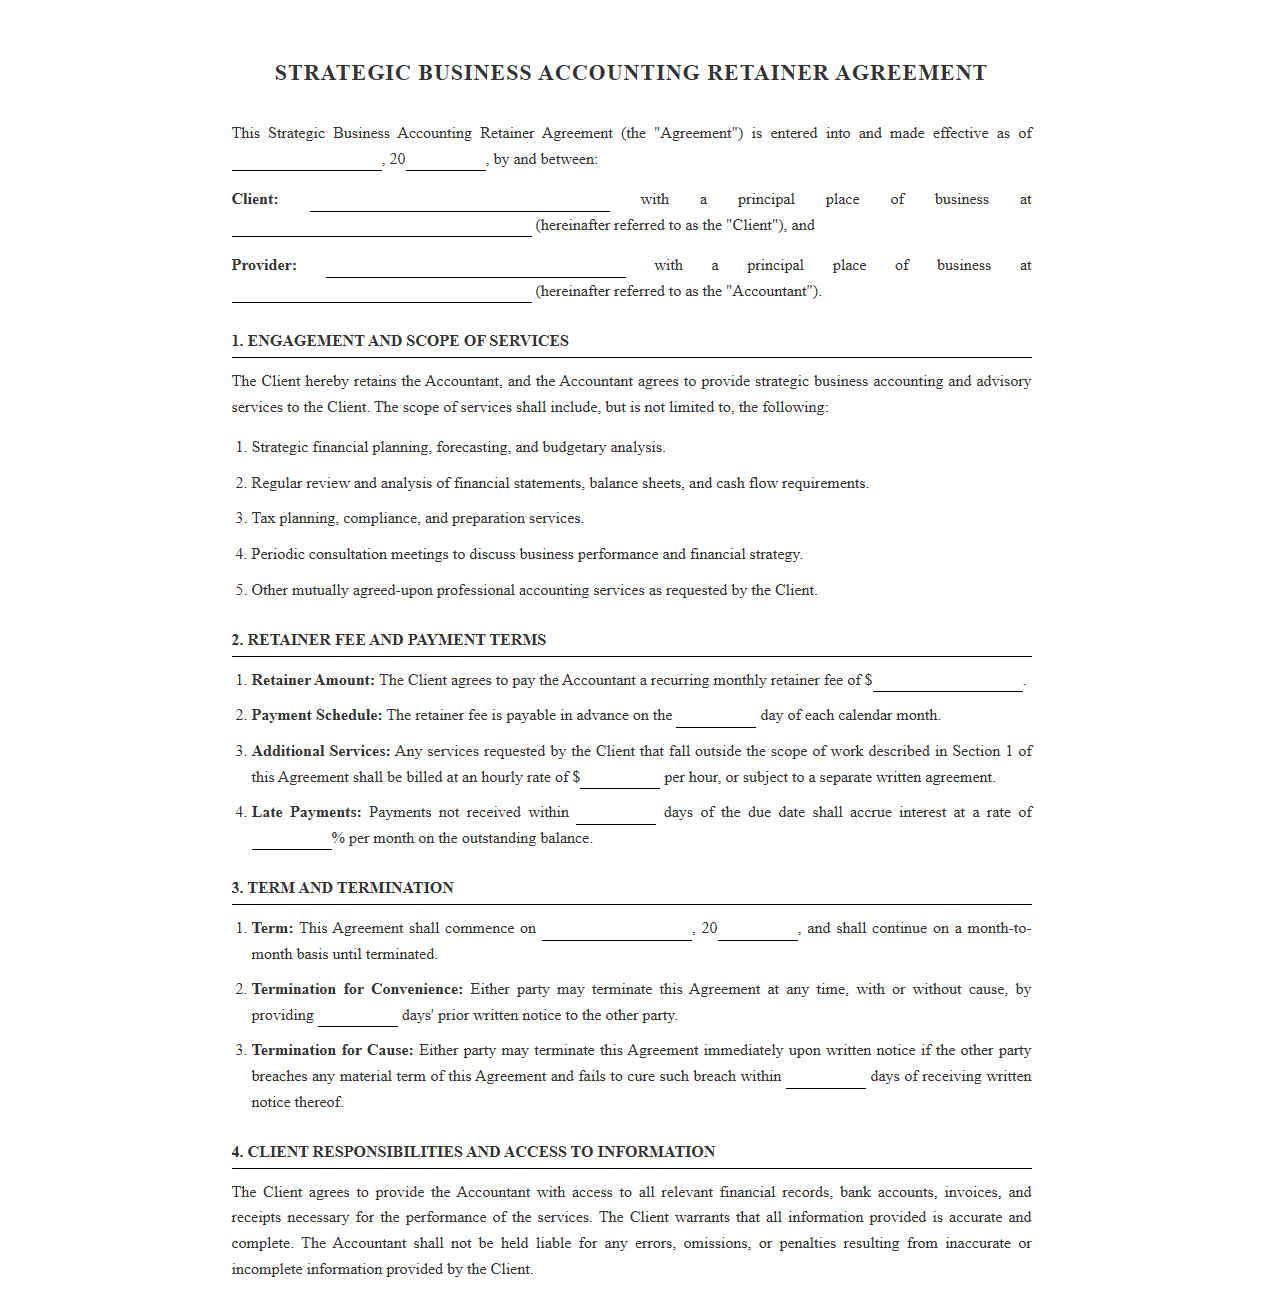
Strategic Accounting Retainer Agreement Template
 Download: .PDF
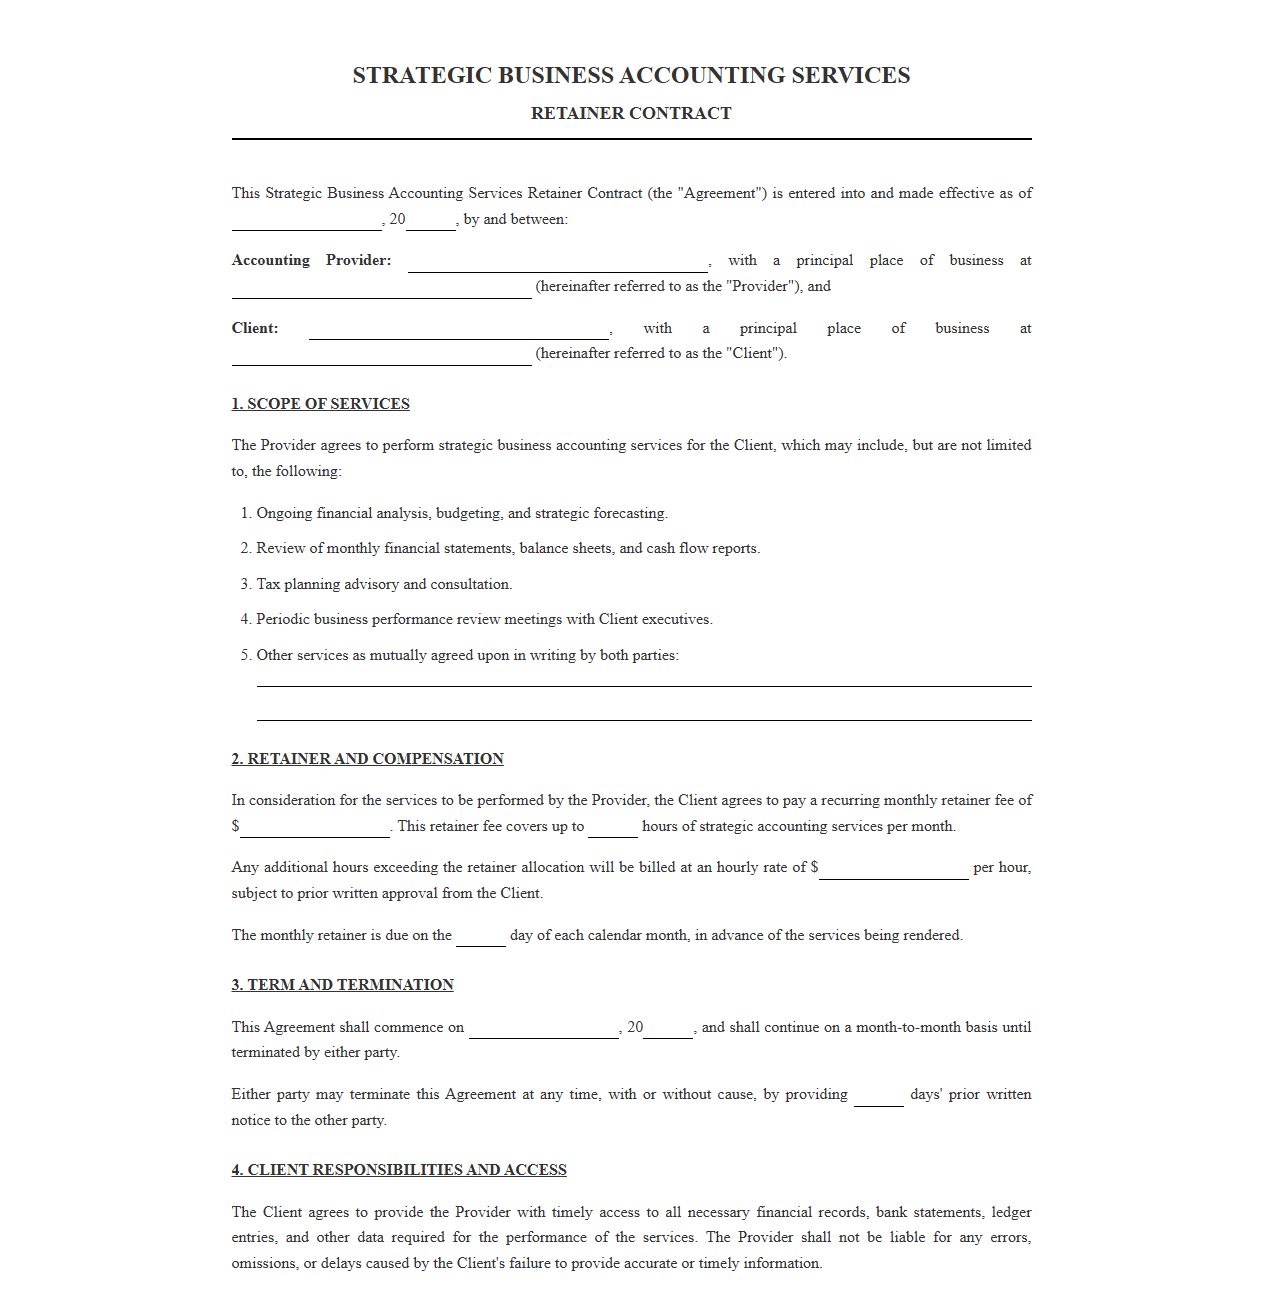
Strategic Business Accounting Services Retainer Contract
 Download: .PDF
Retainer Agreement for Strategic Business Accounting Services
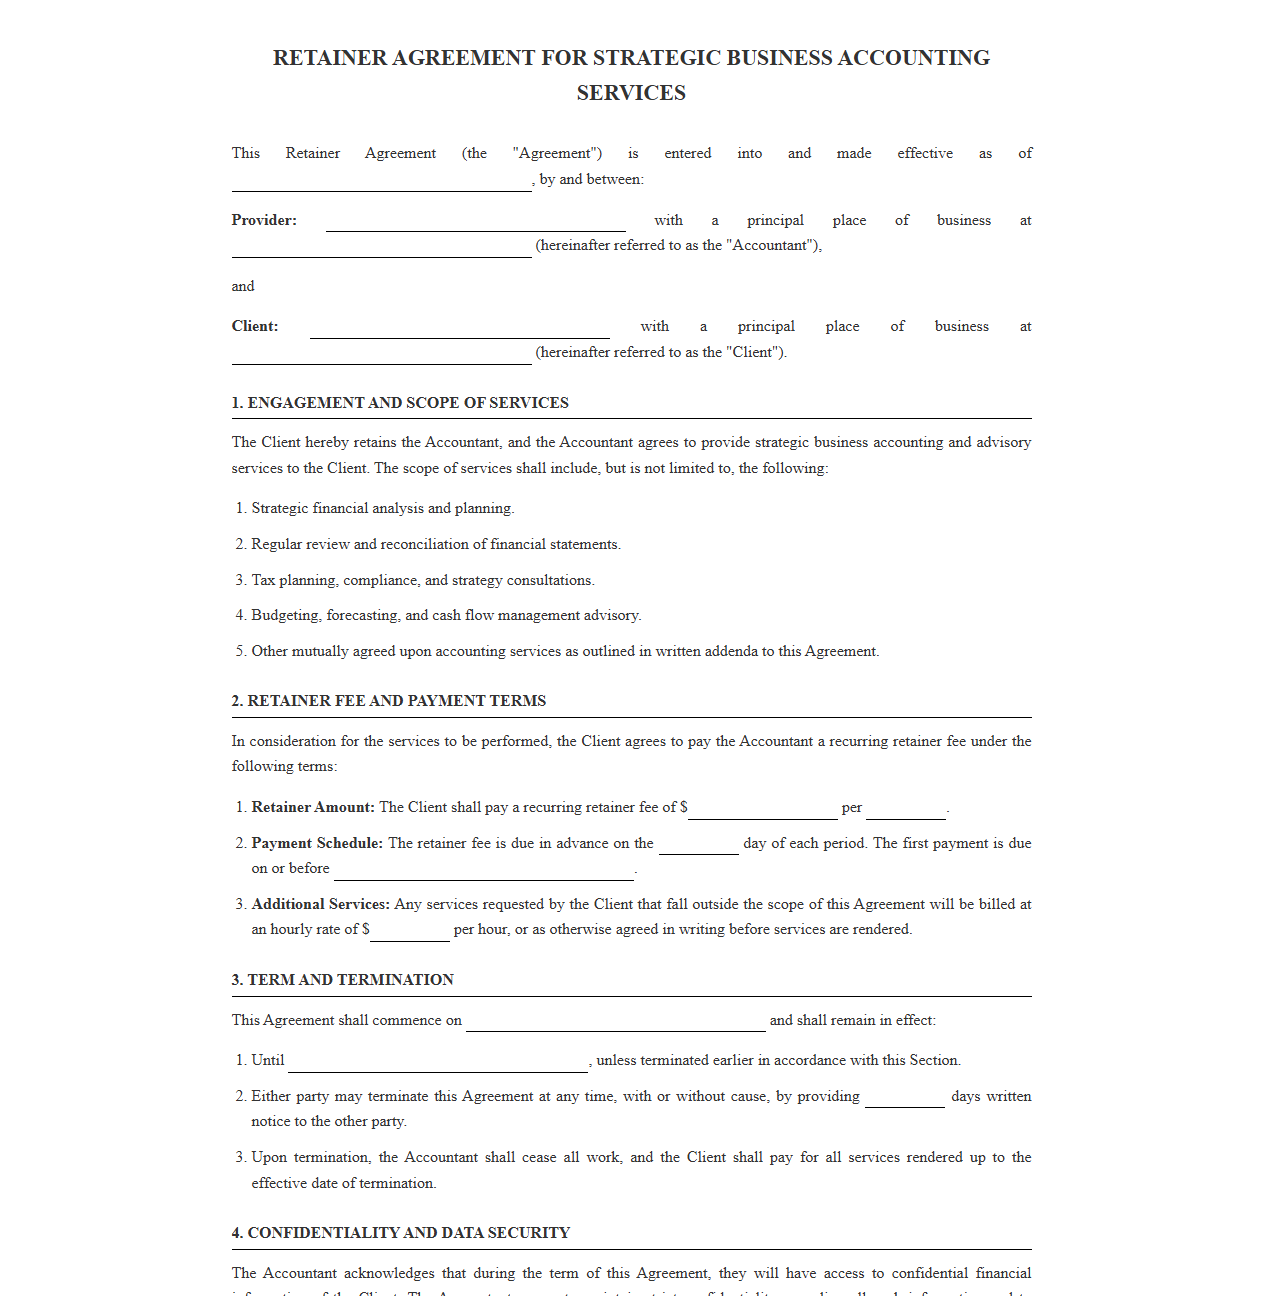 Download: .PDF
Corporate Strategic Accounting Retainer Contract Template
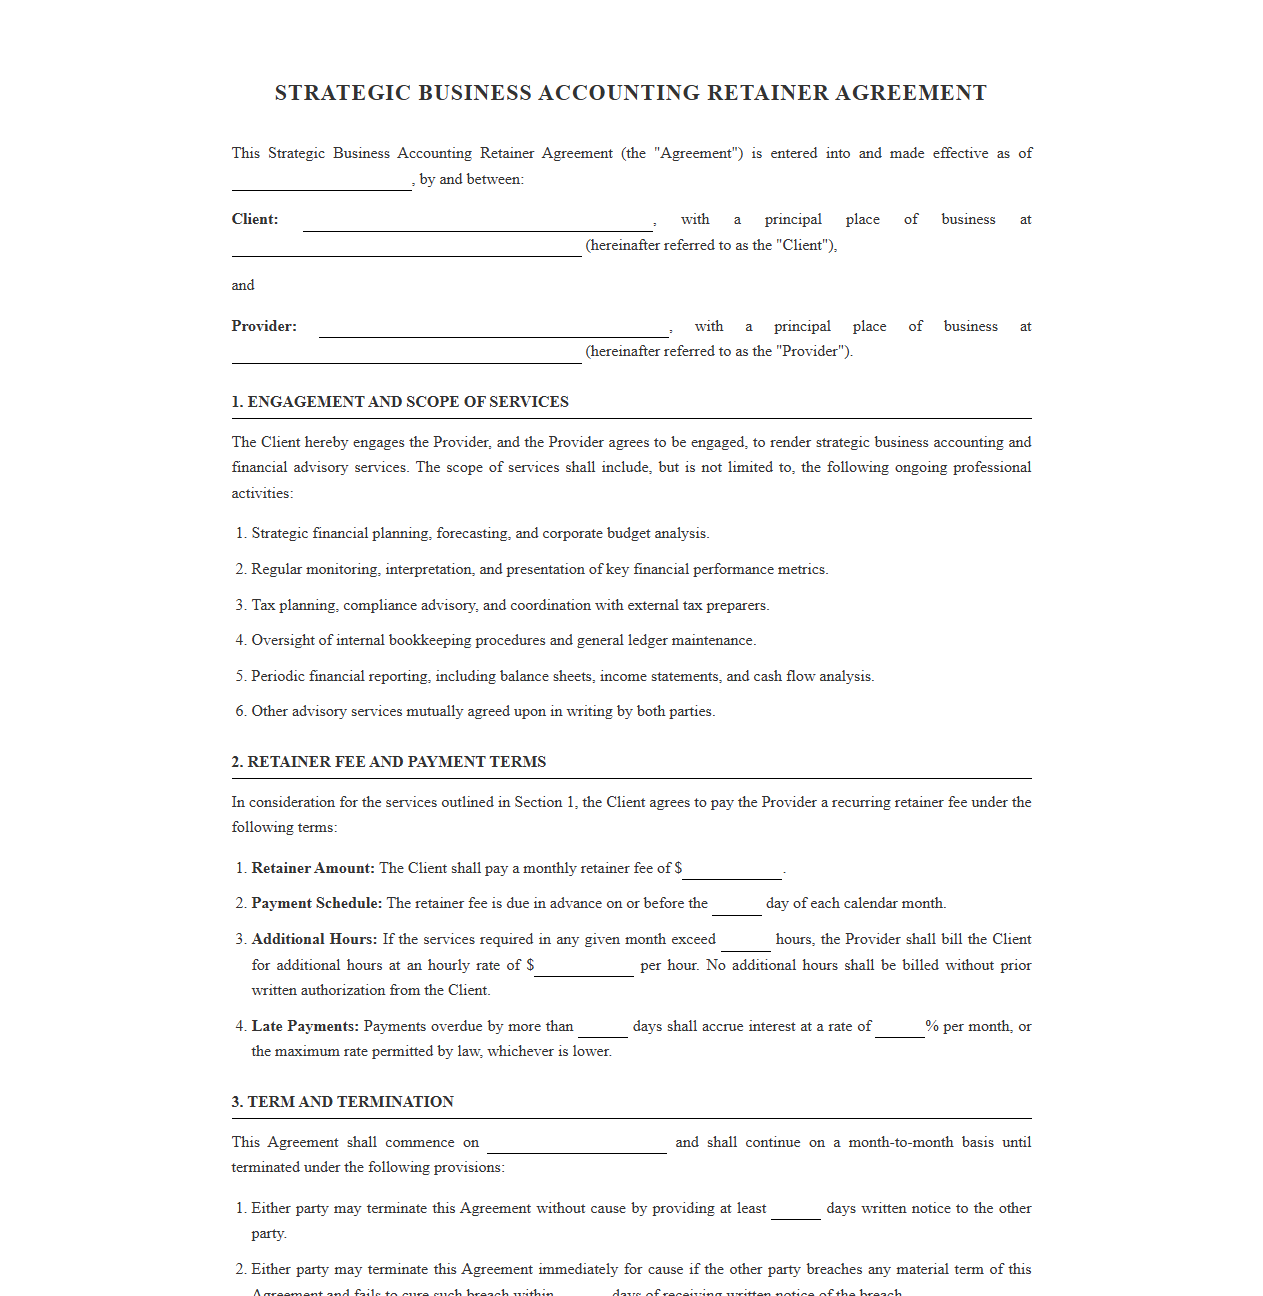 Download: .PDF
Strategic Financial Advisory and Accounting Retainer Agreement
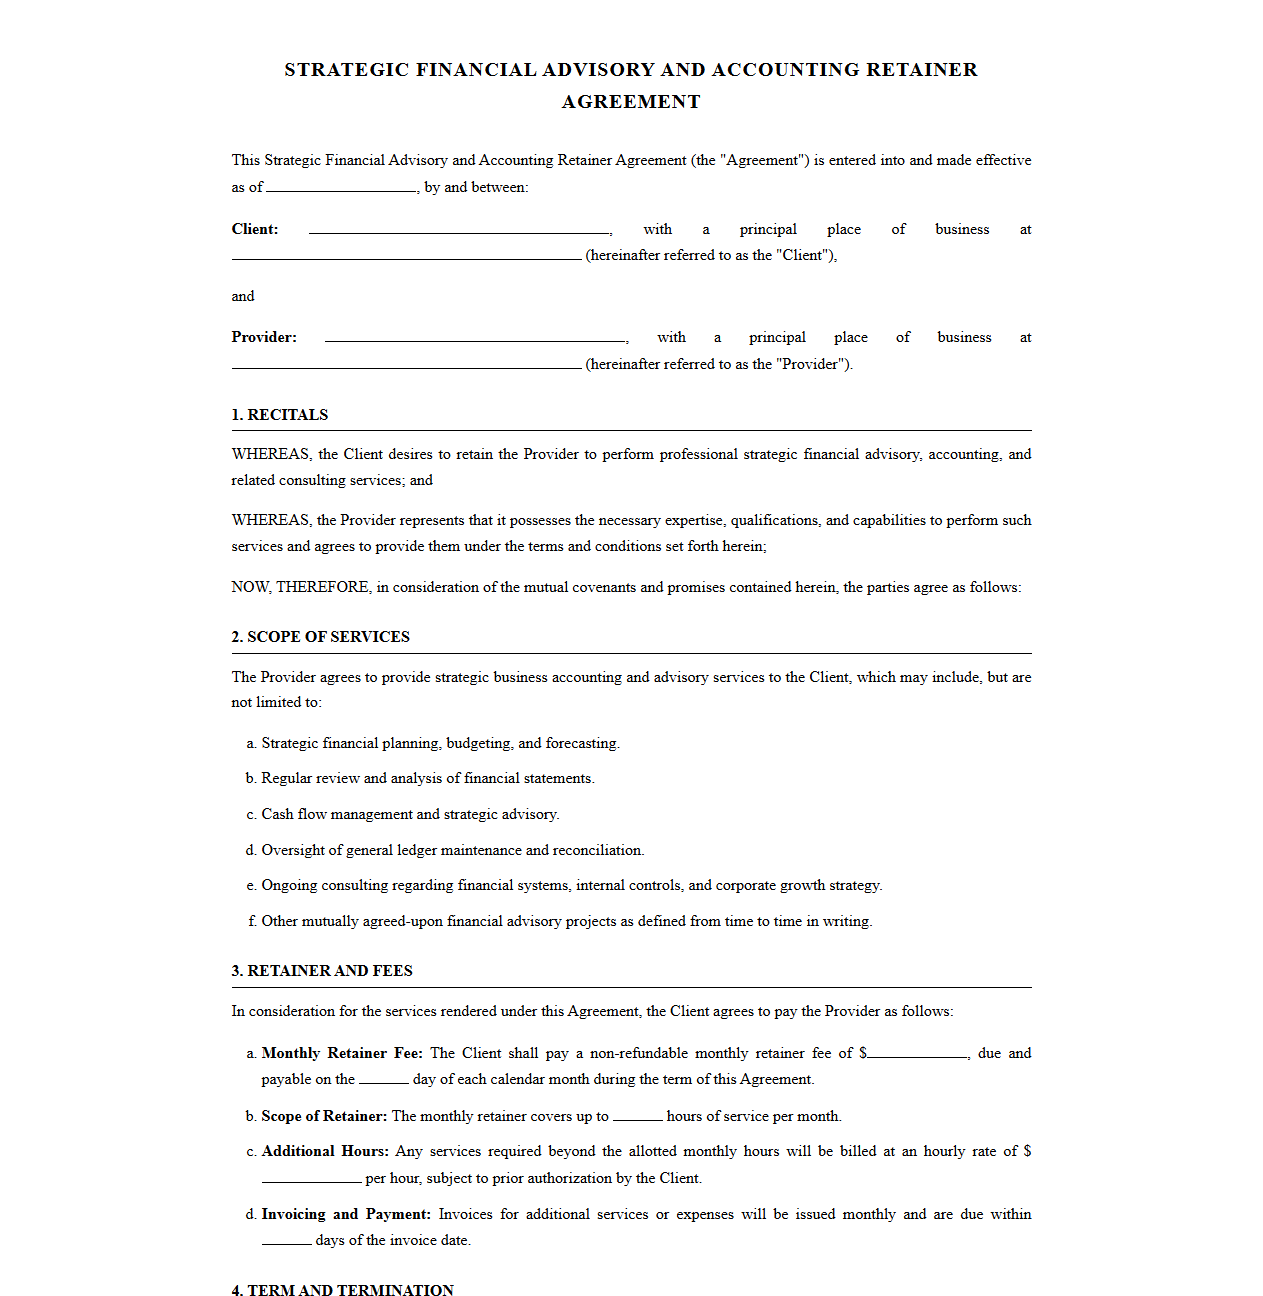 Download: .PDF
Strategic Business Accountant Consulting Retainer Agreement
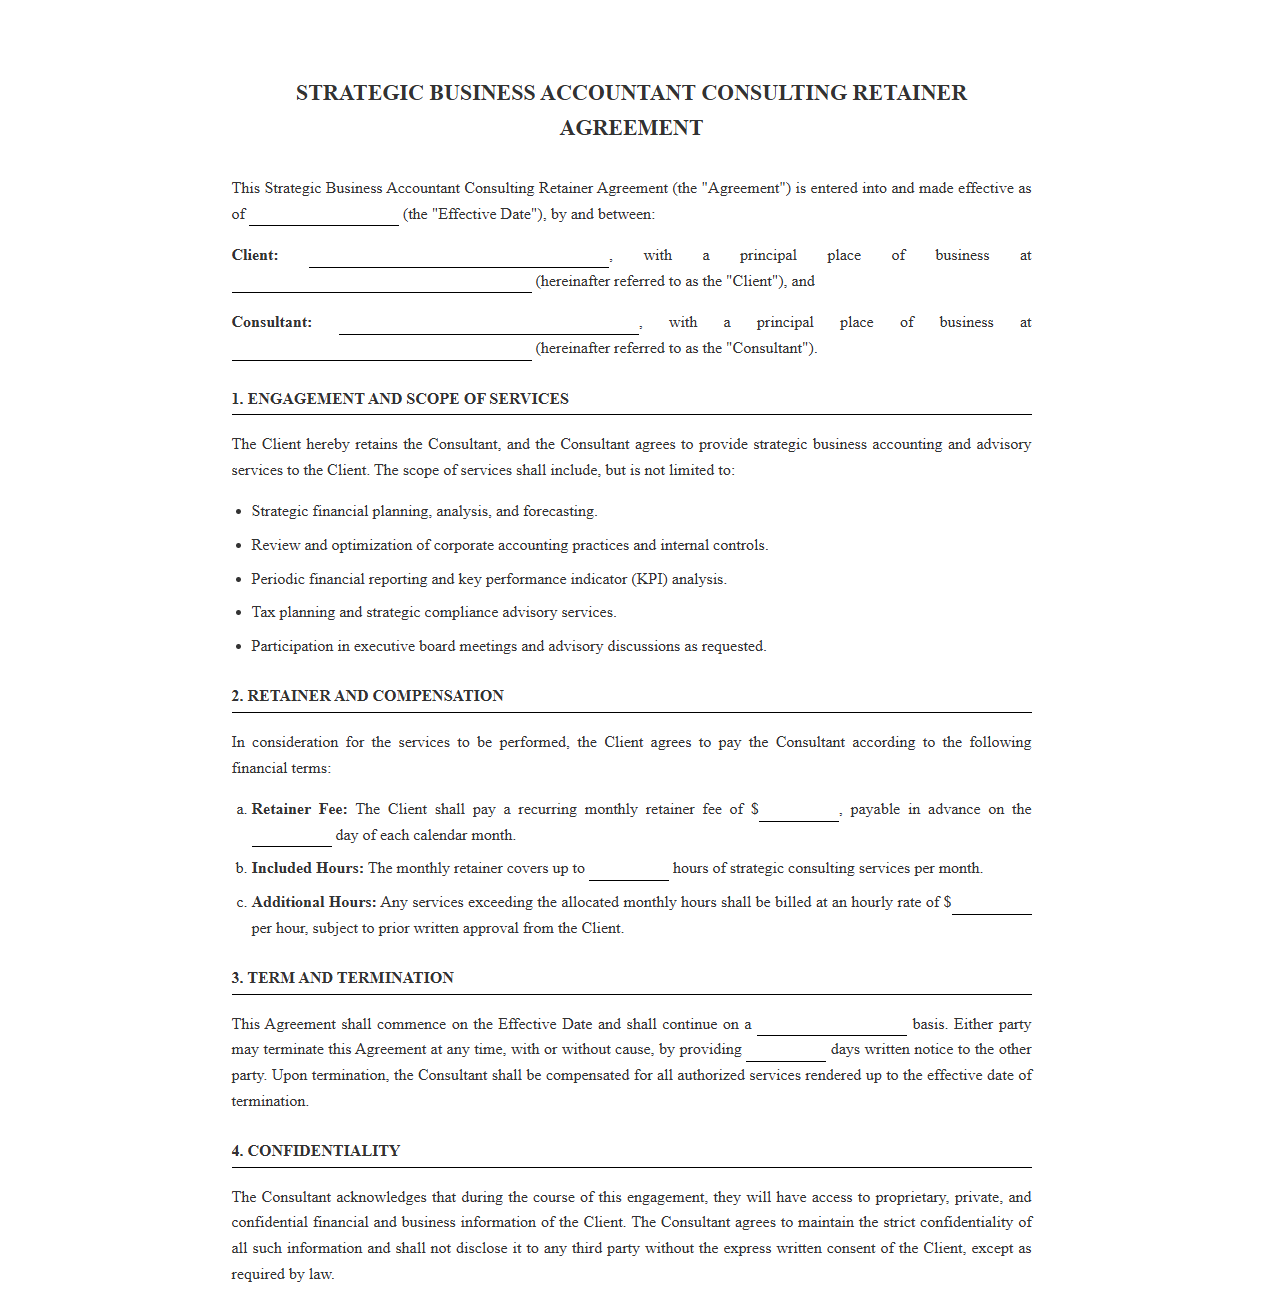 Download: .PDF
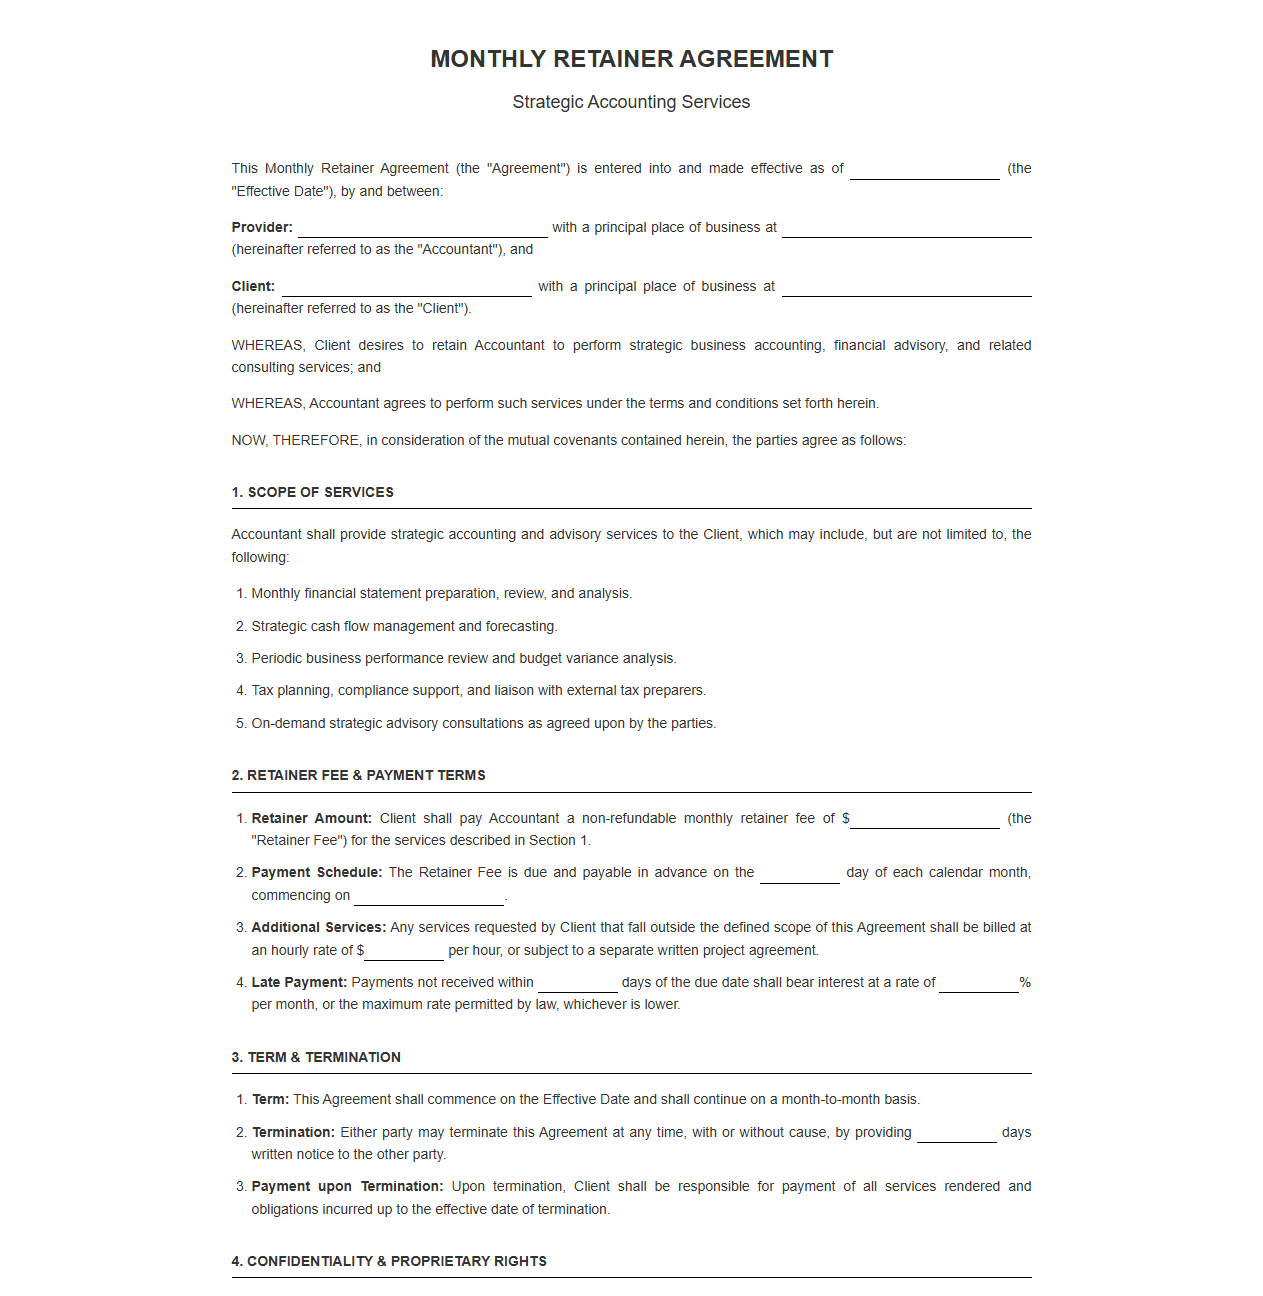
Monthly Retainer Agreement for Strategic Accounting Services
 Download: .PDF
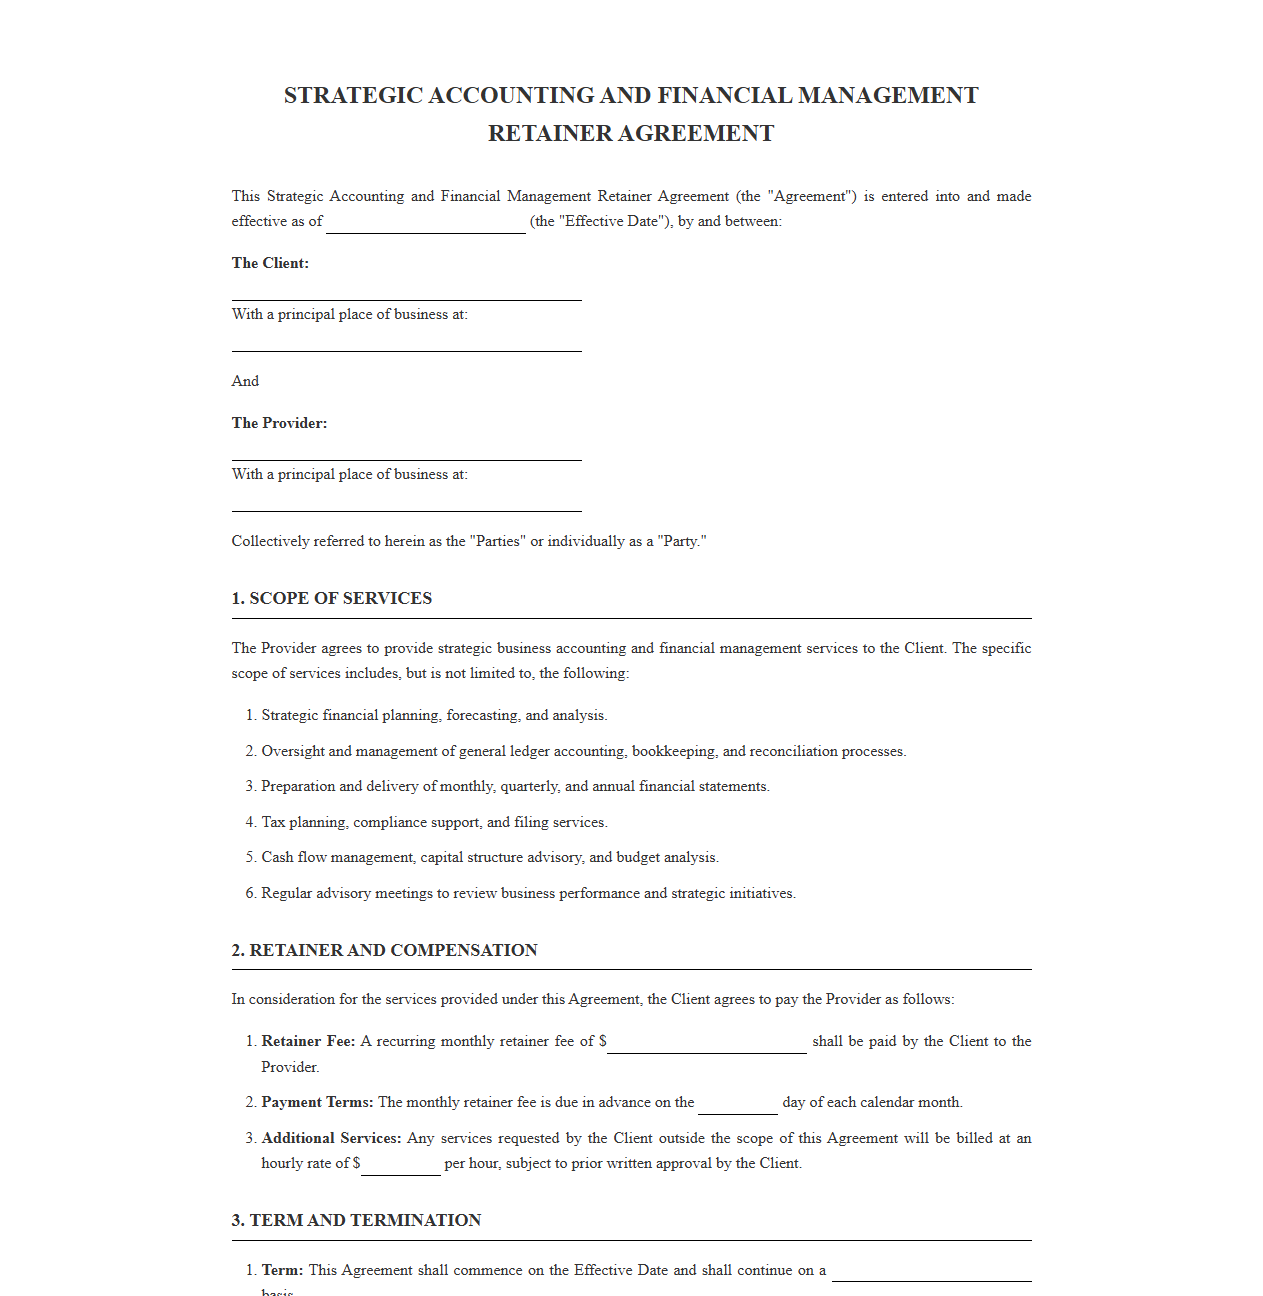
Strategic Accounting and Financial Management Retainer Contract
 Download: .PDF
Redefining the Accounting Relationship: From Transactional to Strategic
The modern business landscape demands more than backward-looking financial reporting. Traditional accounting retainers, once limited to routine ledger entries and periodic tax filings, have evolved into dynamic vehicles for strategic partnership. Today, forward-thinking organizations leverage their accounting relationships to secure real-time insights, proactive risk management, and high-level financial guidance. Transitioning to this modern retainer model requires a fundamental shift in perspective: both parties must view the agreement not as a grudge purchase for basic compliance, but as a collaborative framework built for mutual growth and shared accountability.
Defining the Scope: Distinguishing Core Compliance from Advisory Services
A successful retainer agreement rests on a foundation of absolute clarity. Without explicit boundaries, the line between routine maintenance and high-level advisory work quickly blurs, leading to mismatched expectations and strained partnerships.
Baseline Compliance Services
Core compliance services represent the essential financial hygiene of any organization. This category includes transactional accounting duties such as accounts payable and receivable processing, bank reconciliations, standard payroll execution, and routine state and federal tax filings. These tasks are historically focused and highly standardized, keeping the business in good standing with regulatory authorities.
High-Value Advisory Services
Strategic advisory services look forward rather than backward. This level of engagement includes fractional CFO coaching, cash flow modeling, capital allocation analysis, and tax optimization strategies. Unlike compliance work, advisory services provide the executive team with the predictive insights needed to scale operations, secure funding, or navigate complex market expansions.
Structuring the Fee: Choosing the Right Pricing Model
Selecting the appropriate pricing architecture ensures the accounting firm remains profitable while the client receives predictable, transparent value. Here are the three primary retainer models used today:
- Fixed-Fee Retainers: Best suited for standardized compliance and recurring bookkeeping tasks. Under this model, the client pays a set monthly rate for a predefined volume of transactions. This approach provides maximum budget predictability for the client and steady, forecastable cash flow for the firm.
- Value-Based Retainers: Designed for high-impact advisory work where the pricing is linked to the perceived or realized value delivered to the client, rather than the hours spent. Use this model when offering specialized services like M&A advisory or complex tax restructuring, aligning the firm's incentives directly with the client's financial outcomes.
- Tiered Retainers: A hybrid structure where clients choose from predefined service packages (e.g., Bronze, Silver, Gold). This model is highly effective for growing businesses, allowing them to scale their service tier up or down as their internal resources and financial complexity change over time.
Establishing Performance Metrics and Service Level Agreements (SLAs)
To maintain accountability, the retainer agreement must define what success looks like through objective key performance indicators and clear communication timelines.
| Service Area | Key Performance Indicator (KPI) | Target Service Level Agreement (SLA) |
|---|---|---|
| Financial Reporting | Delivery of monthly financial statements | By the 10th business day of the following month |
| Client Communication | Response to urgent email and phone inquiries | Within 4 business hours |
| Payroll Processing | Accurate direct deposit initiation | 48 hours prior to the designated pay date |
| Tax Filing | Completion of draft tax returns for review | 30 days prior to the official filing deadline |
Standardizing Billing Cycles and Administrative Mechanics
Administrative friction can quickly erode the profitability of an advisory relationship. Implementing automated systems and clear payment rules protects cash flow and keeps the focus on strategic delivery.
To eliminate manual invoicing bottlenecks and ensure timely collections, both parties should agree to a standardized payment workflow at the onset of the engagement.
- Invoice Generation: Retainer fees are invoiced in advance on the 1st of each service month.
- Automated Collection: Payments are processed automatically via ACH debit or credit card on file on the 5th of the month.
- Replenishment Terms: For variable project work outside the core retainer, a replenishment threshold is set, authorizing automatic billing when the project deposit falls below 20% of the initial estimate.
Preventing Scope Creep: Clauses for Adjustments and Out-of-Scope Work
Scope creep is one of the most common points of friction in professional relationships. It occurs when minor, ad-hoc requests accumulate over time, pulling resources away from strategic goals without corresponding compensation.
"Any service requested by the Client that is not explicitly detailed in Exhibit A of this Agreement shall be deemed Out-of-Scope Work. Such work will be subject to a separate written Change Order and billed at our standard hourly rate of $250/hour, or as a fixed-fee project, and must be approved by both parties before work commences."
Incorporating a formal change-order protocol protects the integrity of the original contract. By defining how out-of-scope work is identified, estimated, and billed, both the firm and the client can navigate unexpected business needs without risking resentment or financial loss.
Ensuring Continuity: Termination and Transition Protocols
A well-drafted agreement must anticipate the end of the partnership, ensuring that any eventual offboarding is executed with professional care and minimal disruption to the client's operations.
To protect both parties, the agreement should mandate a minimum 30-day or 60-day written notice period for termination without cause. This window provides the necessary runway to close out current billing cycles, reconcile open accounts, and hand over critical financial historical data securely.
Operational Warning: All intellectual and financial data remains the sole property of the client, provided that all outstanding invoices and final reconciliation balances have been settled in full according to the terms of this agreement. Access to shared accounting software systems will be revoked immediately upon the final day of the transition period.
Leave a comment